
Global Salon: Building the Rails for a $3.5 Trillion Empire
Apex Group’s Peter Hughes on AI hype, tokenization, private credit and what Jeff Bezos got wrong.
Peter Hughes founded Apex Group Ltd. in Bermuda in 2003. Today, it manages more than $3.5 trillion in assets across 52 countries, with 100-plus offices, 13,000 employees, and 90 regulatory licenses—growth built on more than 50 acquisitions over eight years and a bet Hughes made roughly five years ago that traditional finance and decentralized finance, or DeFi, were headed for convergence, not collision.
In this conversation with Global Finance, Hughes—who spent time at KPMG and Hemisphere Management before founding Apex—traces that bet from BlackRock Inc.’s decision to add bitcoin to its balance sheet to Apex’s enabling the development of the compliance-focused Layer 2 blockchain initiative, T-Rex. He pushes back on Jeff Bezos’s prediction of an artificial intelligence-driven labor shortage, defends private credit against claims that it’s a broken asset class, and argues that traditional exchanges and crypto-native platforms are racing toward the same end state.
Global Finance: Was there a critical moment or aha moment that sparked a major change in your firm?
Peter Hughes: Absolutely. Bridging traditional finance and DeFi has been my focus for five years. Before that, we serviced crypto funds investing in bitcoin, working strictly with regulated partners to manage risk. I wasn’t sure if crypto would go mainstream, but seeing BlackRock put bitcoin on its balance sheet five years ago proved it was here to stay. That was the turning point.
We later ran a project with a client, lowering a fund’s subscription minimum in Luxembourg from 1 million Swiss francs to 1,000 so more people could access it. That was great, but our real value proposition lay in our scale—we operate across 50 countries under 35 regulators.
So you take something that’s high risk, like crypto, and then you say, “Well, actually, if it’s regulated and you’ve got clean AML around it, it’s a digital asset, and then it becomes accessible for everyone.” From there, I focused on building the distribution rails. We are now approved in 20 jurisdictions for on-chain transfer agency, enabling seamless settlement of digital securities. Our target by next year is a platform giving funds access to 50 new distribution channels across wealth, retirement, retail, and crypto-native channels. As tokenized money market funds transition to a 24/7/365 operational model, the broader asset world will inevitably follow. Building these locked-in distribution rails today ensures a highly valuable position for the future.
GF: Has blockchain changed the way your business operates, and do you see it likely becoming more integral in the future?
Hughes: Blockchain is the end state for how everything ends up; crypto is just a small piece of what we service. We focus on the regulated side—digital assets backed by clean AML.
My view is that everything will move on-chain, creating cheaper fund structures and frictionless finance. But that only works in a regulated environment. We favor public, permissioned chains because you know where the money is coming from, where it’s going, and that it’s clean. We supported the launch of the Layer 2 compliance initiative, T-Rex, which is operated by an independent foundation, to validate that every transaction moving across chains is fully verified.
I’m looking toward a world where custody, administration, transfer agency, and distribution all sit on-chain and interlink seamlessly—yielding faster speeds, higher volumes, and lower costs. So we’re all-in on blockchain. Crypto is part of it, but the core focus is digital assets: regulated securities that trade 24/7/365 like crypto, but with the institutional guardrails built in.
GF: Do you expect any relaxation for crypto in China?
Hughes: It’s difficult to tell, but stablecoins will eventually replace fiat on corporate balance sheets because they function as both payment tools and yield-bearing instruments. Their growth is currently limited by regulation—like MiCA in Europe and the Genius Act and Clarity Act in the US—designed to protect traditional bank deposits. But tokenized money market funds already offer the same yield without the payment functionality. It’s only a matter of time before yield- bearing stablecoins gain widespread adoption.
GF: Will Apex pursue any more acquisitions in the near future?
Hughes: We don’t need any new acquisitions. I bought 50 businesses over an eight-year period, each designed to add a new technology, open a new geography, or add a new product set. Every one is handpicked to complement what’s already there, so you can cross-sell both ways. People look at that from the out- side and say we just buy businesses—but for the last three years, it’s really been distribution businesses and technology businesses, aimed at building the technology rails to be the distribution leg for asset managers globally. That’s the direction I’ve always been moving in not just being good infrastructure and doing a good job for clients like other asset servicers but layering in and distributing their products to help them get bigger. That’s when you go from being a vendor to a real partner—when you’re shifting their P&L upwards. In September, I announced we’ve brought in a head of product from Revolut, because I want us building products and releasing them in eight-week sprints. If you’re not moving that fast in a tech evolution like this, you get left behind. So now it’s about building the technology of the future ourselves, rather than buying it in. We’re already servicing tokenized money market funds that run 24/7/365, fully on our own tech stack—and we want to keep enhancing that.
GF: Will there be fewer workers in the future due to AI or tech innovation?
Hughes: I hosted a conference for our clients in London and told them people are running an AI race that ends in a trap—you embed AI across everything, decide you don’t need people any- more, and suddenly your AI costs go up tenfold. That kills businesses. I’m not rushing into that trap. I’m adding AI thoughtfully, so data flows seamlessly end to end instead of being pushed and pulled by people, and I’m using it to build incremental products that add value for clients. I don’t think we’ll have fewer people, and I don’t think our salary costs go down—I think the same people will service more revenue. What it does change is who we hire. Instead of people doing manual work in Excel, we can bring in people who add real thought leadership, PhDs who help us think about how to value funds for the future. It doesn’t get cheaper for us. We just get better talent.
GF: Jeff Bezos insists AI will cause a labor shortage.
Hughes: I don’t see how it leads to a shortage. In places like India, where 18 million people enter the workforce every month, it’s exactly those keying-into-dashboards, keying-into-keyboards jobs that a lot of that workforce would traditionally have done—and a lot of people there see AI as a real threat because of it. So no, I don’t agree. When the manual layer goes, even my son—he’s at university in the UK—asks me, well, what job is he going to do when he leaves? He’s not going to start as an accountant, not going to start as a lawyer, because the bottom rungs of the ladder are being taken out. Firms are only hiring the top 10% into those entry positions now, whether that’s investment banking or what- ever else. So I don’t see it. Bezos is obviously very successful, but I don’t see how he’s right on this.
GF: What’s your view of the turbulent private credit space?
Hughes: The turbulence comes from growth—the volume of investor capital coming in but coming into a format that doesn’t work: a mismatch in liquidity. If you want to get out, you can’t, and that’s a structuring problem, not a problem with underly- ing returns. I still think private credit is a great asset class—10% annualized returns with low volatility. The friction came from structuring it into interval funds, which isn’t the right structure for private credit. When people raised concerns, the response was “wait for the next valuation, in four months you’ll see there’s no problem”—but the technology exists for weekly or daily valuation. If that information had come through faster, people wouldn’t have panicked. Instead, redemptions piled up and it became a vicious circle. The asset class itself is as strong as it always was—it was the structure, and the slow information flow, that caused the problem. And there’s no real slow down here: Revolut recently announced that Ares and Apollo are making their private credit funds available on the platform, with a €1 minimum investment. That’s not just a headline—it shows both the confi- dence in the asset class and what’s now possible in terms of democratizing it.
GF: Can we say that there is also an element of democratization of finance in what you do?
Hughes: That’s been a theme for the last three or four years — democratization, giving more access. But I think the way access happens will get more appropriate and more sophisticated going forward. People talk about interval funds in the U.S. as democratizing private markets, but for me that’s the wrong structure — it’s exactly why you saw noise around private credit funds: they were structured for retail, but there was a mismatch in liquidity. I think democratization gets broader and more sophisticated from here. It started with high-net-worth and wealth; as regulators get more comfortable, it’ll extend into wealth, retirement and retail. Think about why a private equity fund is high risk: it’s illiquid, you’re locked in for seven to ten years, it has a big ticket size, and it’s valued infrequently. Take away those three barriers and it trades like a normal equity, with a normal equity’s risk profile — which means it should be accessible to retail. Regulators are starting to understand that, though it’ll take time.
Anthony Noto covers corporate finance and private credit. Contact him at anoto@gfmag.com
Best Buy launches a gamers hub ahead of GTA 6 release and holiday rush (BBY:NYSE)

Robert Way
Best Buy (BBY) announced the launch of its Best Buy Gamers hub in beta. The free online hub was highlighted as putting gaming content, gear, special offers, sweepstakes, and events all in one place, with the goal to save gamers from checking several sites for
1-800-Flowers.com closes on asset sales (FLWS:NASDAQ)

L Feddes/iStock via Getty Images
1-800-FLOWERS.COM (FLWS) announced that it has completed the previously announced $45M sale of PersonalizationMall.com and Things Remembered to PlanetArt, LLC, a leading global technology platform for personalized, made-on-demand e-commerce products.
The company said the completion of the transaction represents another

SoftBank 5-Year CDS climbs to 432 bps on AI debt, acquisition concerns (SFTBY:OTCMKTS)
SoftBank Group’s (SFTBY) 5-year credit default swaps have climbed to 432 basis points, their highest level in four years, as worries mount over AI-related funding and a possible large acquisition. The spread has widened by more than 30 basis points since it
U.S. to allow ‘dark fleet’ tankers to ship oil legally

Alexey Bakharev
The U.S. government will authorize the sale of sanctioned oil tankers, allowing these vessels to ship crude legally to help rein in soaring shipping costs, Energy Secretary Chris Wright said during a Citadel Securities event on Monday.
He noted that “a
Nvidia to back four German AI startups as part of near-$10B European push (NVDA:NASDAQ)
Nvidia is stepping up its investment in Europe’s AI sector, announcing plans to back four German startups: Agile Robots, Avelios Medical, Mirelo, and Reflex Aerospace. The company did not say how much it will invest in each. The announcement came as German Chancellor Friedrich Merz urged businesses, especially
BlackRock’s Fink sees AI shortages, not a bubble, as the bigger threat (BLK:NYSE)
BlackRock (BLK) CEO Larry Fink commented on the AI bubble, saying “The demand for compute is growing faster than supply. I don’t see anything but a bubble. I see greater shortages.”
Fink added, “Shortages of skilled trade, shortages of power and energy, shortages
Activist investor Starboard builds stake in Solstice, urges focus on core business, FT reports (SOLS:NASDAQ)
Activist hedge fund Starboard Value has built a stake in Solstice Advanced Materials (SOLS), the Financial Times reported, few weeks after the company’s $14.5B merger with Element Solutions was scrapped on August 27. Solstice, which was spun off from Honeywell, was valued at $9.4 billion
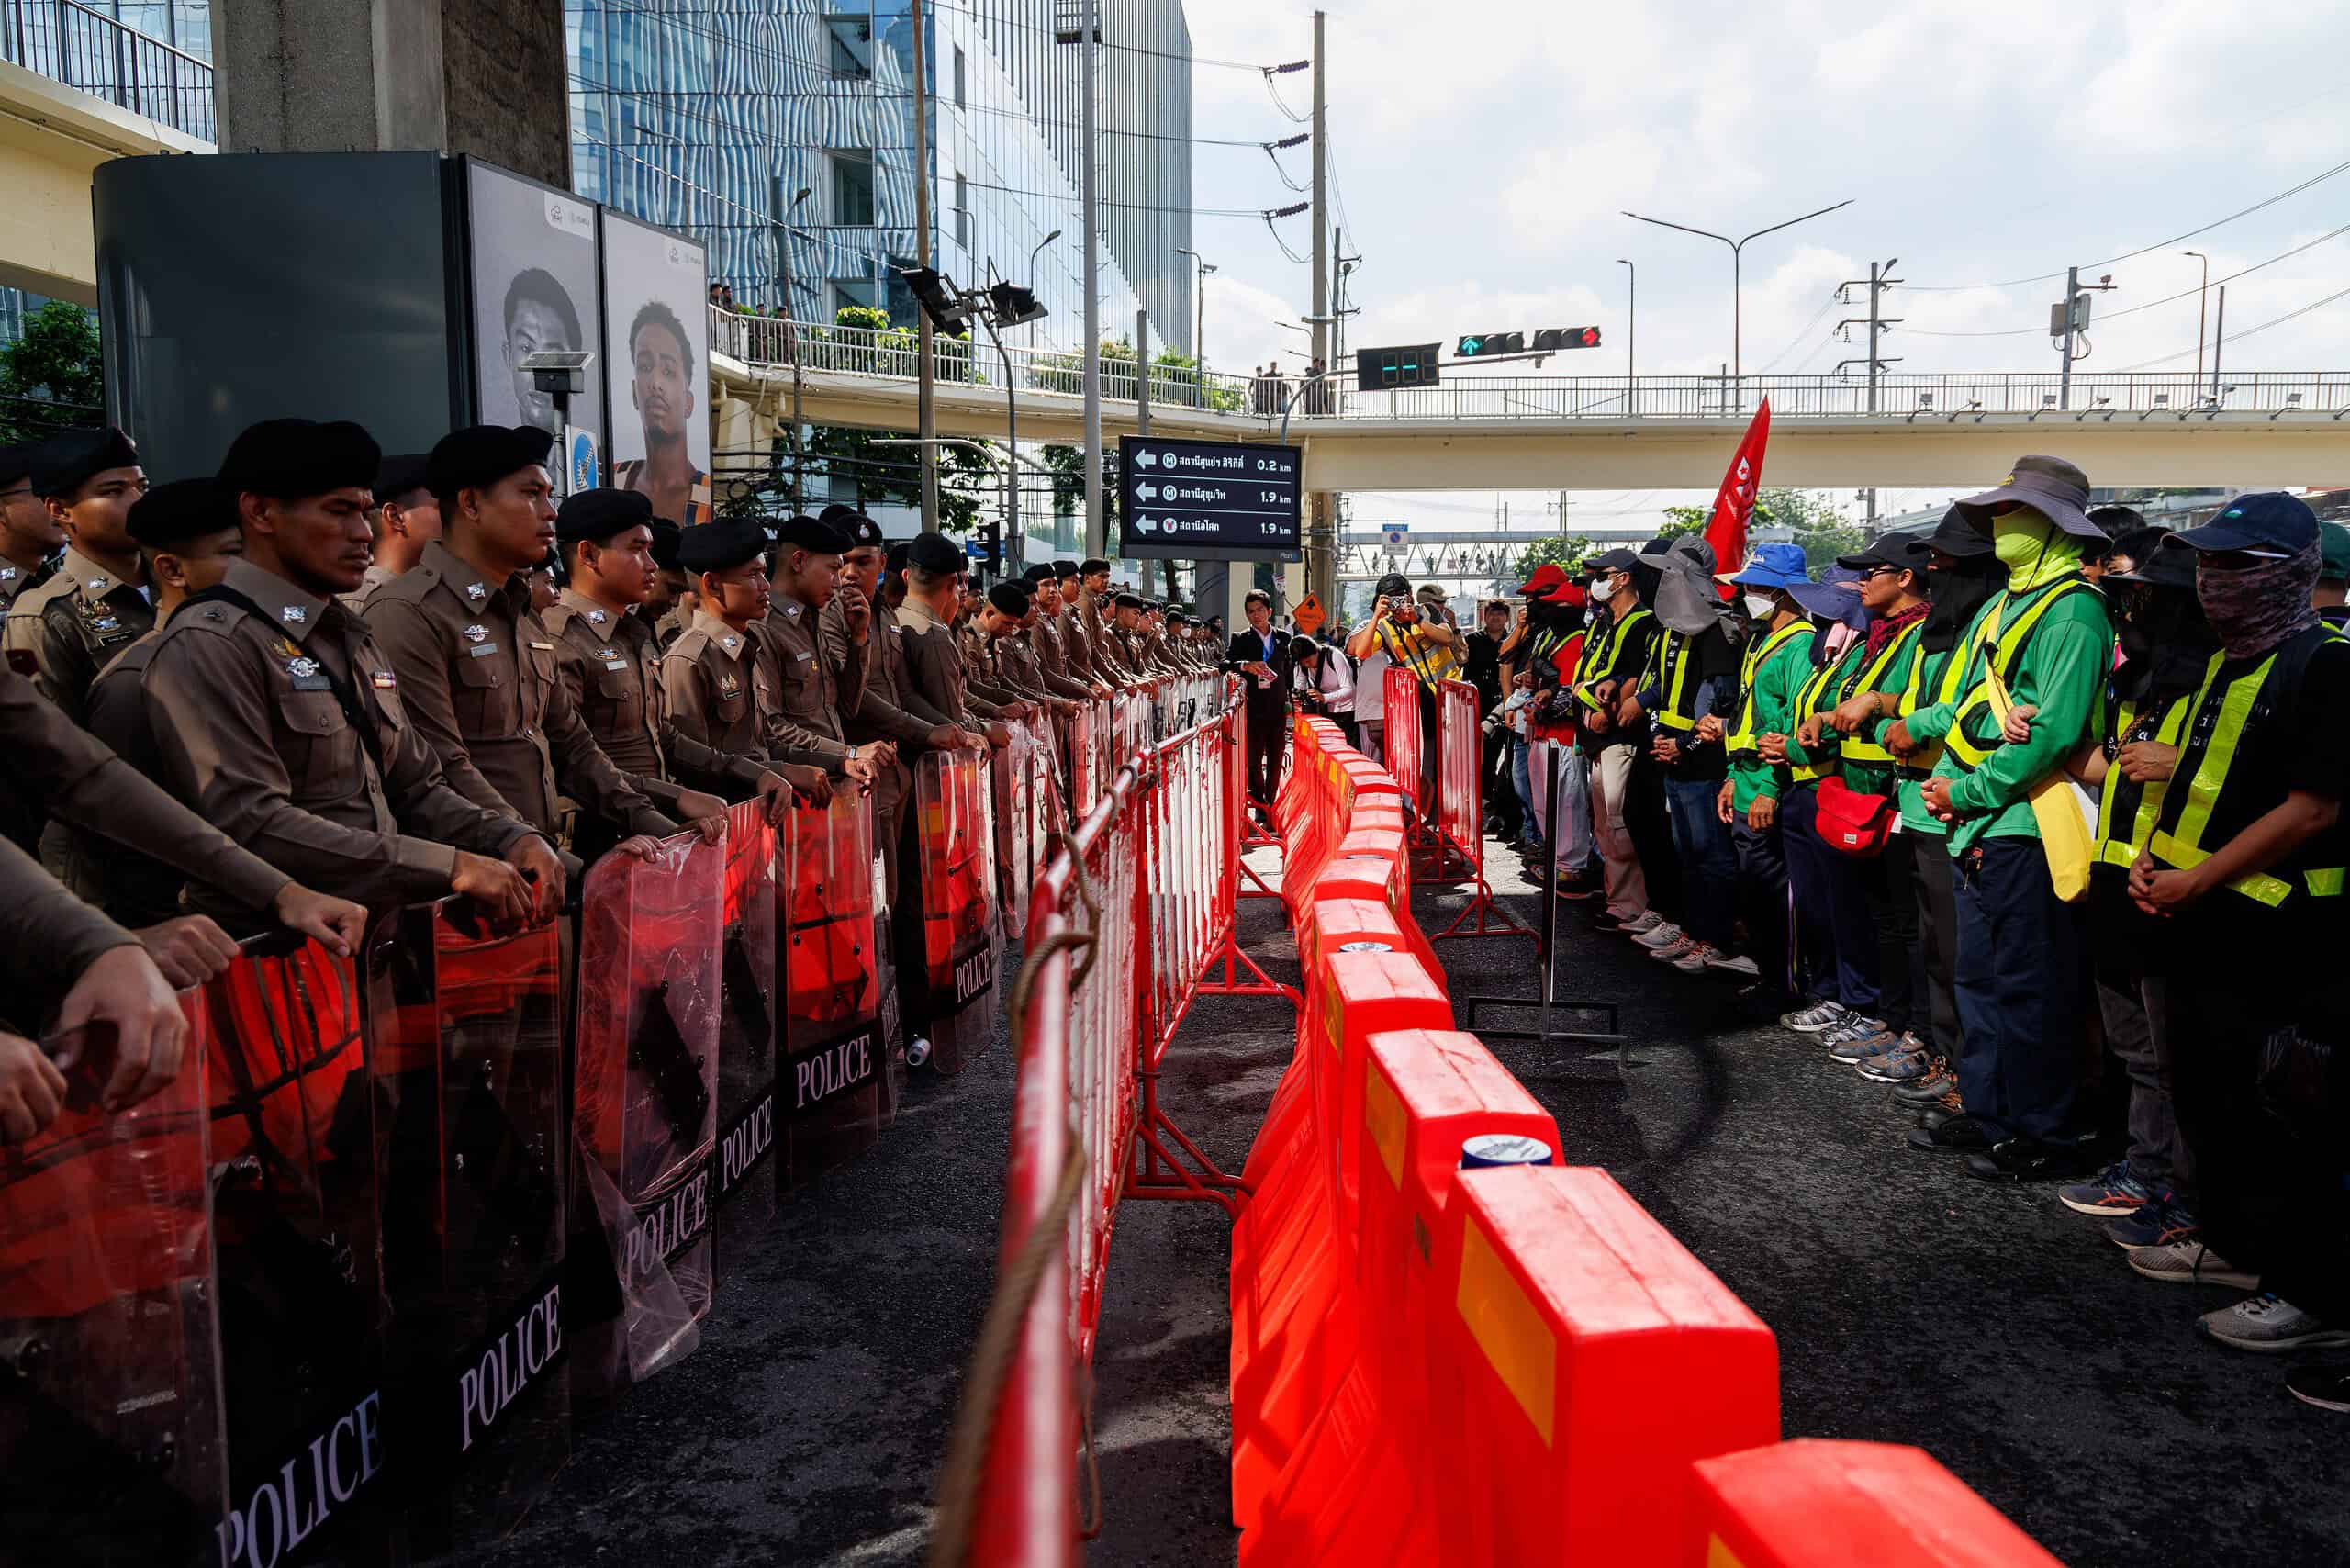
Global Economy Struggles to Achieve Balance in Divided Times
As leaders gathered in Bangkok, discussions highlighted the fractures between economic winners and losers.
The global economy appears to be on a fragile foundation, and the finance ministers of Argentina, Greece, Nigeria, and Thailand agree that all economies should get their houses in order.
“Ideally, when you put your fiscal house in order, it shouldn’t be because of experience,” said Kyriakos Pierrakakis, the Minister of Economy and Finance for Greece and President of the Eurogroup, during a panel discussion that took place at the annual International Monetary Fund (IMF) and World Bank meetings in Bangkok. “It should be because of inspiration.”
Although the IMF projects global economic growth at 3.1% throughout 2026, its composition has changed.
The global economy is increasingly split between a handful of nations with AI-driven economies and those without. The IMF has upgraded AI-driven economies while it downgraded many fuel-importing nations and those affected by war.
However, AI may be a curse and a blessing.
“The global economy’s dependence on AI investment enthusiasm creates a vulnerability, with risks of disappointment cycles, as per Amara’s Law, and the potential loss of human control over AI systems,” said fellow panelist Kristalina Georgieva, IMF Managing Director.
Exacerbating the situation are growing excessive export-import imbalances. Developing countries struggle to compete with export-oriented countries that have built their manufacturing base over decades. At the same time, developing economies struggle to compete for capital against an economy that takes in capital for productive use but leaves little for the rest of the world.
“The biggest source of imbalance comes from the two largest economies, China and the United States: China not having enough domestic consumption, exporting a lot, and the U.S. the opposite, not saving enough, having a high level of debt and deficit,” she said.
Achieving Resiliency
It’s best for a country to put its fiscal house in order during periods of economic calm, but human nature tends to act only amid a crisis, said Georgieva. “Nonetheless, we have excellent examples of countries that have brought back fiscal discipline. They have taken the reforms, structural reforms that promote growth.”
The formula for building a resilient economy is discipline, transparency, and consistency, which, according to Olayemi Cardoso, Governor of the Central Bank of Nigeria, build credibility, said Cardoso, who spoke on the panel.
To address a persistent currency crisis and the loss of investor confidence, Nigeria eliminated its fuel subsidy in 2023 and, in June 2024, implemented multiple foreign exchange rates.
“These should have been done a long time ago, but they were not done,” he said.
The central bank also enacted an aggressive 800-basis-point (bp) increase in 2024, including a single 400-bp increase. As a result, the central bank brought inflation down by about 20 percentage points, to about 15%, and raised foreign reserves to their highest level in 18 years.
“Painful though they were, it brought back credibility because we were consistent in saying certain things and doing them,” said Cardoso.
In Argentina, the government eliminated its fiscal deficit, which was 5% of GDP, by cutting spending by 30% and growing the economy for the third consecutive year through increased exports. These measures helped bring inflation down to approximately 30% today from 211% in 2023.
“We have a fiscal surplus, a commercial surplus, and a current account surplus,” said panelist Luis Caputo, Argentina’s Minister of Economy. “The way we will continue in the following years will be by fulfilling our goal of reducing the weight of the state in the economy.”
Thailand aims to maintain macroeconomic stability amid an energy shock and a few years of supply-chain fragmentation. Even as part of the AI value chain, it has kept sovereign bond yields low.
“Our government 10-year yield is around 2.3%, so much lower than the U.S. and Europe, thanks to fiscal discipline,” said Ekniti Nitithanprapas, Thailand’s Deputy Prime Minister and Finance Minister.
The Thai government has also made structural changes to turn these economic shocks into opportunities for low-income small and mid-sized enterprises by helping them adapt to current shocks and prepare for future ones.
It also expects to work more closely with its ASEAN partners to expand trade and investment opportunities to establish a resilient economy.
“For example, 22% of our trade is with ASEAN countries compared to 60% for the E.U.,” he said. “So, we could do more trade together.”
In Europe, the EU is working to close gaps in its pan-European reforms, which each member state must implement.
“Fragmentation in Europe is a strategic tax,” said Greece’s Pierrakakis. “The IMF has made a calculation that the barriers that exist in services or in manufacturing are equivalent to having a 40%-44% tariff for manufacturing.”
Shocks Happen
Even if countries can build a resilient economy, Argentina’s Caputo was skeptical that it would withstand future shocks.
“It looks like these shocks are going to take longer than anyone of us would have anticipated or hoped,” he said. “If that is the case, resilience by definition will have to last longer. And we don’t want to rely that much on that because resilience is there until it is not anymore.”
Caputo also noted that the whole world wouldn’t need to collapse to create a need for resilience. “Just one important country getting into trouble could probably generate systemic risk and affect us all.”
When questioned about France’s current economic distress, Greece’s Pierrakakis responded, “Well, I would say first we’re mindful, but we’re not alert. And we’re not alert in the sense that we know the fundamentals are there and they’re strong. If there’s one key word about Europe, it’s resilience.”
Rob Daly covers the economy and fintech. He can be reached at rdaly@gfmag.com
Fifth Third expects 2.5%-3.5% Q4 net interest income growth as it targets $200M-$300M buybacks (NYSE:FITB)
Management is targeting loan and deposit expansion, notably in Texas and through Innovation Banking, with outlook for growth in net interest income, reduction in noninterest expense, and active pursuit of revenue synergies in wealth and commercial banking.
Gold market consolidating rather than entering bear market, Metals Focus analyst says
Gold market consolidating rather than entering bear market, Metals Focus analyst says
Source link
Bonds have taken control of the markets’ narrative – analyst (SP500:)

Just_Super
The bond market (US10Y), (US30Y), (US2Y) has taken control of the current market narrative, creating ripple effects across non-investment-grade technology companies and neo-cloud providers, according to Tyler Radke, Citi’s co-head of U.S. software research.
In an interview with CNBC, Radke pointed
The S&P 500 had its largest ever put volume day on Friday (SP500:)

primeimages/iStock via Getty Images
The S&P 500 (SP500) recorded its largest-ever single-day put options trading volume by dollar notional value last Friday.
The index reached an estimated $3.3T-$3.4T, according to market data.
The surge represented roughly a 330% increase above the 2024 average, with approximately 4.1M
GFL Environmental deal could happen as early as next week – Bloomberg (GFL:NYSE)

typhoonski/iStock Editorial via Getty Images
A sale of GFL Environmental (GFL) to a consortium of private equity firms could be reached as early as next week.
While the companies are still working on negotiating the terms and structure of a potential deal, a transaction could happen
Central Garden & Pet complements its portfolio with acquisition of 150-year old Burpee
Central Garden & Pet complements its portfolio with acquisition of 150-year old Burpee
Source link
FX weekly: Dollar weakens against major peers (DXY:)
The dollar index (DXY), which measures the greenback against a basket of major currencies, was last up 0.10% at $101.93 and remains up over 3.8% for the year to date.
Dollar weekly moves and key drivers:
Over the past week, the

Standard Bank’s Rajesh Ramsundhar on Africa’s Growth in Payments and Trade

Produced in partnership with Standard Bank, this video features Rajesh Ramsundhar, Head of Investor Services & Financial Institutions, Corporate and Investment Banking at Standard Bank, speaking with Global Finance at Sibos.
Ramsundhar explains why Standard Bank is firmly bullish on Africa’s long-term growth runway; how payments and trade sit as the bank’s core transaction banking priorities; and how its technology agenda — building on the bank’s legacy of innovation, deploying technology to enter new markets, and applying data and AI to sharpen efficiency and client service — is positioning the bank for what comes next.
IN PARTNERSHIP WITH

AIOS Tech to acquire SmartCore Holdings in all-stock deal
- AIOS Tech (AIOS) said on Monday that it will acquire SmartCore Holdings in an all-stock deal worth $100M.
- AIOS Tech will purchase the shares from Better Way Holdings, Novo Spring Management and Cloud Spring, which collectively hold all the issued and
Global-E Online rallies after Morgan Stanley turns bullish (GLBE:NASDAQ)

Morgan Stanley turned bullish on Global-E Online (GLBE) on its view that the durability and magnitude of the DTC e-commerce company’s same-store-sales growth is being underappreciated. The stock was upgraded to Overweight on the expectation for strong sales growth and
East Africa Moves to Create Payments Market
Fast-track settlement is making East African payments easier—and a new strategy emerges.
This article appears in the October 2026 issue of Global Finance Magazine.
East Africa is beginning to transform the national payment systems used by millions of businesses and consumers into infrastructure for a more integrated regional market. Rather than building an entirely new platform, the emerging strategy is to connect existing systems, enabling money to move between countries more quickly and with less friction.
Rwanda and Tanzania are at the forefront of that effort, working to connect Tanzania’s Instant Payment System (TIPS) with Rwanda’s National Payment Switch (RSwitch) to create an instant-payment corridor under the Cross-Border Payment System Masterplan of the East African Community (EAC).
The work is moving beyond policy discussions into the technical, operational, and regulatory arrangements required to make the system function. Its significance, however, extends beyond faster remittances. If national payment systems become interoperable, businesses could pay suppliers, receive payments from customers, and settle commercial transactions across borders more easily than under traditional arrangements.
Small and midsize enterprises, banks, fintech companies, and mobile-money operators could all benefit if regional payments begin to match the speed and convenience of domestic transactions.
This Rwanda-Tanzania initiative offers the most immediate test of the concept, but it is not the only example of East Africa’s emerging payments architecture. Kenya’s Pesalink, the country’s instant-payment network, connected to the Pan-African Payment and Settlement System (PAPSS) in February. The partnership enables instant, round-the-clock payments from PAPSS participants to banks and mobile-money operators on the Pesalink network in Kenya, with transactions settled in local currencies.
Those two developments illustrate different routes toward the same objective. Rwanda and Tanzania are connecting their national instant payment systems directly, while Kenya is linking its domestic infrastructure to a wider continental network. Together, they suggest that African payments integration may depend less on building a single system than on making existing systems work together.
EAC’s Regional Masterplan
A broader regional effort is also moving into implementation. On August 24, the EAC announced the establishment of three technical working groups to support implementation of its Masterplan. The Masterplan is “anchored on four key pillars”: governance and regulation, infrastructure, inclusivity, and capacity building. It includes 20 strategic initiatives to strengthen cross-border payment systems.

MDU Capital
Total trade for members of the EAC in 2025 is reported at $156.6 billion, including $19.3 billion among partner states, underscoring the system’s commercial implications. As goods and services move more freely across the region, the financial infrastructure supporting those transactions will also need to become easier to use.
“East Africa’s push for interoperable payments could fundamentally change the economics of regional trade,” said Robert Omotunde, executive director and chief investment officer of Lagos-based asset management and advisory firm MDU Capital. “The significance goes beyond making cross-border transactions faster or cheaper; it is about creating the financial infrastructure through which African businesses can trade more seamlessly across borders.”
As the African Continental Free Trade Area expands markets for cross-border businesses and increases demand for payment systems that support that commerce, opportunities could eventually extend beyond the EAC. Faster settlement, lower transaction costs, and greater use of local currencies could reduce some of the financial friction that still accompanies regional trade. While East Africa is beginning to connect payment systems already embedded in its banks, mobile-money networks, and the wider financial system, the region faces the challenge of ensuring those connections operate reliably across different regulatory and monetary environments.
Vincent Nwanma is a contributing writer based in Nigeria.