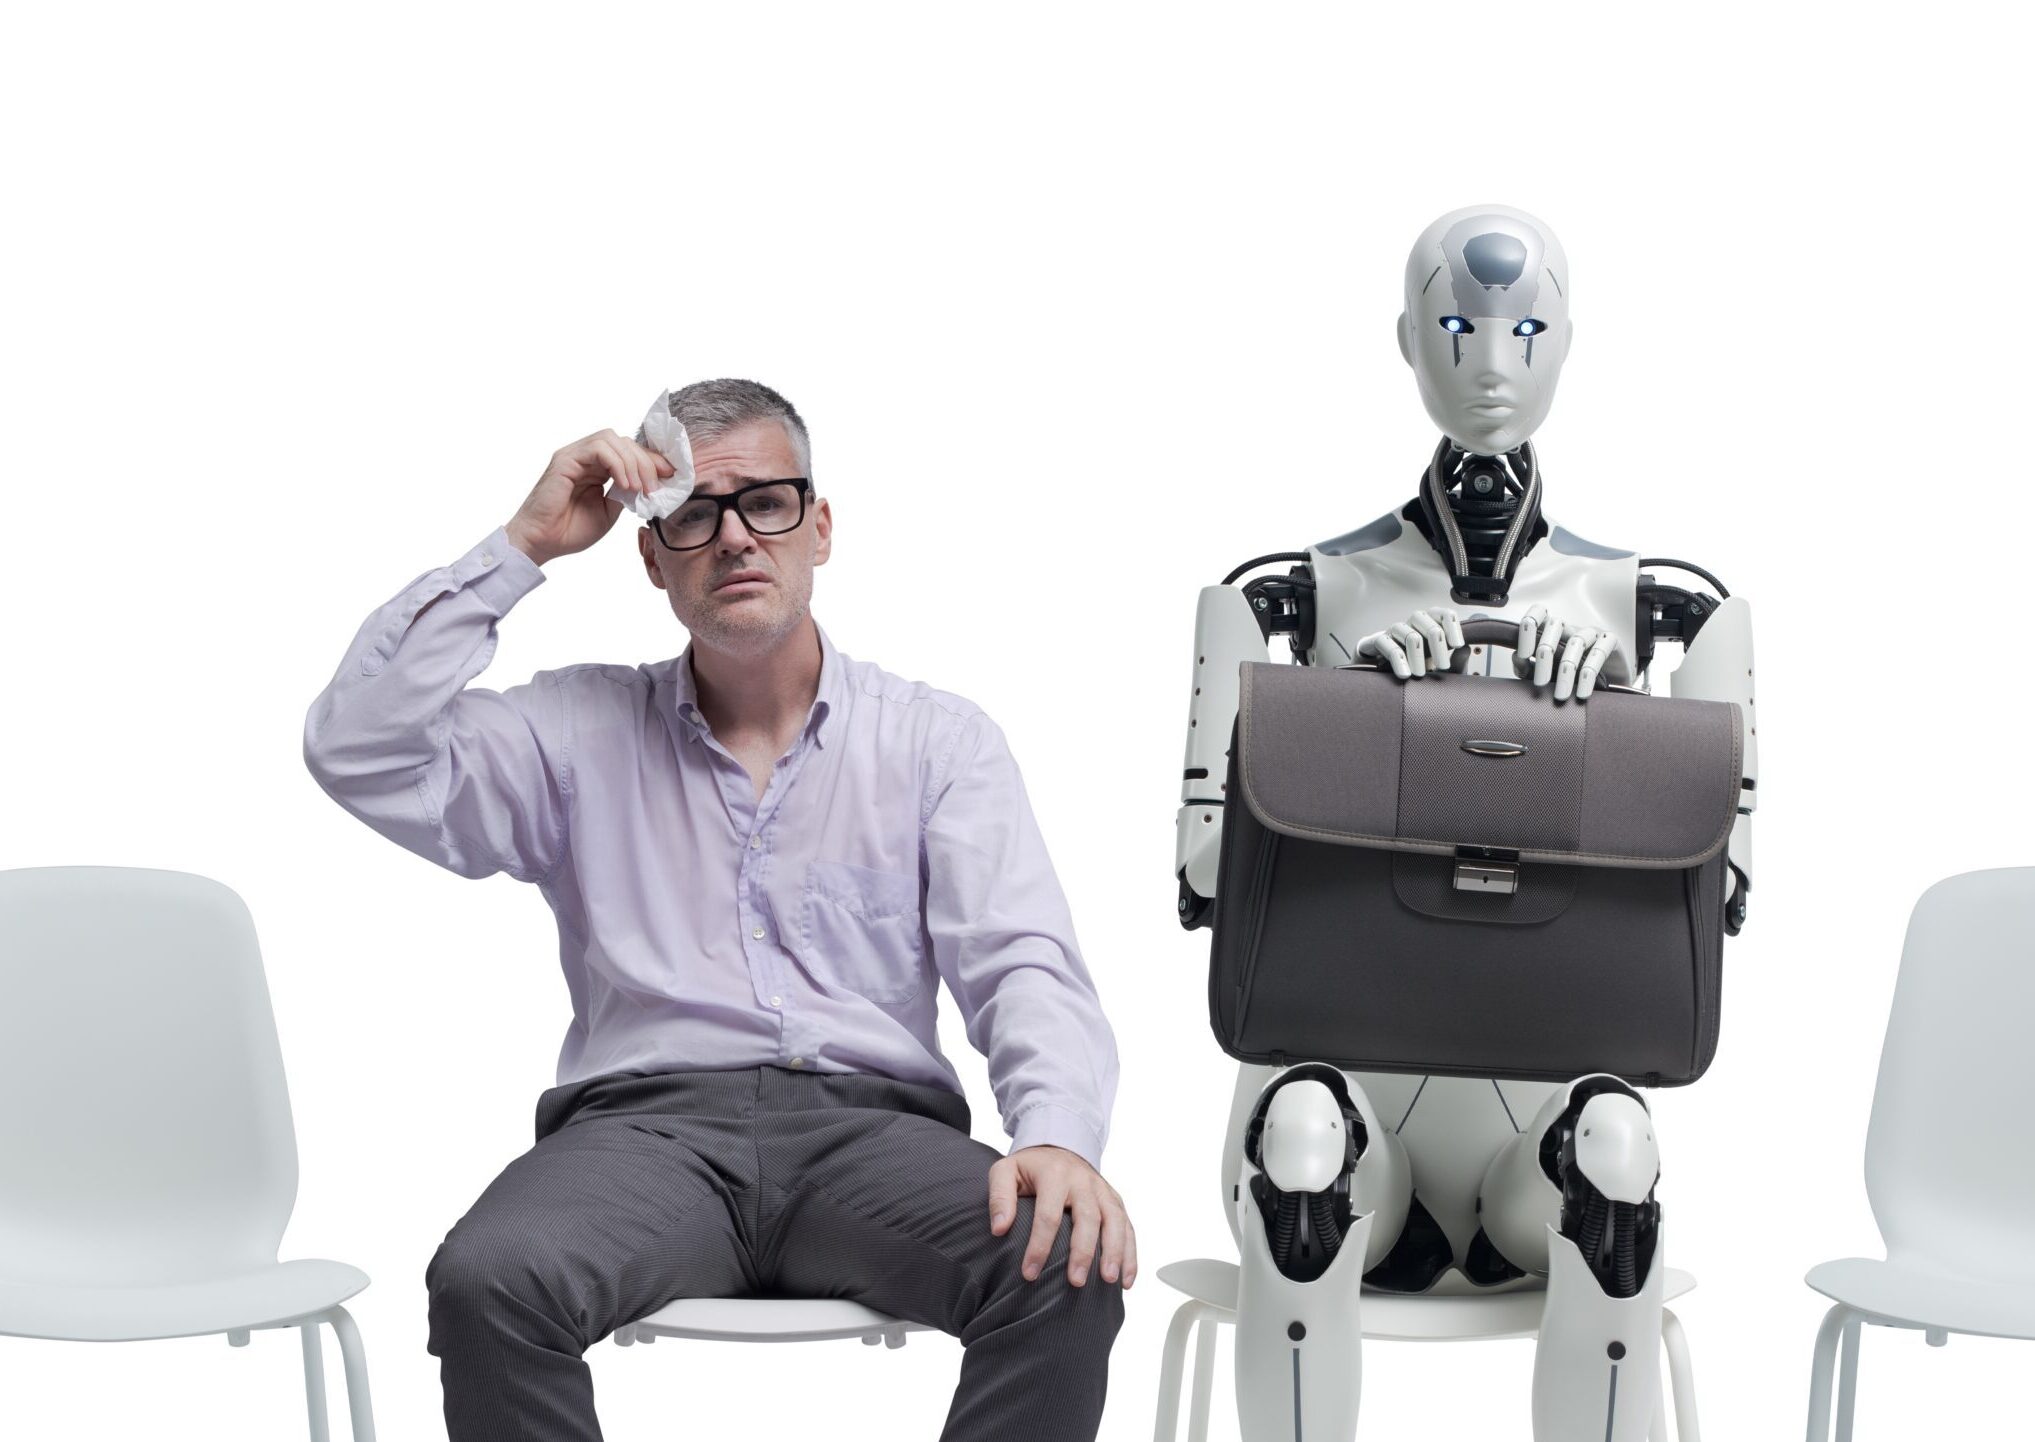
“They have been through a lot over the past six or seven years,” said Bhushan Sethi, a partner at PwC, who moderated a Sibos panel on AI-led workforce strategy. “We’ve gone from the Great Recession to quiet quitting. We’re now in the ‘no hire, no fire’ job market in the US and beyond.”
Through it all, companies continue to ask their employees to move faster, reimagine their businesses end-to-end, and standardize their documented processes globally, while their leadership eyes the performance of small AI-enabled startups unencumbered by technology debt, he added. “That’s a challenge.”
Especially when 80% of those polled expect their organization to reduce headcount by 20% in the next few years.
“We don’t have a choice of going back and saying ‘No, we are not going to move with the industry and trends that are leading the next generation of the financial services industry,’” said Anna Domino, global head of client services at BNY.
“BNY has more than 300 AI-enabled offerings currently in production,” she added. “We also have almost 150 digital employees deployed across the organization, including operations and other functions. Over half our employee population are AI super-users on a daily basis.”
In comparison, only 22% of respondents in PwC’s survey reported using generative AI daily for their jobs, up 8% from the previous year.
Calming the AI Workforce
Allaying a workforce’s anxiety about AI won’t be easy, as 44% of respondents in a PwC survey said they did not trust their senior management.
“That’s a hard environment to bring your best self to work and to optimize and leverage the investments that many, many firms have made and will continue to make in AI-led transformation,” said PwC’s Sethi.
Applying human skills such as empathy and kindness would help leadership manage its workforce’s anxiety, he added. “Let’s face it, we could all do with a little more of that.”
When BNY deploys a new solution, Domino’s team works with the people who currently do the job and lets them lead the bank’s redesign of the process to create more value for the client.
“If you include people in the conversation and give them transparency about how their role will change because of the redesign and what skills they need to learn over time to support the new process, it makes buy-in much easier,” she said.
Another option for employers is to wait a few years and hire those born around 2010, who won’t remember a world without AI.
“We have people in their 20s, mid-20s, and late 20s who are digital natives, but [employers] want those people who came out of their cribs and started playing on tablets and iPhones,” said panelist Darmesh Sethi, a managing director at Sumitomo Mitsui Banking Corp. (SMBC), sharing his personal opinion.
They will enter entry-level jobs after working on their high school newspapers and using AI throughout college, he added. “They are comfortable; they’re confident, and that is what we need. We need a confident workforce that can actually harness the power and potential of what these technologies provide.”
However, the same technologies are eliminating the menial work that once taught entry-level employees the business.
“When we were hiring people out of college 20 years ago, they would be creating spreadsheets and PowerPoint presentations,” said BNY’s Domino. “None of that is happening anymore. So, we have to focus on apprenticeships, coaching, shadowing, and bringing that talent in front of clients way sooner than it used to happen 20 or 30 years ago.”
The process would require an investment of time and energy from senior leaders who possess the business knowledge, she added.
SMBC’s Sethi sees entry-level employees moving from grunt work to decision-making. “That is where they are going to have to step up,” he said. “And that is what we are really seeing in our employee training and the intentional hiring of young talent.”
Capricor Therapeutics (CAPR) is down ~10% in Monday trading despite releasing positive data from an open-label extension study for deramiocel for Duchenne muscular dystrophy as investors appear hesitant that the candidate will muster US FDA approval.
Marcelo Mousalli, Head of Product for Latin America at Bank of America, speaks with Global Finance editor Paul Curcio at the 2026 Global Finance Transaction Banking Awards, Fontainebleau, Miami Beach.
At the 2026 Global Finance Transaction Banking Awards in Miami Beach, editor Paul Curcio sat down with Marcelo Mousalli, Head of Product for Latin America at Bank of America, which took the Best Bank for Transaction Banking global award this year. Mousalli explains how a client-first model, built around regional cash flow advisory boards, drives the bank’s product development. He also details how BofA pairs the scale of its global platform with local expertise to lead in liquidity, payments and cross-border real-time settlement.
Major executive moves and leadership changes across the finance industry.
This article appears in the September 2026 issue of Global Finance Magazine.
Michael Kremer, World Bank
The World Bank Group appointedMichael Kremer to be the organization’s chief economist and senior vice president for development economics.
Most recently, he served as director of the University of Chicago’s Development Innovation Lab, where he researched economic growth, technological change, and development economics. Kermer, Abhijit Banerjee, and Esther Duflo jointly won the Nobel Prize in Economics in 2019 for their “experimental approach to alleviating global poverty.
Kremer “has spent his career not just identifying what works in development but proving it at scale,” said Ajay Banga, President of the World Bank Group. “That is exactly the kind of thinking we need.” —Rob Daly
Pam Kaur, HSBC
After more than a decade at HSBC, Pam Kaur will step down as Group CFO, a position she has held since January 2025, before the bank’s 2027 annual meeting.
She will assume an advisory role to support Group CEO Georges Elherdy and ensure a smooth transition for her successor.
Kaur began her career in 2013 as group head of internal audit before advancing to the head of wholesale market and credit risk, group chief risk officer, group chief risk and compliance officer, and eventually group CFO.
Brendan Nelson, HSBC Group Holding plc chairman, praised Kaur for her “strong judgment and integrity.” She will leave the Group CFO role with the firm’s “deepest thanks and best wishes,” he added. —Rob Daly
Nelle Miller, J.P. Morgan
J.P. Morgan namedNelle Miller and William Sinclair as co-CEOs of its U.S. Private Bank in September.
The pair leads the firm’s $2.4 trillion U.S. private banking business, overseeing more than 5,500 professionals across 57 offices who serve the wealthiest individuals, family offices, and institutions nationwide.
The appointments follow the July 2025 naming of David Frame as global CEO of J.P. Morgan Private Bank. Miller and Sinclair joined in 2002 and 2007, respectively. Miller currently heads the firm’s New York market, while Sinclair leads the Financial Leaders Group.
“We have a fantastic franchise, with exceptional people and an unparalleled breadth of capabilities,” Sinclair said. —Anthony Noto
Jules Wurlod, IA Global
IA Global Capital, a technology-focused investment bank with offices in New York and London, announced that Jules Wurlod has joined the firm as managing director.
Wurlod has served as M&A director for circular businesses at Houlihan Lokey since 2020, focusing on circular technology services such as device-as-a-service, IT asset management, IT asset disposition, recommerce, and trade-in. He previously worked as a project leader at Boston Consulting Group, advising Fortune 500 companies and government officials across Europe and the Middle East on corporate strategy and sustainability. —Anthony Noto
Nvidia (NVDA)-backed AI infrastructure startup Firmus Technologies plans to allocate about half of its $5.5 billion ($7.9 billion) initial public offering to a handful of existing backers, according to a book update sent on Monday morning, AFR reported.
The first full week of October, though light, brings a diverse earnings slate spanning consumer staples, beverages, travel, apparel, and AI infrastructure, with companies offering fresh reads on both consumer demand and the capital-intensive technology buildout. PepsiCo (PEP), Constellation
Middle East crude oil exports have rebounded to 17.5M bbl/day on a 10-day average, or 98% of pre-war levels, despite continued risks to shipping, J.P. Morgan analysts said this week, supported by restored flows through Saudi Arabia’s East-West pipeline and
When Maduro was taken and arrested on January 3rd, many Venezuelans brought out the good stuff. The old bottle of rum or whiskey they’d been saving for a special occasion, believing the incursion would inevitably lead to the return of liberty in Venezuela. Nine months later, the “transition” has not been what most Venezuelans wanted. Hundreds of political prisoners were released, but that is not enough. A few laws are being reformed, but not the institutions that carry them out. Delcy remains in power despite no lawful statute allowing it nor any sort of popular mandate for her to be the head of the Venezuelan State.
Many who brought out the good whiskey have soured on the transition, or at the very least lost their shiny optimism. But the mistake was not just to believe in a future that now seems a bit naive, but to yearn for the return of a past which was the precursor to our current tragic state.
The quest for a more liberal society
Yes, we were better off before the 2000s, but we’ve never had a truly free society without clientelism or corruption. Chavismo may have perfected the art of corruption in Venezuela, but they certainly did not invent it. Venezuela, since its inception, has not been able to ameliorate the very Latin American issue of inequalities of power. We tend to forget about the problem during oil bonanzas. Everyone is doing better, right? Why worry? Then the oil price inevitably falls, the party stops, the lights turn on and we see the naked truth that we are in a horrible state of disrepair.
Many say that the Venezuelan problem is economic (lack of diversification or investment in non-oil industries), political (once high polarization and weak rule of law), or even cultural (a tendency towards el guiso). But within these lies a deeper philosophical issue: for a society that claims to love liberty and our libertadores as much as we do, we don’t actually understand what it takes to create a liberal society.
This is hardly a Venezuela-specific issue, but we are a unique case in that so much of our self-perception is based on the idea of a people who achieved freedom from the yoke of Spanish tyranny, only to then continue to liberate other countries in South America, making Simón Bolívar the most famous person in the history of the continent.
What room is there to become “more liberal” once all citizens are recognized by the law and there is universal suffrage?
To understand what it means to be a liberal society, perhaps it would be best to understand what it means to be a more liberal society. When the classical liberal revolutions of the 18th and 19th centuries took place, it was the divine right of kings that fell. The power was taken from an individual and shared amongst parliaments, which were at the time controlled almost exclusively by rich landowners (including our own first few republics). Still, this was unquestionably a redistribution of power from the individual to the few. It took a long time, but eventually this distribution of power from the one to the few became a distribution of power from the few to the many. Nowadays, democratic societies are expected to allow every single citizen to vote, but this is a reality that is younger than the oldest person alive today. When English supercentenarian Ethel Caterham in the UK was born in 1909, her mother would not have been allowed to vote.
Liberal societies today hardly even question the idea that all people should be equal in respect to the law and that we ought to have a voice in the decisions of our country through voting. So what room is there to become “more liberal” once all citizens are recognized by the law and there is universal suffrage?
It’s true that the distribution of power in liberal countries these days is much improved when compared to 100 years ago, but is it better than 50 years ago? The laws may say that all people are equal, but systems don’t seem to provide that result. Even in societies where they have nominally distributed power amongst all citizens, the power has not been really distributed amongst them nearly as well. Throughout the current Trump presidency, there have been a string of pardons for white-collar criminals who have paid patronage to Trump and his family, including the former president of Honduras convicted of drug trafficking, or a Venezuelan oligarch indicted for allegedly bribing a Puerto Rico governor.
This is a clear example of a two-tiered justice system in which if you put the right money in the right pockets, you get preferential treatment.
A post-WW2 recipe?
I use these examples to show that although there is nothing ontologically wrong with wealth inequality, especially if the rich earned that money honestly, in practice inequality in resources leads to inequality in power and inevitably abuse of that power. This is the state of Venezuela now, but it was also the state of Venezuela long before Chávez caught a whiff of power and what ultimately led a majority of voters to choose a murderer and traitor over the “democracy” that was in place.
The issue, after nearly three decades of chavismo, is that although they entered power on the basis of railing against resource and power inequalities, in the time since they’ve been in charge they’ve done nothing to ameliorate those same inequalities. The people in government have simply taken the seats of the previously corrupt politicians and become even more clientelist, leading to greater inequalities in power and resources than ever before (on top of just a generally poorer country).
The vast majority of Venezuelans can clearly see what chavismo is now, even many who used to vote for it. And though we are still not through with it, we ought to give serious consideration to what we want to replace it with. Do we want a return to bipartidismo and clientelism with high inequality? Just hoping that the price of oil rises so we can keep our population happy whilst oligarchs accrue more and more power? Or do we actually want to achieve the liberty we say we value so much?
We can imitate post-WWII States who decreased inequalities by taxing the incomes of extremely wealthy people at extremely high rates whilst maintaining a belief in free markets, property and the rule of law.
When we get rid of chavismo, we will have an even greater challenge ahead. We’ll have the challenge of rebuilding a country destroyed by decades of mismanagement, a country filled with people who have gotten their wealth by enchufándose into a corrupt system that has oppressed the voice of its people. And we’ll have to decide how we want to go about bringing back liberty. I suggest we act like the previous liberal revolutions we venerate, and distribute more power from the few to the many.
So what is the solution to power inequalities and resource inequalities?
Thankfully, there is no need to reinvent the wheel. We can copy the policies of post-WWII countries (US, Japan, France, UK, Germany, etc) who decreased inequalities in their countries by taxing the incomes of extremely wealthy people at extremely high rates whilst maintaining a belief in free markets, property and the rule of law. This has the added benefit of diversifying government incomes away from just oil revenue or sales taxes, which are regressive and hurt consumers and small businesses (I could go on and on about the economic benefits, but I’ll stick to the institutional ones here). I specify the post-WWII liberal societies here and not the communist ones, because although communist countries seek to ameliorate resource inequalities they end up increasing power inequalities which lead to just as much abuse, if not even more than hyper-capitalistic oligarchic societies.
But before we can consider which policies we ought to copy from which societies, we must adopt the attitudes and political beliefs which made those policies implementable in the first place.
The world, not just Venezuela, is at a crossroads between greater authoritarianism or greater liberalism. If we are leaders of liberalism in our continent, as we have historically perceived ourselves to be, then we ought to understand the nature of liberalism and how we ought to achieve it. If we do not have a vision of how to recreate our institutions and our general idea of what a liberal society even is, then we will surely return to the sad state we are in right now, even after we get rid of the kleptocrats sitting in Miraflores.
The solution is simple, but it’s not easy. Entrenched interests are just that; entrenched. But if the people of the country yearn for liberty and we manage to understand what it takes to attain it, then it can be done through hard work and dedication, as ultimately all worthwhile goals are achieved.
Downward revisions and finance and insurance job losses paint a pessimistic picture for the U.S. labor market.
In the last jobs numbers report before a contentious U.S. mid-term election, the Bureau of Labor Statistics (BLS) reported that seasonally adjusted nonfarm payrolls added 29,000 jobs in September, while the unemployment rate remained stable at 4.2%
The BLS also revised its July numbers for a second time, now showing a loss of 10,000 jobs compared to its first revision, which upped the number of jobs created to 21,000 from a loss of 23,000 jobs. It also revised August’s number down to 132,000 from 162,000.
The report may have underwhelmed market expectations, but economists at RBC say that doesn’t mean the labor market is weak.
“The 29,000 payroll gain is quite healthy in the context of our breakeven estimate of 20,000 jobs per month,” they wrote in an RBC Economics note. Gains were broad-based, and the declines more likely reflect retirements than layoffs, especially in sectors with an older workforce (e.g., the median worker age in financial services is 44.2 years compared to 42.1 years overall). Despite a slowdown in health care hiring, strength was driven by the goods sector, which continued to recover from the post–Liberation Day layoffs earlier in 2025.”
Finance Sector Feels the Bite
Despite the overall positive number, the finance and insurance sector lost 7,000 jobs, with credit intermediation and related activities accounting for 4,600 fewer jobs, followed by insurance carrier and related activities, which lost 2,300 positions.
Employment in the capital markets remained unchanged, with no job gains or losses compared to August.
The information industry took a harder hit than the finance and insurance sector, losing 10,000 jobs. Publishing lost 4,000 jobs, while broadcast and content providers lost 3,000 jobs, and computing infrastructure providers, data processing, and web hosting and related services eliminated 1,600 jobs.
Private Optimism
Using a proprietary methodology developed with the Stanford Digital Economy Lab, ADP is far sunnier in its view, estimating that U.S. private employers added 90,000 jobs over the same period, according to its ADP National Employment Report for September.
“It’s a strong report. After a three-month slowdown, job creation rebounded, and pay growth remained solid,” said Nela Richardson, chief economist at ADP, in a prepared statement.
However, the report’s authors have no good news for those working in financial activities, which lost the most jobs (-16,000) of any sector, while professional and business services lost the second-largest amount (-11,000).
The information sector managed to eke out growth, adding 3,000 new positions.
Mid-sized companies (50 to 499 employees) created more than half of the new jobs (54,000). Small companies (1 to 49 employees) added 23,000 new positions, while large companies (more than 500 employees) added the fewest jobs (14,000).
However, not everyone shares the optimism.
The BLS report reflects an economy that has not set itself up for growth, Michele Evermore, a senior fellow at the National Employment Law Project, told Global Finance.
“Nobody was planning to build a manufacturing economy in the United States again,” she said. “Growth was going to come from innovation. If we get rid of the core government research, that is what was going to build jobs of the future, I’m afraid this is par for the course for the foreseeable future until either the AI bubble crashes or AI turns out to be amazing and starts taking over jobs.”
Rob Daly covers fintech and the economy. Contact him at rdaly@gfmag.com.
The amendment aims to clarify campaign finance rules for candidates running for a seat on the board of education, which overseas LAUSD and its approximately 350,000 students.
Repetitive language in the Los Angeles City Charter would be deleted and would make clear the same campaign finance rules apply to both mayoral candidates and board of education candidates, except in certain instances, the measure says.
Among those requirements are rules governing campaign contribution limits, filing deadlines, public disclosures and fundraising windows.
Eurozone annual inflation accelerated to 3.8% in September, up from 3.2% in August and above market expectations of 3.6%, according to preliminary estimates.
Core inflation, which excludes energy and food, rose to 2.5% from 2.4%, in line with expectations.
Hong Kong listing reforms and surging deposits show regional markets funding Asia’s future.
This article appears in the October issue of Global Finance Magazine.
When the International Monetary Fund and World Bank convene their annual meetings in Bangkok this October, it will be the first time the joint gathering has returned to the city in 35 years. IMF officials have taken to calling Asia the “driving force” of the global economy — shorthand for a region that accounts for one-third of global gross domestic product, 29% of global public equity market capitalization, 56% of listed companies and 52% of global venture capital activity, according to the Organization for Economic Cooperation and Development’s Asia Capital Markets Report
The question for chief financial officers isn’t whether Asia is growing — it’s whether the region can finance that growth on its own terms, or whether it still depends on capital, listings, and liquidity from the West. The answer, based on bank data, exchange records, and conversations with practitioners and economists on the ground, turns out to be both.
Alex Ibrahim, until recently corporate CFO of Yanolja, the Seoul-headquartered travel technology company, said Asia is a picture of change. Its financial sector has matured in the decades since the 1960s to 1990s, when headlines proclaimed the rise of the Asian Tigers and countries became synonymous with rapid, export-driven industrialization funded largely from abroad.
“Back then, the economies were growing very fast, and a lot of the money was coming from the U.S. to invest,” said Ibrahim, who before joining Yanolja spent nearly a decade running international capital markets at the New York Stock Exchange. “If you look now, capital has developed locally and the financial infrastructure in Asia is much more robust.”
Marc Iyeki, a board advisor who formerly led the NYSE’s Asia-Pacific listing sector and shepherded about 100 companies to market, said the shift reflects a change in decision-making. “Decades ago, the money was in New York. Decisions were made in New York,” he said. Since then, regional private equity and venture firms have placed people on the ground in Asia who understand the home market and make the calls themselves, often after training at global firms and bringing that experience back. The region has also produced homegrown standouts such as PAG, Hillhouse Investment, MBK Partners, and Peak XV Partners.
That evolution is seen in how Asia’s own exchanges are performing. Over the past ten years, Hong Kong’s equity market has moved through cycles in liquidity and new issuance, but 2025 marked a rebound from the post-pandemic slowdown. Average daily turnover on the Hong Kong stock exchange rose from HK$66 billion in 2016 to HK$248 billion in 2025, nearly 3.7 times the level a decade earlier. Initial public offering proceeds were more volatile: HK$194 billion was raised in 2016, followed by several weak years before rebounding to HK$285 billion in 2025.
Japan’s exchange has risen more steadily. On the Tokyo Stock Exchange’s Prime Market, average daily trading value for domestic common stocks rose from 3.2 trillion yen in fiscal year 2022 to 4.3 trillion yen in fiscal year 2023, and 6.7 trillion yen in fiscal year 2025.
Iyeki recalled that when Alibaba first wanted to list in Hong Kong in 2013, the exchange turned it away over governance requirements — and New York landed the IPO. Losing a flagship company forced a reckoning. Some in Hong Kong worried that loosening listing rules would weaken protections for retail investors; others warned the market would be “hollowed out,” as local companies sought listings in New York and London. Hong Kong changed its rules, and years later Alibaba came back for a dual listing. The infrastructure now absorbing record IPO volumes and Alibaba-scale capital was built, in part, out of that earlier loss.
One of the people behind that financial infrastructure is Larry Li, a Hong Kong-based fintech founder who worked on Stock Connect, a market access program that links the stock markets of mainland China and Hong Kong. It has become a major cross-border equity trading tie between China and international investors. Its northbound turnover more than doubled to 345 billion yuan in the first half of 2026; southbound turnover hit a new high of $123 billion yuan. “It’s a closed loop, so capital cannot fly out of the system,” Li said.
Li, a director of Digital Asset Clearing Center, which aims to develop a financial settlement and clearing infrastructure that can integrate digital and tokenized assets into mainstream capital markets, argued that areas like Hong Kong, Singapore, and Shanghai have pockets of innovation in financial AI. Li said the region’s token economy “drives market infrastructure upgrades, attracts capital globally, and enjoys support from governments as a strategic force of growth.”
Fintech, Banking, and Innovation
Li pointed out that the region’s tokenized economy fosters “co-opetition” between the banking industry and fintech enterprises. Consumers across the region have largely turned to fintech-developed super apps like Alipay and WeChat Pay, while banks have doubled down on the regulated back end: cross-border settlement, know your customer, and other compliance rules.
Some of the same banks figuring out Asia’s patchwork of KYC and settlement rules are also among the world’s fastest-growing lenders. Banking data makes the same point in numbers. S&P Global Market Intelligence’s 2026 ranking of Asia-Pacific’s 50 largest lenders by assets found China’s big four — Industrial and Commercial Bank of China, Agricultural Bank of China, China Construction Bank, and Bank of China — grew assets about 16% year over year in US-dollar terms as of December 31, 2025. S&P also singled out Singapore’s three largest banks — DBS, Oversea-Chinese Banking Corp., and United Overseas Bank — for strong double-digit asset growth, driven by regional deposit inflows rather than capital raised abroad.
China’s financial system is bank-led and primarily state-directed, according to Standard & Poor’s. The country’s household savings, pensions, and corporate liquidity flow into banks rather than capital markets, giving lenders a large, stable funding base that the government then channels toward priority sectors. Beijing has supported that base with a 520 billion yuan capital injection into four state-owned banks in 2025, followed by plans announced in March 2026 to issue another 300 billion yuan in special bonds to recapitalize ICBC and Agricultural Bank of China.
“As the primary liquidity conduit for fiscal stimulus, state-owned banks increased their financial investments by 19% in 2025,” Iris Tan, a senior equity analyst at Morningstar, said in the S&P report. These financial investments were “fueled by a record 28% surge in government bond issuance,” according to Tan.
Vietnam as a Case Study
None of this means that Asia’s approximately 48 countries are growing equally. Sam Van, managing partner of SRO Partners and an advisor on Vietnamese capital markets, said the region is still layered by tier. Blue-chip regional companies can borrow cheaply from local banks at rates set by well-capitalized central banks — sometimes so cheaply, he said, that “it’s better to borrow money from the bank than actually issue a bond.” Midsize companies, those earning under $50 million in revenue, are a harder sell to credit officers weighing thin margins against career risk, which pushes some smaller businesses toward informal lenders. Van sees this gap as a reality in a still-maturing system rather than evidence that the system isn’t working.
Van, who recently co-authored a book that chronicles Vietnam’s economic rise, said the country illustrates how quickly a market can mature once the incentives align. Vietnam’s IMF-linked compliance upgrades — the product of what Van calls the government “consistently wanting to meet that standard” since joining the IMF in the 1990s — helped it earn an upgrade to FTSE Russell’s emerging-market status in September.
Critical Economic Views
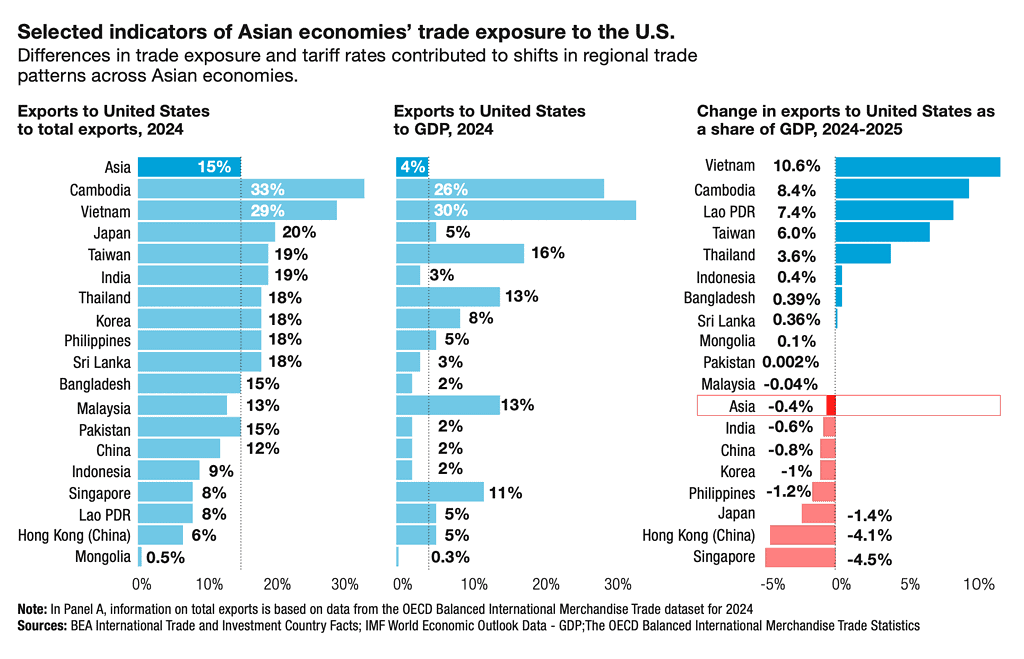
Two economists watching from outside the deal room caution against overstating the region’s financial self-sufficiency. Bala Ramasamy, professor of economics at the China Europe International Business School in Shanghai, argued that “the driver in Asia, for Asia and by Asia is definitely China” — its outbound foreign direct investment to the Association of Southeast Asian Nations alone can match what comes from the EU or the US, and the reconfiguration of trade around geopolitical frictions is relocating supply chains in ways that are boosting growth across Southeast and South Asia. Japanese and Taiwanese capital, he noted, is increasingly heading toward the US to secure market access and stay aligned with Trump-era industrial policy, even as flows from Europe and the US slow elsewhere. “I don’t think Asia can do without it,” he said.
Prema-chandra Athukorala, emeritus professor of economics at the Australian National University, said Asia’s growth is substantial, but its export-driven economy still relies heavily on the rest of the world. Domestic savings rates across the region dwarf the emerging-market average of roughly 25% — Singapore’s is near 58%, China’s near 49.5%, India’s around 30% — and in most Asian economies, investment rates run below those savings rates, meaning the region is, on balance, a net exporter of capital rather than an importer of it. Intraregional FDI from China, Korea, Taiwan, and Singapore has grown substantially over the past two decades. However, Athukorala said that extra-regional FDI still accounts for the larger share of investment in Vietnam, Malaysia, Thailand, and Cambodia, where Western multinationals remain central to “China+1” supply-chain strategies, and even domestically financed activity depends heavily on global demand. “Over two-thirds of the regional exports are still destined to extra-regional markets,” he said.
Taken together, the practitioners and the professors describe a region that finances far more of its own growth than it used to, yet remains clearly reliant on the rest of the world.
Weld Royal is a contributing writer based in the U.S.
Algoma Steel (ASTL) fell 2.4% post-market Thursday after warning it expects to report a sharp decline in Q3 steel shipments due to the impact on production caused by a turbine outage.
The Canadian steel producer guided for Q3 steel shipments of ~145K