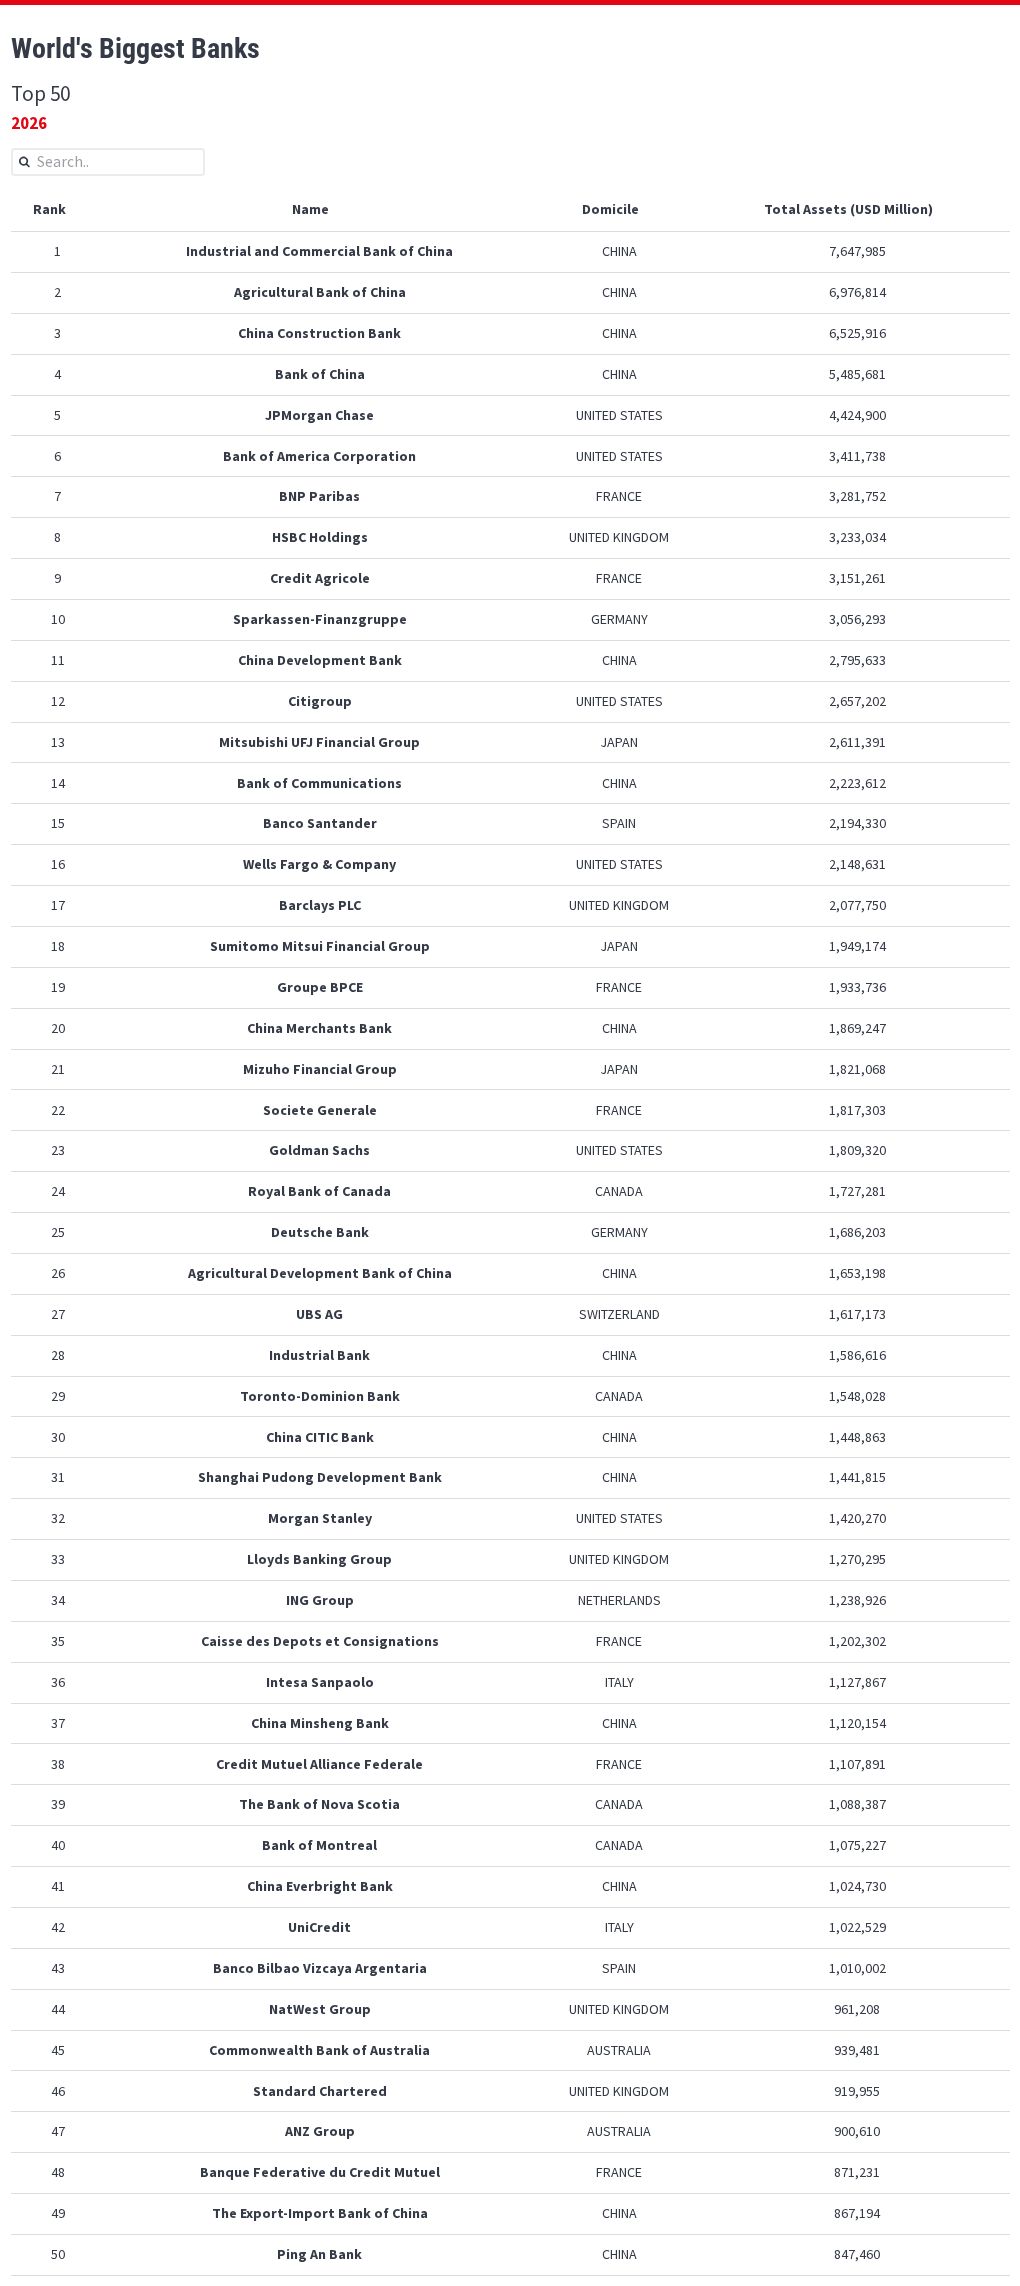
Biggest Banks 2026: assets of the world’s top 50 banks rose 13% to $108 trillion, led by China’s state-owned banks, with Western Europe placing 20 banks.
Balance sheets of global banks continued to expand in 2025 as central banks across many major economies became more accommodative, with lower rates supporting economic activity and healthy equity markets sustaining investment.
Overall, the assets of the top 50 global banks increased 13% year over year to reach $108 trillion as of December 2025. This growth was reflected among the Chinese banks in our rankings, which reported over $43 trillion in aggregate as policy-driven balance-sheet expansion offset weakness in overall loan growth. The country’s large state-owned banks top the rankings, and 15 banks are included, unchanged from last year. The Asia-Pacific region accounts for 18 institutions when Mitsubishi UFJ, Sumitomo Mitsui, and Mizuho are added. Western Europe places the most banks on the list with 20, up from 19 last year, following the addition of Banque Federative du Credit Mutuel at No. 48. BNP Paribas edged out HSBC for the largest bank on the continent.
JPMorgan Chase tops North American banks as U.S. banks’ assets grew 11% year over year. The four Canadian banks each now exceed $1 trillion in assets, driven by 9% average annual growth.
With the addition of Banque Fédérative du Crédit Mutuel, State Bank of India was pushed off this year’s rankings. The asset cutoff for inclusion at $847 billion rose 9% in 2025.
Ecopetrol (EC) is negotiating a 10-year agreement to buy natural gas from Venezuela at a price that would be “very competitive” and “well below” current market levels, CEO Joaquin Gutierrez said Friday during the company’s earnings conference call, according to Bloomberg.
Semiconductor stocks staged their strongest five-day rally since 2020, a sharp rebound after a five-day slide of roughly 20%, according to a chart from The Daily Shot shared by Mike Zaccardi.
The Philadelphia Semiconductor Index (SOX) moved above the
Within emerging-market economies, ongoing uncertainty over U.S. tariff policy continues to reshape global trade flows. However, the impact varies significantly across regions and by export mix.
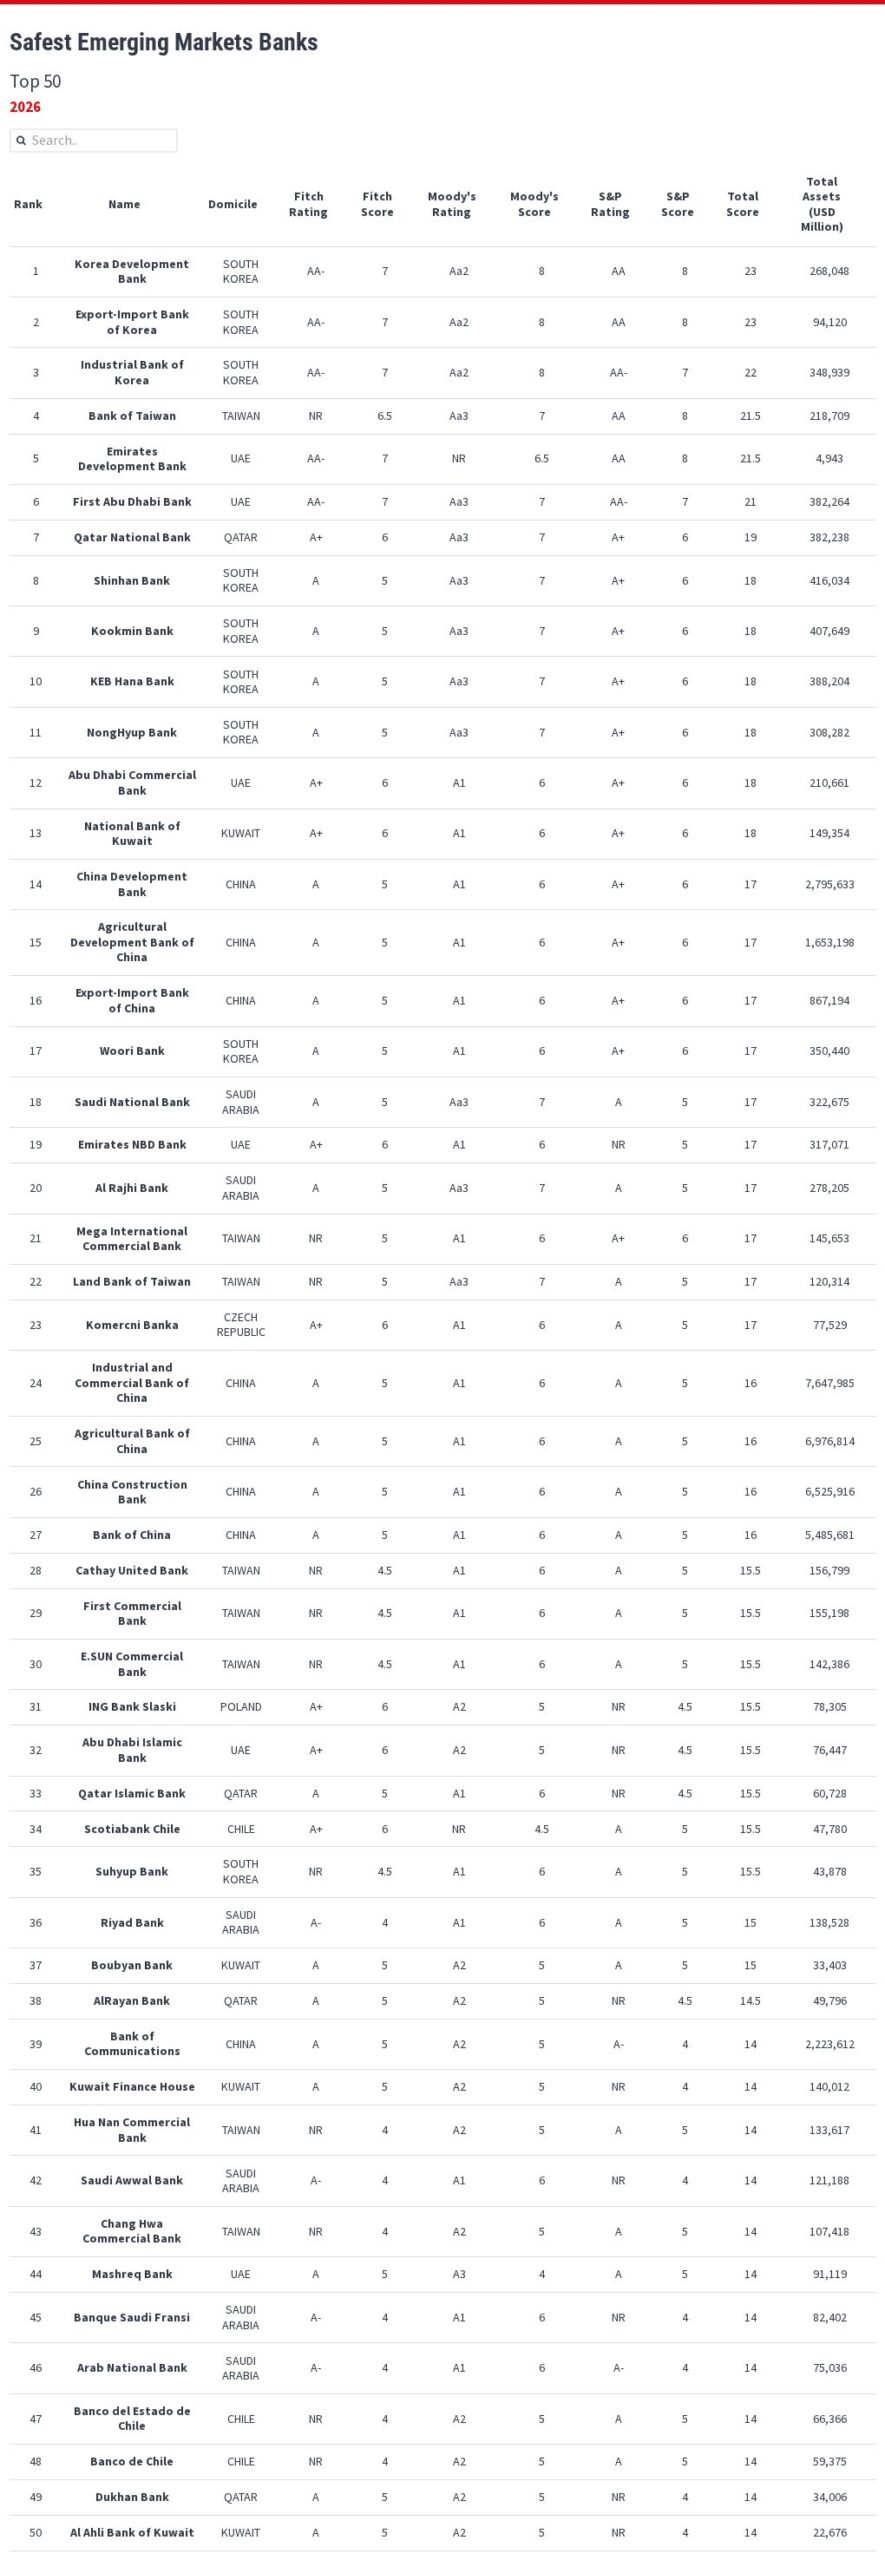
For the institutions included in our Safest Emerging Markets Banks, this environment presents both risks and opportunities. Trade volatility can weigh on corporate clients and credit demand, but it also increases the need for specialized trade and supply-chain financing, treasury, and foreign exchange services. Some emerging-market economies are benefiting as U.S. importers shift sourcing away from more heavily-tariffed countries. According to IMF research, trade diversion and import reallocation toward lower-cost alternatives can help mitigate tariff exposure by changing suppliers, relocating production, and rerouting trade. While these measures can help preserve trade activity, they can also introduce higher costs, operational inefficiencies, and greater supply-chain complexity.
Additionally, tariff impacts vary by region and product. In the Asia-Pacific region, U.S. tariffs are estimated at 21% on China and between 2% and 11% on other Asia-Pacific economies.
South Korea and Taiwan remain highly exposed because they depend heavily on technology exports. However, exceptionally strong demand for semiconductors and AI-related components has so far more than offset much of the tariff-related drag on exports. In South Korea, overall exports rose 84% year over year to a record $121 billion as of September, while semiconductor exports surged 263% to $60.3 billion, according to government data.
Over the same period, Taiwan also reported significant export growth, rising 61% to a record $87 billion, driven by global demand for advanced AI chips and technology products. For the South Korean and Taiwanese banks included in our ranking, this export strength supports corporate activity across the technology, manufacturing, and capital investment sectors, even as tariff-related uncertainty persists. More broadly, emergingmarket economies are contending with heightened inflation pressures from the energy shock associated with the ongoing war with Iran, which contributes to volatility and uncertainty for both consumer and commercial banking clients.
Among the winners for Safest Emerging Markets Banks, changes in sovereign ratings and bank regulatory developments in certain jurisdictions drove shifts in our rankings. In November 2025, S&P upgraded Kuwait to AA- from A+, reflecting the government’s progress with implementing fiscal and economic reforms under Kuwait Vision 2035, the country’s national development strategy. The agency also upgraded National Bank of Kuwait to A+ from A, reflecting its strong franchise in its home country with a 30% market share and its success in geographic diversification, as approximately 25% of revenue is from international sources. Consequently, the bank rose five places to No. 13.
In Saudi Arabia, Fitch raised the ratings of Saudi National Bank and Al Rajhi Bank to A from A- in December 2025. For both banks, Fitch emphasized their strong business profiles and credit metrics, while also increasing their government support ratings component. This move boosted Saudi National Bank up seven places to No. 18, and Al Rajhi moved up six spots to No. 20.
In May, Fitch upgraded Komercni Banka of the Czech Republic to A+ from A. The agency revised its global bank rating methodology to give greater ratings credit to loss-absorbing debt buffers in jurisdictions with developed bank-resolution regimes. As a majority-owned subsidiary of Société Générale, Komercni Banka benefits from the group’s large resolution debt buffer. The bank’s ranking climbed four places to No. 23. In Qatar, AlRayan Bank benefited from Fitch initiating coverage with an A rating. The bank is now eligible for inclusion in our Safest Emerging Markets Banks at No. 38.
Only two consumer discretionary stocks currently carry long standing Sell Quant Ratings, spanning sub-industries such as specialty retail and distributors.
DICK’S Sporting Goods, Inc. (DKS) leads the list with a Sell rating that has persisted for 36 consecutive days, followed
The buildout raised prices for memory chips, storage equipment, and circuit boards. Prices in a related equipment category rose almost 8% over the 12 months through March 2026, while the broader effect on headline inflation was noticeable but limited.
With global trade fracturing amid tariffs and risk, corporations are rethinking supply-chain costs.
This article appears in the November issue of Global Finance Magazine.
When a Citi analyst pressed SIG Group CFO Ann-Kristin Erkens on the company’s first-half call in July about whether its €80 million inventory build would become permanent, he was asking a version of a question finance chiefs now routinely face: How much should a company pay to protect itself from supply shocks?
Part of the inventory increase came from valuing stock at higher input costs and part of it was deliberate, said Erkens, who has since been promoted to CEO. “There is an element of safety stock in there,” she said; whether the Swiss packaging maker works it down by year-end will depend on market volatility.
Companies that once scoured the globe for the lowest-cost production to feed just-in-time inventories now must account for geopolitical risk, surprise supply disruptions, and the price of keeping operations running when global trade falters.
The new era of de-globalization is complicated by the need to spread costs out. Some are on the balance sheet as extra inventory. Others may be in capex as relocated or duplicate capacity. Sometimes costs appear as financing for a company signing up new suppliers. A CFO who wants to nail resilience must add up these scattered costs and figure out how much the business can recover.
Shock Absorbers
Inventory can be the quickest lever to pull, and usually the first.
At Authority Brands, a consumer services company, some of the larger franchisees and company-run locations bought extra HVAC compressors and outdoor units in the first quarter of 2025, ahead of tariff-driven price increases, said CFO Josh Greear.
In a normal year, those operators carry “weeks of inventory, not months.” Authority Brands negotiated with distributors on behalf of the whole system to lock in stock at existing prices. The manufacturers ended up raising prices anyway, including those building in the U.S., because every competitor’s costs had gone up.
Trane Technologies experienced the same whiplash on a large balance sheet. During the company’s second-quarter 2026 earnings call, CEO Dave Regnery said it had added four times the capacity to its applied HVAC business over the past three to four years, and guided 2026 capex to 2% to 3% of revenue. Part of that build-out runs through the P&L as production ramps up, CFO Chris Kuehn added, and may weigh on operating leverage in the very near term.
Trane is “not going to get behind” and is “not turning away any orders,” Kuehn said.
Francois Motte, CFO of rare-earths developer Aclara Resources Inc., has worked through how to split the cost of resilience with customers and governments.
Operating costs at Aclara, which has operations in Brazil, Chile, and the U.S., are close to Chinese companies’, he said. Its disadvantage is the cost of capital. Governments in the U.S., Japan, South Korea, and Brazil are narrowing that gap with long-dated finance, often 10 to 12 years out and in some cases up to 20. Their backing also tells customers a supplier has survived due diligence, said Motte, which can matter to buyers as much as the money.
Aclara pairs take-or-pay offtake agreements with a minimum price that lasts until its construction debt is repaid, he explained. In return, it offers customers a price cap, protecting them when supply is tight. After the payback period, Aclara is willing to move to index pricing.
Gas turbine makers sitting on years of backlog are paying up for yttrium, a rare earth that makes up about 8% of the mix in thermal barrier coatings, and yttrium now accounts for roughly 30% of the value of Aclara’s output, Motte said. Carmakers competing with Chinese electric vehicles have far less room to pay.
The Cost of Weak Suppliers
Costs that customers refuse to absorb land on suppliers. Rapid Ratings International Inc., a supply chain risk intelligence firm, modeled country-specific tariff rates, assuming suppliers could pass through only about half the added cost. Even in that scenario, the number of public-company suppliers rated High or Very High Risk for weak financial health rose 56%. Among privately held suppliers, the number struggling dangerously more than doubled. (The chart on the left shows changes in financial health scores across sectors.)
RapidRatings CEO Charlie Minutella described how painful this can be in practice.
A manufacturer learns that the supplier of a critical engineered component is heading into financial restructuring. Qualifying a replacement, with new tooling and a production ramp, would take several quarters, and by the time the distress is visible, that window has closed. The manufacturer instead pays a sum in the mid-tens of millions of dollars to keep the supplier operating.
“Wait for headlines or disruptions to emerge, and the only option left is writing the check,” Minutella said.
Late discoveries reach the plant floor, too, observed Catherine Cormier, chief innovation officer at Assent Inc., a supply chain software firm. Manufacturers must retool entire factories and halt production to change a product’s composition for regulators—and some must destroy finished goods they can no longer sell.
Supply chain consultancy Miebach Consulting GmbH, reviewed the sprawling production footprint of a consumer goods manufacturer, including its actual and projected P&L for the previous few years. In each year, an outside event knocked results off plan.
“Find me a year we’ve had a white swan,” quipped Nick Banich, chief revenue officer for Miebach in the U.S. and Canada.
Nick Banich, Miebach
Some shocks had hit more than once, Miebach’s review revealed, so the manufacturer built them into its long-term plan. That made shifting some production from Southeast Asia to Mexico look more attractive. Labor costs would rise 15% to 20% while unit costs would increase 7% to 14%, depending on the product. But cutting about 20 days of ocean transit would free up working capital, and the move would reduce the company’s exposure to another round of tariffs.
Raising inventory on everything can be an easy response, and the most expensive one. After Covid-19, many organizations “beefed up inventory, and it didn’t really solve a lot of the service issues,” Banich said. He argues for segmenting by SKU and by supplier. “It’s not going to make sense to have committed capacity with an additional supplier with machines running at 40% utilization for everything.”
Life sciences companies already hold what they call strategic stock against low-probability, high-damage events, and he said he expects other industries to borrow the approach.
Weld Royal is a contributing writer based in the U.S.
Earnings Call Insights: Liftoff Mobile, Inc. (LFTO) Q3 2026
Management View
“Total revenue was $238 million in the third quarter, an increase of 32% year-over-year.” (CEO & Director Jeremy Bondy)
“Adjusted EBITDA was $145 million, representing a margin of 61%.” (CEO & Director Bondy)
Seeking Alpha’s Disclaimer:This article was automatically generated by an AI tool based on content available on the Seeking Alpha website, and has not been curated or reviewed by humans. Due to inherent limitations in using AI-based tools, the accuracy, completeness, or timeliness of such articles cannot be guaranteed. This article is intended for informational purposes only. Seeking Alpha does not take account of your objectives or your financial situation and does not offer any personalized investment advice. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank.
Michael Burry has increased his bearish bets on the Nasdaq 100 (NDX) and semiconductor stocks, citing concerns about Nvidia’s (NVDA) influence on the AI infrastructure market following Jensen Huang’s departure as CEO.
Earnings Call Insights: Rekor Systems, Inc. (REKR) Q3 2026
Management View
“The third quarter revenue was $10.9 million compared with $14.2 million a year ago,” said Joseph Nalepa (Chief Financial Officer), attributing the decline primarily to “high-margin perpetual ALPR software licenses in our public safety business
Seeking Alpha’s Disclaimer:This article was automatically generated by an AI tool based on content available on the Seeking Alpha website, and has not been curated or reviewed by humans. Due to inherent limitations in using AI-based tools, the accuracy, completeness, or timeliness of such articles cannot be guaranteed. This article is intended for informational purposes only. Seeking Alpha does not take account of your objectives or your financial situation and does not offer any personalized investment advice. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank.
Backlog exceeds current production capacity, prompting active hiring, substantial CapEx, and expansion of the Orlando plant, with a new facility also under consideration. Management is pursuing acquisitions and strategic investments and is trying to announce one RF-product deal before year-end.
The digital lender’s collapse leaves deposit insurance under strain as payouts begin for 1.8 million clients.
A little more than a week after shuttering Ueno Bank, the Central Bank of Paraguay has paid approximately 3.9 trillion guaraníes ($644 million) to more than 1.8 million depositors, according to figures reported Thursday.
The payouts could ultimately drain as much as $928 million, or 58%, from Paraguay’s Deposit Guarantee Fund, according to preliminary central bank estimates. That would leave approximately $672 million in the fund to cover future bank failures, before accounting for any recoveries.
However, any direct contagion risk seems relatively small because deposits, not loans from other banks, funded Ueno Bank, said Rhys Hicks, Associate Banking and Payments Analyst at GlobalData.
“The other banks in Paraguay fund the deposit guarantee scheme, so they will share the bill, and while they seem to be picking up the slack, they are now under some strain,” he said. “A potential issue could be fraud, as these banks are having to onboard so many customers so quickly. In the long run, this should lead to far better regulation in the country, though it may cause costs to rise for everyone.”
An Anatomy of the Pay Out
The central bank began disbursing advances of up to 121.76 million guaraníes from its Deposit Guarantee Fund to each affected depositor on Nov. 5. By the end of Nov. 9, it had made payments to 93.1% of all depositors. The remaining depositors either have restrictions on their accounts, hold certificates of deposit, or have transactions involving the Development Finance Agency.
The fund’s disbursements account for roughly 12.5% of the digital bank’s reported deposits as of Oct. 28.
This is not the first digital bank failure in Latin America this year. According to the Rio Times, Brazil’s central bank liquidated the neobank Will Financeira in January after its controller, Banco Master, collapsed under special administration.
“However, that was more to do with issues at its parent bank, while Ueno’s collapse was caused by its own lending,” said Hicks, adding that the major difference with Ueno was that it was proportionally much larger, reaching around 60% of the adult population.
Rob Daly writes about the economy and fintech. You can reach him at rdaly@gfmag.com.
Editor’s note: This article has been updated to reflect the latest payout totals and the number of depositors paid.
Anthropic’s massive IPO comes with staggering infrastructure commitments and steep operating losses.
Anthropic is expected to price its initial public offering on Wednesday, Nov. 18, ahead of a planned Nasdaq debut on Nov. 19, in what is shaping up to be the largest artificial intelligence IPO to date.
The company launched its roadshow on Tuesday, marketing 825 million shares at $70 to $78 each, including 801.4 million newly issued shares and 23.6 million from existing shareholders. The offering could raise as much as $64.35 billion and, based on the shares outstanding disclosed in its filing, value Anthropic at approximately $1 trillion at the top of the range.
The proposed valuation is below the $1.5 trillion figure that circulated before a recent selloff in technology stocks, suggesting the company is prioritizing a successful debut and strong investor demand over pursuing the highest possible valuation.
Pricing at roughly $1 trillion, with the option to move toward $1.2 trillion, “is the right move,” according to a Nov. 10 research note from merchant bank Yorkville Ives & Co. “A deal of this size gets one shot at its debut, and making it digestible for the market matters more than the last turn of valuation,” the firm added.
An Unusual Sidepot
Alongside the public offering, Anthropic is arranging a $26 billion private placement with seven major tech investors: Alphabet Inc., Nvidia Corp., Advanced Micro Devices Inc., Broadcom Inc., Micron Technology Inc., Microsoft Corp., and Taiwan Semiconductor Manufacturing Co. The combined fundraising could reach $90.4 billion.
The arrangement gives companies with significant commercial relationships with Anthropic — including chip suppliers, cloud providers and distribution partners — stakes in the “Claude” developer before its first public trading session. It’s also a unique setup since several of these investors could also make money from Anthropic’s infrastructure spending.
“Google, Nvidia, AMD, Broadcom, Micron, Microsoft and TSMC have commercial interests in the technology Anthropic needs to expand, giving them potential benefits beyond the return on their shares,” Varun Datta, venture capitalist and Founder of Truth Ventures, told Global Finance. “What’s unusual is having seven major technology companies investing at this scale, including businesses that compete with one another and could also supply Anthropic with the infrastructure it needs.”
Google and Microsoft sell cloud computing capacity, while Nvidia, AMD and Broadcom supply AI chips and related technology. Their potential returns extend beyond Anthropic’s share price because its continued expansion could generate billions in additional orders for their businesses, he explained.
“I’d want to examine whether the investments are tied to purchasing commitments, cloud contracts or preferential supply arrangements,” Datta added.
“Those details matter because they would help establish how much of the capital raised is available for Anthropic to deploy independently, and how much could ultimately flow back to its investors through commercial spending.”
Amended Terms
The proposed range of $70 to $78 a share on 825 million shares tops out below the terms in a filing Anthropic briefly sent to banks — $70 to $80 a share on 866.7 million shares — which a company representative later said contained inaccurate pricing details, Reuters reported.
Anthropic did not respond to Global Finance’s request for a comment.
The startup’s revised terms follow a sharp tech selloff that began Nov. 5, when the Nasdaq fell 5.5% — its worst day since April 2025 — amid concerns that Democrats’ midterm gains could bring tighter AI regulation.
Michigan Senator-elect Abdul El-Sayed, who won on Nov. 3, campaigned on a plan that includes “pausing frontier AI development,” the category that covers Anthropic, according to Harvard’s Ash Center.
A Closely Intertwined System
Google, Amazon.com Inc. and Microsoft are among Anthropic’s backers, customers and computing suppliers, illustrating how tight-knit the AI ecosystem has become.
The company’s substantial infrastructure commitments offer a multi-year demand signal for chipmakers and cloud providers, while raising questions about whether revenue growth can eventually translate into sustainable margins.
The central question for investors will be whether Anthropic can maintain its rapid expansion while bringing computing costs under control. Its second-quarter operating profit and third-quarter loss offer sharply different pictures of the company’s underlying earnings potential.
The offering also comes on the heels of SpaceX’s massive IPO and OpenAI’s expected public listing in 2027. But while Anthropic’s market debut could establish an important benchmark for valuing privately held AI companies, the longer-term test will be whether it can sustain that valuation after the initial excitement fades.
A sharp decline in Anthropic’s share price, as seen with SpaceX, which is down more than 13% year to date, could challenge the investment assumptions underpinning the broader AI investment boom.
Anthony Noto covers corporate finance and private credit. Contact him at anoto@gfmag.com.
Goldman Sachs analysts are pointing to Apple’s (AAPL) experience more than a decade ago as a useful frame for how investors may value Nvidia (NVDA) amid questions around leadership continuity and long-term momentum.
When the world thinks about China, it envisions dazzling cities, technological prowess, and the ubiquitous “Made in China” label. Less visible is the powerful financial industry that helps drive the nation’s economic growth.
But global awareness of China’s banks, asset managers, and other financial-sector firms is growing: driven by a government-led campaign called “baotuan chuhai” (“band together to expand overseas”), a sector-wide commitment to supporting domestic consumers in a challenging market, and the rapid adoption of pioneering digital solutions including AI.
The winners of Global Finance’s 2026 Stars of China awards play a key role in building the sector’s profile, often in more ways than one.
Trade finance, foreign exchange, and other services underpin the financial sector’s support for baotuan chuhai, which urges Chinese enterprises to work together to build industrial supply chains abroad. The campaign aims to establish overseas factories, warehouses, and logistics by leveraging Chinese financing and business-to-business collaboration. Consider three of the financial sector’s recent achievements in promoting Chinese business abroad.
Sustainable Finance Deal of the Year winner Bank of China sponsored a round-the-world roadshow this past summer to encourage internationalization of the renminbi and China’s CIPS system—an alternative to Swift—with stops in France, Chile, Kenya, and eight other countries.
Best Corporate Bank winner ICBC reported its international currency settlements volume grew 45% from January to June 2026. And Best Bank for Green Bonds winner China Merchants Bank issued $600 million in green bonds in September to fund a major expansion project at CATL, an international supplier of vehicle and storage batteries based in Fujian.
These efforts piggyback off long-running programs dominated by state banks, policy banks, and state-run corporations, such as the Belt and Road Initiative and China’s renminbi internationalization campaign. The Hong Kong Stock exchange and Southbound Stock Connect program have facilitated investments by qualified Chinese investors. Now, global payment and settlement services are expanding with guidance from the People’s Bank of China, whose Vice President Lu Lei laid out a goal in August for China to take the lead in elevating the world’s payments clearing industry. China is working with Hong Kong, the United Arab Emirates, and other jurisdictions to build a digital channel between the yuan and multiple other currencies for cross-border clearing.
Wu Wei, president of Hang Seng Bank (China), is among the bankers promoting a “global business layout” for Chinese companies. “More and more enterprises are moving toward a ‘going overseas system’ for assets to establish a complete supply chain for operating locally in target markets,” he told media outlet Sina Finance in August.
More foreign funds, meanwhile, are flowing into China. Last year, investors lined up for China’s first sovereign green bond, issued on the London Stock Exchange, and foreign bank-purchased panda bonds were expected to raise a record amount in 2026.
Yet, foreign investment levels pale beside the resources dispatched by China’s banks to support the homegrown science and technology sector, small and medium-sized enterprises (SMEs), and the nation’s half-billion consumer households. Banks have also responded creatively to challenges tied to the AI race, a soft real estate market, and unstable trade relations with the U.S. and Europe. Consider two steps taken to bolster retail bank customers.
Best Consumer Bank award winner Postal Savings Bank of China is one of several institutions accommodating the accelerating movement of consumer funds from savings accounts into higher-yielding wealth management products. CITIC Group analysts predicted such products will grow 12% nationwide in 2026. And Best Consumer Lending award winner ICBC is encouraging home sales through mortgages arranged with property developers and real estate agencies.
“Meeting the needs of China’s consumers is a fundamental requirement for ICBC to uphold the political and people-centric nature of financial work,” a bank statement noted.
Digital tools, meanwhile, are streamlining financial operations across the board. China Construction Bank’s Huidongni app offers credit applications to its 11 million SME clients while YOUMY Family Office provides AI-powered advisory services. YOUMY Founder Song Ying said, “With risk management at the core, we leverage financial and legal tools to create value.”
Whether working abroad or at home, China’s value-building financial sector is getting more attention.
METHODOLOGY
Global Finance editors select the winners of the Stars of China awards using information provided in entries and independent research based on both objective and subjective factors. It is not necessary to enter to win, but an entry can provide details that may not be publicly available. The editors incorporate insights from executives, academics, and other industry experts. Judgments are based on performance from September 2025 to September 2026. We apply an algorithm to arrive at a numerical score on a 100-point scale. The algorithm incorporates criteria—including knowledge of local conditions and customers, financial strength and safety, strategic relationships, capital investment, and innovation in products and services—weighted for relative importance.
MEET THE WINNERS
A Chinese company with global reach and more than 1,000 upstream suppliers sought to strengthen its international competitiveness by overhauling its treasury department. Ready to help was ICBC, this year’s Best Corporate Bank award winner, a global treasury services provider for about 17,000 of its 14.4 million corporate customers. The bank resolved the company’s funds’ visibility, capital allocation, foreign exchange rate, and cross-border liquidity issues.
Treasury management is just one area of corporate banking where ICBC excels—and helps its clients grow, particularly Chinese companies expanding overseas. The bank has broadened its “Going Global” initiative by expanding credit support in trade finance; the volume of its international currency settlements grew 45% from January to June, underscoring its role in overseas corporate growth. As of June, ICBC’s corporate loan balance exceeded 18.5 trillion yuan. Last year, it disbursed corporate loans worth more than 10 trillion yuan and underwrote more than 560 billion yuan in corporate bonds.
BEST CONSUMER BANK
Postal Savings Bank of China (PSBC)
A retail consumer migration from bank savings accounts to bank-administered wealth management products has grown. The shift, promoted by government policy and encouraged by savings account rates hovering near zero, has helped drive growth and elevated customer service at Postal Savings Bank of China (PSBC), this year’s Best Consumer Bank.
PSBC serves the Main Street economy through some 40,000 outlets nationwide. It has about 681 million clients and that number is growing. Total assets increased 9% year-on-year to 18.6 trillion yuan in 2025 while assets under management climbed to 18.3 trillion yuan, due partly to wealth management expansion. That growth has been encouraged by PSBC’s development of urban wealth management and private banking centers for high-end clients. It also improved wealth management services for retail clients, addressing the bank’s mission to serve every facet of the income spectrum.
BEST BANK FOR SUPPLY CHAIN FINANCE
Guangfa
In China, a typical manufacturer’s supply chain includes geographically dispersed suppliers with a range of credit profiles that can lead to long waits for bank loan approvals. China Guangfa Bank has addressed this challenge by streamlining credit processing with timesaving, industry-leading techniques, earning it the Best Bank for Supply Chain Finance award.
The bank’s innovation dovetails with its mission to support industrial chain finance as a means of bolstering the nation’s economy. Guangfa has streamlined its credit process by setting credit limits according to groups of enterprise subsidiaries and affiliates, using fintech to slash loan processing to 24 hours from 72 hours. It also expanded cooperative links to all of China’s joint-stock commercial banks. Beyond credit processing, it offers a comprehensive supply chain finance platform, Guangfutong, and E-Chain Discounting, a settlements service, which cuts bill management costs for suppliers.
BEST AI STRATEGY IN BANKING
China Merchants Bank (CMB)
The strategy was simple: China Merchants Bank (CMB) set a course for excellence in digital finance by edopting an “AI First” philosophy. In doing so, CMB has promoted AI development and application at all levels to improve workflow, risk management, and retail finance, earning it the Best Bank in AI Strategy award.
The impact of AI First is reflected in, for example, a tenfold increase in average daily token throughput handled by CMB’s 80,000-plus staffers between 2024 and 2025. That was the result of giving 450 employees AI tools through the bank’s FinGPT Large Model Creative Center. A digital assistance system that streamlines communication between middle-office and public-facing staffers topped 3.79 million questions and answers in 2025 while improvements in risk management prevented more than 540,000 suspected telecom fraud transactions. Moreover, CMB credits AI with driving wealth management product growth, boosting bond underwriting, and increasing the value of the bank’s corporate wealth management business to an industry-leading 600 billion yuan.
BEST PANDA BOND ARRANGER
DBS China
Investor appetite for China’s foreigner-friendly panda bonds was expected to hit a record high in 2026; with analysts predicting that total volume would top 200 billion yuan. Supporting and benefiting from the feeding frenzy is DBS China, voted the Best Panda Bond Arranger.
With a quarter-century of experience in Chinese debt capital markets, the subsidiary of Singapore’s DBS ranked first among foreign banks in panda bond issues for financial institutions and sovereign governments. The business is healthy; last year, the bank participated in nine issues worth a total of 35 billion yuan for Barclays Bank, Malaysia’s CIMB Bank, and others. DBS China served as joint lead underwriter on a 5.5-billion-yuan bond issue for Deutsche Bank in March and a 7 billion-yuan bond issue for the Republic of Indonesia four months later.
It’s a mark of creativity as well as a sign of the times when a bank taps China’s data center buildout for debt instruments. ICBC has done exactly that by arranging the use of data center cabinet leases as underlying assets for asset-backed securities (ABS), helping the bank win the Best Debt Bank award.
The digital-age securitization project was launched last year as a new financing model and the first green, ownership-type real estate ABS for China’s fast-growing data center industry. Debt financing is an ICBC specialty. Between April 2025 and March 2026, it successfully closed 208 debt financing projects, including 26 ABS deals, in sectors including transportation, energy, local government, logistics, and tourism. ICBC has a special knack for adjusting to new markets; for example, it tapped into the value of intellectual property assets by turning intangible assets into financing capital. In another recent ABS project, it helped finance energy-saving upgrades for a heavy-equipment manufacturer.
BEST EQUITY CAPITAL MARKETS BANK
Shanghai Pudong Development Bank
A closely regulated equities trading arrangement lets international investors in China buy Shanghai- and Shenzhen-listed stocks and mainland investors buy Hong Kong-listed shares. To encourage this so-called northbound and southbound investment arrangement—and steer funds into science and technology firms—Shanghai Pudong Development Bank recently launched the Hong Kong-Shanghai Innovation and Technology Incubator, securing it the Best Equity Capital Markets Bank award.
With locations in Shanghai and Hong Kong, the project is designed to build a financial services system promoting science and technology innovation and investment road shows, with the goal of raising capital through markets on both sides of the border. The initiative is also a means of enhancing cross-border financial development. Appropriately, the kickoff gathering was timed to coincide with the opening of an SPDB branch in Hong Kong.
INVESTMENT BANKING DEAL OF THE YEAR
Unitree
Investors clamored for shares at the August stock-market debut of Unitree Robotics, whose humanoid robots famously boxed for German Chancellor Friedrich Merz and played ping-pong at the recent World Humanoid Robot Games in Beijing. A key player behind the scenes of the highly successful IPO was lead underwriter CITIC Securities, winner of the Investment Banking Deal of the Year award.
The prospectus noted that Unitree, the international name for Yushu Technology Co., received its first CITIC investment in 2024. The bank then helped raise more than 6 billion yuan on the Shanghai Stock Exchange’s STAR Market, which focuses on technology stocks, exceeding Unitree’s 4.2 billion-yuan target. Unitree is one of many CITIC success stories in the tech sector; in the first half of this year, the firm reported equity underwritings totaling 20.7 billion yuan on the STAR Market.
SUSTAINABLE FINANCE DEAL OF THE YEAR
Bank of China
Investor demand vastly exceeded expectations for China’s first sovereign green bond issue on the London Stock Exchange’s International Securities Market. A key partner for the successful Ministry of Finance fundraiser—Global Finance’s Sustainable Finance Deal of the Year—was Bank of China.
Along with other institutions, BOC served as a joint bookrunner, joint lead manager, and green structuring advisor for the April 2025 issuance, which raised 41.58 billion yuan, nearly seven times more than expected. The oversubscription highlighted strong investor interest in supporting the Chinese government’s green initiatives as well as the bank’s skills as a green bond underwriter with global clout. BOC ranked first on the interbank market in 2025 for underwriting volume with more than 428 billion yuan in domestic green bond issues.
MOST INNOVATIVE ASSET MANAGER
Taikang Asset Management
Applying AI solutions to the financial challenges of an aging population is a skill in high demand in China and mastered by Shanghai-based Taikang Asset Management, winner of the Most Innovative Asset Manager award.
The firm, a subsidiary of Taikang Insurance Group, has adopted an AI-enhanced approach to research that has yielded efficiency gains deepened insight into the market. It has also injected real-time, AI-powered data analysis into fund settlement while integrating a fund clearing system and investment management platform, resulting in less risk and more accurate investment decisions. Beyond AI improvements, Taikang has embraced a central government call to shore up pension finance.
As of June, the firm was managing 1.4 trillion yuan in annuity funds and basic pension funds, serving provinces and municipalities across the country. Additionally, Taikang’s investments also support retirement communities and about 40 health care companies. Looking to the technological future, the firm recently announced a plan to apply AI tools to grow its pension finance business.
BEST BANK FOR OVERSEAS BRANCH SERVICES
CITIC
Given China’s cross-border capital controls, credit card purchases can be complicated for the hundreds of thousands of Chinese students attending universities and other schools overseas. That’s why China CITIC Bank recently upgraded a credit card program specifically for youths studying abroad and their families, garnering the Best Bank for Overseas Branch Services award.
When it was launched in 2023, the “Youth Bank” program offered a Visa card only. But in August, CITIC expanded the study-abroad program’s services to cover students aged 14 and up. It added American Express, Union Pay, and Mastercard, including cash-back schemes, foreign exchange fee waivers, and other perks. Moreover, parents can monitor and control spending. The international arm of CITIC Bank operates a limited number of overseas branches in New York, Los Angeles, London, Singapore, and Hong Kong, but Chinese students can swipe and tap anywhere their Youth Bank credit card is accepted.
STAR OF HONG KONG
China Construction Bank (Asia)
In areas from cross-border wealth management to renminbi internationalization, Hong Kong financial institutions have embraced the city’s first five-year plan for economic and social development, which formally launched in September. Leading the banking sector in support of the plan is this year’s Star of Hong Kong, China Construction Bank (Asia).
As the Hong Kong branch of a mainland giant, CCB (Asia) functions as a bridge between Chinese enterprises and international markets through automated cross-border settlements, by servicing Belt and Road Initiative projects. It is also the top payment agent and trustee for offshore bonds issued by mainland enterprises. The bank also boasts 17% of market share for mainland-to-Hong Kong wealth management investment flows, complementing the five-year plan’s goal of bolstering Hong Kong as a center for cross-border wealth management. CCB (Asia) reported a 91% year-over-year increase in total new retail customers in 2025.
BEST CONSUMER LENDING BANK
ICBC
Stabilizing the country’s wobbly property market and stimulating consumption are near the top of a state-directed list of priorities for banks across China. Leading the financial industry’s charge is ICBC, hands-down the Best Consumer Lending Bank.
The wide array of credit products and services offered by ICBC underscores its commitment in the consumer space. An example is the Housing Ecosystem-plus portfolio, which includes loans for home renovation, parking space, and property auction loan packages. The bank also supports property market stability by offering mortgages in cooperation with property developers and real estate agencies. Its retail finance products include an online- and offline-available digitized loan application tool that can generate an answer for a client in seconds.
ICBC is paying special attention to fresh university graduates, the elderly, and consumers who migrate to urban centers from rural areas. Working with auto manufacturers, it promotes loans to consumers who swap older vehicles for new rides. Between January and June, the bank’s total personal loans rose 100 billion yuan to more than 8 trillion yuan.
BEST BANK FOR M&A
China Merchants Bank (CMB)
By steering a home appliance manufacturer deep into the intelligent auto components business, China Merchants Bank (CMB) has proved its mettle as a leading driver of mergers & acquisitions, making it the winner of the Best Bank for M&A award.
Haier Group’s 2025 acquisition of a controlling stake in Autohome is just one of several high-stakes deals arranged by CMB in the past year. The flurry of activity, generating deal-making volume of more than 250 billion yuan, points to what the bank as a friendlier policy environment for M&A and a boom for business integration in China over the past year.
CMB arranged a syndicated loan for the privatization of Dongfeng Motor, an asset restructuring for coal giant China Shenhua, and Xinchao Energy’s takeover by Inner Mongolia Yitai Coal. Setting the stage for future deals, CMB this year upgraded its Investment Advisor platform to better facilitate equity financing roadshows. The platform serves as a communication channel for buyers and sellers, offering planning, transaction design, financing scheme building, and due diligence support.
BEST BANK FOR BUSINESS TRANSFORMATION
Bohai Bank
Eleven years have passed since the cities of Beijing and Tianj in joined nearby Hebei Province in a cooperative push to strengthen the regional economy, which boasts an 11.5 trillion-yuan GDP and a population of more than 100 million. In May, Bank of Beijing adjusted its focus and injected fresh impetus through an agreement with Tianjin-based Bohai Bank, earning it the Best Bank for Business Transformation award.
Bank of Beijing is the two-bank agreement’s big brother, with total assets of 4.7 trillion, more than twice that of Bohai Bank. At a signing ceremony in Tianjin, Bank of Beijing President Dai Wei reportedly said he “looks forward to comprehensively deepening multi-field business collaboration with Bohai Bank, deepening pragmatic cooperation, and achieving mutual benefit and win-win outcomes.”
Together, the banks pledged to cooperate in areas including corporate finance, syndicated loans, transaction banking, and wealth management. The goal is to further develop the Beijing-Tianjin-Hebei region by collaborating on financing regional infrastructure construction, industrial upgrading, environmental protection, and public services.
BEST PRIVATE BANK
Bank of China
China’s private banking clients are on the move, traveling for business and pleasure around the world. Bank of China has them always covered through a mobile platform and related services, contributing to its profile as Best Private Bank.
BOC offers face-to-face interaction with its bankers and investment advisors at more than 200 private banking centers in mainland cities as well as Hong Kong, Macau, Singapore, and London. Since January, it has offered worldwide access to services through its Global Personal Financial Services, which integrates the bank’s mainland mobile banking platform and a globally accessible platform linked to its Hong Kong subsidiary.
Services at the client’s fingertips include an overview of cross-border accounts and customized asset allocations, remittances, and localized services in more than 10 countries outside China. BOC’s private banking base has accordingly grown to 216,900 clients with a combined 3.4 trillion yuan in assets under management.
BEST PRIVATE BANK FOR SUSTAINABLE INVESTING
Bank of Communications
Private banking and China’s largest mangrove forest are growing together thanks to Bank of Communications, winner of the Best Bank for Sustainable Investing award. The bank is leveraging its 1.43 trillion yuan in assets under management to support marine protection projects in the Zhanjiang Mangrove National Nature Reserve, a refuge for hundreds of bird species in otherwise heavily developed Guangdong Province.
Conservation is one of BOCOM Private Bank’s six areas of charitable services, complementing rural revitalization, assistance for the disabled, support for the elderly and children, cultural and education grants, and medical assistance. These services contribute to the bank’s mission to support client aspirations both for wealth accumulation and giving back.
BEST PRIVATE BANK FOR ENTREPRENEURS
China Construction Bank
Given their grueling work schedules, dedicated entrepreneurs can use a private bank that addresses personal lifestyle as well as business needs. Over the past year, China Construction Bank has upgraded its integrated services for business owners with the pledge to cover “personal, family, corporate, and social needs,” winning the Best Private Bank for Entrepreneurs award.
The upgraded contributed to adding nearly 100,000 entrepreneurs as clients. Growth areas include credit products for entrepreneurs with mid-sized and large enterprises, controlling shareholders of listed companies, founders of tech start-ups, and owners of industrial chains. On the personal side, CCB offers various trusts, health management and travel services. On the business side are customized asset allocation, equity financing, and capital-markets investment support. CCB has also beefed up its digital platform with a dedicated e-Private Banking service for entrepreneurs that’s slashed the time needed for client solutions in areas including investment banking and trust data channels.
BEST PRIVATE BANK FOR ULTRA-HIGH NET WORTH INDIVIDUALS
Ping An Bank
The famous saying about wealthy families, “shirtsleeves to shirtsleeves in three generations” is now being tested in China, where younger generations are inheriting wealth earned after the reform-and-opening-up period began in 1978. Ping An Bank, winner of the Best Bank for Ultra-High Net Worth Individuals, aims to help families prosper well beyond the third generation through its network of family offices.
In addition to offering financial and lifestyle-related services, the family office division of Ping An’s private bank promotes family spirit and inheritance through a raft of personalized services. Wealth and health management, philanthropy, children’s education services, and tax planning are among the offerings. At the end of 2025, Ping An reported serving a substantial number of ultra-high net worth individuals among its 105,600 private bank clients, with more than 1.9 trillion yuan in assets under management.
BEST WEALTH MANAGEMENT PROVIDER
YOUMY Family Office
AI-powered advisory services driven by a buy-side mindset have contributed mightily to growth and performance for YOUMY Family Office, Global Finance’sj choice for Best Wealth Management Provider. The Shanghai-based firm serves thousands of clients from China’s so-called emerging affluent class along with some 500 ultra – high net worth families.
Assets under management at the Shanghai-based firm jumped 32% to $2.1 billion between 2024 and 2025. This propelled a 44% increase in total revenue over that period and including a jump in assets from the high-net worth and ultra-high net worth client categories. YOUMY’s proprietary advisory navigation system for its office consultants and clients—the so-called “C System”—integrates budget simulators and securities portfolio advice. The firm has also embedded AI into office teams.
BEST BANK FOR SUSTAINABLE INFRASTRUCTURE
Bank of China
Waste-to-energy and recycling projects are gaining traction as part of China’s “zero-waste cities” initiative, whose goals include landfill waste reduction. Deeply involved in these and other, sustainability projects is Bank of China, recognized as Best Bank for Sustainable Infrastructure.
BOC participated in raising 300 million yuan last year for a company that builds end-to-end waste treatment systems and currently handles more than 13 million tons of urban waste annually. The bank’s sustainable infrastructure contributions range from Yangtze River and Yellow River conservation projects to emissions reduction efforts in the Greater Bay Area to the Yulin water diversion project. BOC’s total green lending balance surpassed 4.96 trillion yuan last year. Beyond China, it promotes global best practices in sustainable development and is working to facilitate international cooperation on sustainability in 64 countries.
BEST BANK FOR GREEN BONDS
China Merchants Bank
It’s been a big year for green bonds at China Merchants Bank, winner of the Best Bank for Green Bonds award. Highlights include the first-ever bonds supporting emissions controls at China’s seaports; a bond issue to facilitate the installation of low-carbon streetlights and sewer improvements in rural areas; and bonds to benefit the giant battery manufacturer CATL, aimed at expanding production, solid-state battery research, and battery recycling infrastructure.
Through the year ending March 31, CMB participated in 64 green bond projects with total issuance volume worth nearly 123 billion yuan. Its 41 corporate clients allocated the proceeds for wind power, pumped power storage, industrial waste recycling, clean urban transportation, and low-carbon industrial parks. Other projects reflecting CMB’s commitment to sustainability include a 2 billion-yuan Shanghai International Port Group bond issue, which supports a project to cut carbon dioxide emissions by 321,000 tons annually.
BEST BANK FOR CORPORATE SOCIAL RESPONSIBILITY
China Construction Bank
It’s been 16 years since China Construction Bank became the first among its domestic peers to formulate a complete strategy for social responsibility. Today, CCB continues to lead in serving the public, supporting environmental protection, and pursuing sustainable development, earning it the Best Bank for Corporate Social Responsibility award.
CCB has organized its head office and branch staff members to volunteer for a program that dispatches special healthcare vehicles and caregivers for pregnant women in poor, remote areas. Through the program, titled Health Express for Mothers, the bank donated 101 million yuan for 654 vehicles in 25 provinces last year. The bank financially supports environmental protection in the Sanjianyuan National Park as well as education programs for needy children. It has also been deeply involved in relief efforts following the 2025 Wang Fuk Court residential complex fire in Hong Kong. Each program is backed by a Social Responsibility and Consumer Protection Committee under the CCB Board of Directors.
MOST INNOVATIVE BANK
ICBC
Retail bank customers in China requiring human interaction often wait in long lines for turns at a teller window. But a high-tech solution to long waits, called Remote Teller Service, is providing an alternative at about 15,000 branches of ICBC, winner of the Most Innovative Bank award.
The system gives any customer who can operate a simple computer rapid access to an array of services. While seated at a branch outlet workstation, the customer can access their account through facial recognition and interact with a live teller through videoconferencing. It’s highly efficient; a single remote teller can cover up to eight outlets. Transfers, credit applications, corporate account adjustments, and access to more than 30 wealth management products are some of the services available. Processes that used to take hours are now completed in minutes, with no line.
BEST INNOVATION IN PAYMENTS
AsiaPay
China’s leadership in emissions control policymaking has the backing of the country’s financial sector, particularly from public-facing firms like payment services provider AsiaPay. The Hong Kong-based digital solutions vendor now offers thousands of retailers a way to offset their purchases’ carbon footprints, earning AsiaPay the Best Innovation in Payments prize.
The firm’s year-old GreenPay Ecosystem initiative offers a unique “carbon emissions API” that integrates sustainability metrics into payments, allowing merchants and consumers to track their contribution to carbon offsetting. The API calculates the carbon impact of a purchase and presents the data to the consumer at the point of payment. The consumer then has the option to make a carbon offset payment, such as a roundup, via credit card or digital wallet. To date, AsiaPay reports it has recorded a 28% user engagement rate, significantly higher than the industry average for carbon offset prompts.
BEST INNOVATION IN FINTECH
China Construction Bank
Strong innovation in digital finance begins with a strong foundation. China Construction Bank has built that by computing platform incorporating AI, big data, and cloud-native architecture. Adding to CCB’s digital strengths is a project backed by the People’s Bank of China that incorporates the AI operating system GraphBus into the bank’s fintech departments. In recognition of these achievements, CCB takes China’s Best Bank for Innovation in Fintech.
The platform’s advantages range from streamlining the work of CCB’s 12,000-member research and development staff to incorporating AI across the entire application-review-approval process for the bank’s corporate credit portfolio, amounting to some 57 trillion yuan. GraphBus works with CCB’s mature systems to keep business knowledge, control rules, and operational assets under one roof. Underscoring the bank’s leadership is an offer to fintech peers: CCB announced in its Stars of China entry that it is “willing to share its fintech innovation development ideas and large-scale practical experience with global peers.”
BEST TRANSACTION BANK
China Guangfa Bank
Proficiency at preventing bottlenecks in supply chain financing sets China Guangfa Bank apart as winner of the Best Transaction Bank award.
For clients up and down industrial supply chains, as well as state-owned enterprises, Guangfa builds financial ecosystems in cooperation with government authorities and clients. It has built interconnections with more than 10 mainstream third-party supply chain platforms and is working on further connections with the self-built platforms of major state-owned enterprises and leading industrial enterprises.
The bank’s Guangfutong service is a one-stop, comprehensive supply chain finance platform for enterprises and suppliers, integrating factoring, forfaiting, commercial acceptance bill discounts, and letters of credit. The service has cut the time needed for commercial bill discounting to three hours while a bill acceptance payment now takes only 10 minutes.
BEST SME SERVICES BANK
China Construction Bank
A manufacturer of industrial bearings. A commercial chrysanthemum grower. A printing plant. These are a few of the enterprises highlighted in a promotional video for China Construction Bank’s Huidongni mobile app, whose success story helps explain its selection as Best SME Services Bank.
Mobile business solutions supporting a wide range of small and medium-sized enterprises contributed to CCB’s outstanding credit balance of more than 12 trillion yuan as of March; more than 11 million SMEs use the app, accounting for about 23% of total loans to such businesses by China’s Big Six state banks.
Huidongni was a Chinese banking industry first when it was launched in 2018. Since then, the app has streamlined processing loan applications for up to 10 million yuan as well as the approval, disbursement, and repayment processes. Altogether, it currently serves about 16 million SMEs. Moreover, CCB serves its SME clients—particularly high-tech firms—with a comprehensive equity investment and financing service system to help raise funds through capital markets.
BEST ASSET MANAGER
SPDB International Investment Management
Navigating an intricate regulatory landscape is all in a day’s work for asset management firms doing business in China. Even more navigation falls to China’s offshore asset management firms, including SPDB International Investment Management, winner of the Best Asset Manager award.
A subsidiary of Shanghai Pudong Development Bank, SPDBI has delivered outstanding returns while embracing complex cross-border programs such as China’s Qualified Foreign Institutional Investor scheme, Limited Partnership Funds in primary markets, and Open-ended Fund Companies in Hong Kong’s secondary markets. On the mainland, the firm manages equity investments and yuan-denominated industrial funds.
SPDBI’s segregated account mandates total US$930 million while its U.S.-dollar money market fund has delivered weekly yields of 4% and its mainland-Hong Kong equities investment fund posted a 29% annualized return rate in January.
BEST BANK FOR RMB INTERNATIONALIZATION
DBS Bank
DBS is this year’s champion in China’s ongoing campaign to accelerate acceptance of the renminbi, or yuan, as a go-to for international transactions. Together with DBS (China), its mainland subsidiary, and DBS Hong Kong, the Singapore-based bank has built strong onshore-offshore linkages to facilitate renminbi flows. These include seamless cross-border flows for Chinese companies with offshore entities, access to trade financing for financial institutions, clearing services, and foreign-investor access to Chinese markets.
Mainland clients benefiting from DBS’s commitment to renminbi internationalization range from a global e-commerce auto parts supplier to the offshore metals-trading arm of a Chinese state-owned energy group to a Chinese automation company’s subsidiary in India. DBS participates directly in the Cross-border Interbank Payment System (CIPS), the Chinese alternative to Swift, providing clients with flexible and efficient cross-border renminbi rails. For DBS, the reward is offshore renminbi cash deposits that grew 61% and non-resident alien loan balances that skyrocketed 259% between 2025 and 2026.
BEST BANK FOR BELT AND ROAD
ICBC
Green is the color of the financing engine powering ICBC’s success as Best Bank for Belt and Road. From a green intercity train line serving São Paulo to green construction practices for The New Capital office towers near Cairo, the bank supports environmentally friendly projects around the world through Belt and Road, China’s 14-year-old initiative to widen its reach in global trade and infrastructure.
ICBC has taken the lead in financing hundreds of Belt and Road projects in multiple sectors across 70 countries, making it the leader in total investment and financing through green loans and green bond underwriting. A standout example is a US$9.6 billion polyethylene complex under construction in Kazakhstan. The complex aims to help reduce emissions by utilizing gas that is currently flared at a nearby oil field and help Kazakhstan cut its imports of plastics. For the project, ICBC is leading a bank syndicate and working with Chinese contractors.
We use cookies to ensure that we give you the best experience on our website. If you continue to use this site we will assume that you are happy with it.