Banks

How the Banco Master scandal injected chaos into Brazil’s presidential race | Elections News

A historic collapse

One factor in the widespread disillusionment has been the Banco Master scandal. The financial imbroglio has delivered a black eye to both ends of Brazil’s political spectrum.

A range of business leaders, political figures, regulators and judges have been swept up in the scandal.

A mid-sized lender, Banco Master grew aggressively over the last decade by selling high-yield deposit certificates. Some of those certificates offered returns of up to 140 percent relative to Brazil’s benchmark interbank rate.

But Banco Master did not have the assets needed to sustain that output.

It lacked the money to pay back its risky loans, and what assets it did have were diverted to shell accounts, according to prosecutors.

Brazil’s Central Bank ultimately liquidated Banco Master in 2025, as the lender faced a major funding squeeze.

Its owner, Daniel Vorcaro, was subsequently arrested, accused of an array of financial crimes, including money laundering and fraud.

The collapse of Banco Master triggered a nearly $7.7bn payout from Brazil’s Credit Guarantee Fund, the largest disbursement in the nonprofit insurance’s history.

Investigators have suggested that Vorcaro protected his fraud scheme by cultivating influence among power brokers among Brazil’s elite.

Among those implicated in the scandal is Senator Flavio Bolsonaro, the presidential candidate.

Last month, the Supreme Court unsealed documents showing he is under investigation for alleged corruption and money laundering in connection with Vorcaro.

Audio recordings have also surfaced, appearing to show Bolsonaro soliciting the disgraced bank leader for millions in funding. The money was slated as financing for Dark Horse, a film about his imprisoned father, Jair Bolsonaro.

Flavio Bolsonaro has denied any wrongdoing. He described the interaction as a private sponsorship opportunity, unrelated to the Banco Master scandal.

Source link

Caribbean Central Banks Ditch CBDCs

As CBDCs struggle with low adoption, the Caribbean is pivoting to instant payment systems to boost trade and financial integration.

This article appears in the October issue of Global Finance Magazine.

The Caribbean was at the vanguard of adopting central bank digital currencies with the Bahamas’ SandDollar, one of the world’s earliest retail pilots in 2020. A year later, the Eastern Caribbean Central Bank followed suit with its DCash.

With take-up rates low, DCash has since been discontinued as central banks pivot to instant payment systems. The aim is to provide a resilient and flexible system in an area prone to natural disasters and reliant on tourism and remittances as economic drivers.

“These central bank digital currencies had quite poor uptakes. They never really took off,” said Caribbean economist Dalano DaSouza. “Barbados went the route of doing a fast payment system [BiMPay launched on June 12] and the ECCB is embarking on the same journey because they believe that’s where the transformation lies in terms of digital payments.”

The fact that DCash had an outage in 2022 that stopped new transactions for two months did not help consumer confidence and the project was discontinued in February. Jamaica’s Jam-Dex gave the first 100,000 users who signed up a J$2,500 bonus ($15.69), which accounted for about 0.09% of currency in circulation. The 310,443 registered users represent approximately 11% of Jamaica’s population. 

“The lessons learned are that full integration with the banking system is vital. A fast payment system will still be sending and accepting digital payments, but it will be done from the client’s bank account,” DaSouza said. 

WiPay, Lynk and Trinidad and Tobago adopting India’s UIP interface shows a region keen on integrating and expanding its trade opportunities. This includes the possibility of being incorporated into the African Continental Free Trade Area. This would be accomplished via the Caribbean Community’s CAPSS payment system, which is itself based on Africa’s Pan African Payment System platform.

Dalano DaSouza,
Economist

A pilot scheme to harness the Caribbean and African payment systems is underway, involving Barbados, ECCB and the Trinidad and Tobago central banks. The African Export-Import Bank (Afreximbank has been at the forefront of moves to bring the two regions together. The idea that Caribbean countries can join AfCFTA opens a market of 54 countries with 1.3 to 1.4 billion consumers with a combined GDP of approximately $3.4 trillion. 

“Potentially, by using the system to make an instant payment from the Caribbean to a vendor in Africa, you would be bypassing correspondent banks, and you would be bypassing the U.S. and their banks,” DaSouza said.

This removes a barrier to African integration, which is the current issue in the history of payments and having to use correspondent banks in the U.S., England, or Europe.

Digital trade and paperless trade systems reached 73% implementation in 2025, according to the United Nations Economic Commission for Latin America and the Caribbean. 

With the Caribbean piloting the next stage of instant payments, the hope is that this can lead to greater business opportunities, not just regionally but globally. CBDCs arguably started the digitalization of the Caribbean financial system, but now it seems time for instant payments.

“Digital payments will be critical to opening new markets and streamlining old ones,” DaSouza said.

Nic Wirtz is a contributing writer based in Guatemala.

Source link

Revolut’s CEO Says US Banks Are ‘Out of Step’ With Global Consumers | Global Finance Magazine Revolut US Bank Expansion: CEO Cetin Duransoy Interview

Home Banking Revolut’s CEO Says US Banks Are ‘Out of Step’ With Global Consumers

Revolut US CEO Cetin Duransoy reveals plans to target globally minded and “underbanked” Americans as it builds toward becoming a primary bank.

After receiving conditional approval from the U.S. Office of the Comptroller of the Currency for a national bank charter, Revolut Technologies Inc. appears ready to launch a full-scale challenge to traditional banks and fintechs in the United States.

After relatively quick growth in France, Spain, and Italy, Revolut aims to bring its superapp model to the U.S., where it doesn’t exist in quite the same form.

Revolut’s U.S. CEO, Cetin Duransoy, who has held senior roles at Raisin, Fundbox, Visa, and Capital One, spoke with Global Finance about Revolut’s plans for the American market. 

Global Finance: In the US, banks, fintechs, brokerages, travel products and payment apps are mostly separate. Does that surprise you? Do you see a genuine hole in the U.S. market for a company that combines all those relationships in one place?

Duransoy: It’s not surprising, given how complex these products are and how crowded and fragmented the U.S. market is. Layer on the regulatory process, and combining all these product suites—banking, brokerage, FX, crypto, travel, and more—into a single company or app becomes genuinely difficult and, for most companies, not worth the effort.

We believe you need a genuinely differentiated product to succeed in this market, and we have identified an opportunity here. By bringing all these products into one platform, we can remove the friction customers typically experience when cobbling together services from multiple providers.

GF: People often say, “The U.S. banking market is different.” Different how, exactly? And how might those differences affect Revolut?

Duransoy: The US’s fragmented, charter-based regulation can be more cumbersome than the EU’s passporting model, and U.S. customers tend to rely more on credit than their European counterparts. But the U.S. provides certain advantages, including the U.S. card network and interchange system, which subsidize rewards; FDIC insurance; and consumer-protection laws, which create a trust threshold.

Our broad product offering, 80-million-user global network, and strong global brand allow U.S. to cater to the distinct challenges of the U.S. market and understand the challenges of U.S. distribution costs. By obtaining a national bank charter, we will be on par with traditional banks, with direct Fedwire/ACH access and lending capability.

GF: When Revolut enters the U.S. market more aggressively, should Americans expect something close to the European Revolut experience—or will the U.S. product necessarily look much more like a traditional American bank competing on deposits, credit cards and lending?

Duransoy: We are always focused on product-market fit for our customers, and the U.S. will be no different. We’ve publicly shared that we will bring the best of what Revolut offers and provide the products U.S. customers want most, including checking accounts, credit cards, installment loans, FX, and stablecoins. We’ll continue innovating to deliver a distinct, more productive experience for U.S. customers.

GF: One of the things that makes Revolut unusual in Europe is that it sits at the intersection of finance, travel and lifestyle. Is that model central to how you think about the US, or is America more of a banking opportunity?

Duransoy: Yes. Combining our lifestyle products with the financial services that have made Revolut so popular remains central to our thinking. And they’re a key differentiator in many of our markets. We expect these offerings to help make us a top-of-wallet card and strengthen customer retention.

GF: Why should someone with Chase, Amex, Venmo, Robinhood, and a good travel card move meaningful parts of their financial life to Revolut? What can you offer that those companies, individually or collectively, do not?

Duransoy: We recognize that inertia is a strong force when it comes to financial services and that a customer’s bank holds critical parts of their financial life, such as their mortgage or direct deposit.

What we offer is the ability to consolidate multiple products and services into a single interface and remove the friction our customers find frustrating with other services. Revolut’s broad-based platform allows customers to seamlessly access multi-currency spending without foreign transaction fees, instant global P2P, a combined debit/credit product, budgeting, digital assets, and investing, all without transferring funds between platforms or managing multiple accounts. That’s especially valuable for people who travel internationally, have cross-border family ties, or are underserved by traditional credit underwriting.

GF: Which types of lending will Revolut prioritize in the US?

Duransoy: We intend to initially prioritize unsecured and secured credit cards and installment loans.

GF: What does Revolut understand about the consumer relationship that you think many American banks and fintechs still lack?

Duransoy: We treat our global app as the product. We iterate quickly, aim for gamified engagement, and offer frequent feature releases, in contrast to most U.S. bank apps, which have slower release cycles.

We also build for financial lives that span borders and currencies, rather than assuming a single-currency, single-country customer. American banks were largely built for a domestic customer, and that assumption is increasingly out of step with a more mobile, globally connected population.

GF: Do you think Revolut is underestimated in the US? If so, why? Among those who are aware, what do people in the U.S. most commonly misunderstand about Revolut right now?

Duransoy: “Underestimated” is probably right now, largely because our independent U.S. bank doesn’t exist yet. So we’re still seen as a “European neobank” by most Americans. That undersells what we’ll be once we have a full national charter, FDIC insurance, and our full lending capabilities live.

The most common misunderstanding among those who do know the brand is that we’re simply a fintech or a travel debit card, rather than a company with an 80-million-user global base—including 1.4M in the US—and banking licenses now spanning the UK, France, Australia, Mexico, and more.

GF: Are you coming to the U.S. to compete for a small slice of the market, or do you ultimately believe Revolut can change what Americans expect from a bank?

Duransoy: In the US, our near-term goal is to compete for market share. No new entrant can reshape what an entire country expects from a bank on day one. That takes years of trust-building, especially post-charter, when FDIC insurance and regulatory scrutiny are new territory for us.

What we’re looking to do is win the demographics best suited to us, namely the internationally minded, underbanked-by-incumbents, and digitally native users.

GF: On the corporate side, what are Revolut’s corporate banking plans?

Duransoy: Revolut Business exists—and is a core focus for us—in the U.S. We expect this to continue and are excited to launch merchant acquiring within the first years of becoming a bank.

GF: If we revisit this in three years, what would need to be true for you to say that Revolut has successfully become a major U.S. bank?

Duransoy: Within three years, we expect to be a fully operating bank with real momentum. We won’t share specific customer or product numbers today, but we’re building for scale and a sizable U.S. customer base that treats us as their primary bank, not a secondary account. That’s the bar we’re setting for ourselves.

Source link

More Trillion-Dollar US Banks Expected as Consolidation Accelerates

Lighter regulation and excess capital are setting up the biggest U.S. banking wave since the 2008 crisis.

The U.S. banking industry is bracing for its most significant wave of consolidation since the 2008 financial crisis, according to a new Bain & Co. analysis.

The firm expects the number of trillion-dollar U.S. banks to grow from the “Big Four” — JPMorgan Chase & Co., Bank of America Corp., Citigroup Inc., and Wells Fargo & Co. — to as many as seven by 2030. Key drivers include lighter regulation, burgeoning tech and 17 global banks holding over $10 billion each in excess capital. That capital cushion, Bain argues, will lead to a spike in M&A activity.

Banco Santander SA’s August acquisition of Webster Financial Corp. serves as an early example of what could be in store for U.S. banking giants. For Joe Lischwe, a partner in Bain’s financial services and customer strategy practice, the deal illustrates how capital-rich banks are leveraging eased regulatory conditions to combine geographic scale with targeted scope. In this scenario, Santander gets Webster’s health savings account franchise.

“We think there’s a window within this current [Trump] administration over the next two to three years where this will continue to be accelerating,” Lischwe told Global Finance on a call. “You will see more consolidation over the next few years.”

A Capital-Rich Setup

Seventeen U.S. banks currently hold more than $10 billion in excess capital — a figure Lischwe said Bain compiled from a mix of public quarterly filings and third-party data sources, including Refinitiv.

Bain also found that total bank M&A deal value rose 19% in 2025 and is up another 7% so far this year.

“There’s been an uptick in the actual deal value that has been occurring,” Lischwe added. “But I think, probably, the biggest tailwind is from a regulatory perspective.”

The Trump administration continues to move on multiple fronts that matter most to M&A-hungry banks, the latest being on Sept. 17 when the Federal Deposit Insurance Corporation’s (FDIC) proposed new guidelines to make bank mergers easier and faster to approve.

Scale vs. Scope

Not all acquisitions are created equal, according to Bain’s framework, which sorts bank deals into two categories. “Scale” deals expand a bank’s existing footprint — deposits, branches and geographic reach — and generate value primarily through cost synergies.

“Scope” deals, meanwhile, bring in capabilities the acquirer doesn’t already have. Bain predicts that these blended scale-and-scope deals will emerge as the standouts. Capital One Financial Corp.’s acquisition of Discover, which gave Capital One a payments network it previously lacked, produced outsized total shareholder returns on a two-year basis, Lischwe said.

Fifth Third Bancorp’s purchase of Comerica, by contrast, was a more traditional scale play — consolidating similar deposit and branch businesses — without adding new capabilities.

“In general, we were seeing that blended deals, on average, performed better,” Lischwe said. “That’s not to say that scale deals don’t do well.”

The Fintech Integration Trap

Bain’s advice to bank executives is to first conduct a rigorous self-assessment across six dimensions — financial scale, geographic density, business mix, product capability, technology and liquidity — before approaching an acquisition target.

“The answer is not to buy more fintechs,” Lischwe said. “The answer is to know your gaps, diligence those gaps, and then consider every asset that helps you close those gaps.”

Nowadays, fintechs tend to outpace incumbent banks in artificial intelligence, data, payments, blockchain and digital assets — areas that could tempt banks to leapfrog years of in-house development. But evaluating those targets is harder than buying a similar-sized bank, Lischwe said. A fintech operating in an unfamiliar capability area is more difficult to underwrite than a competitor running the same core business.

That complexity introduces significant execution risk for buyers looking to acquire growth quickly.

Winners, Losers, and the Case for Consumers

Jeff Barrington, Windsor Drake Managing Director
Jeff Barrington,
Windsor Drake

Jeff Barrington, Managing Director at tech and payments sell-side advisory firm Windsor Drake, cautions that banks frequently misjudge these acquisitions on several fronts.

“Banks buying fintechs tend to get tripped up in four ways: they pay a growth multiple for revenue that was acquisition cost-fuelled and doesn’t survive inside the bank, they underestimate the cost of bolting a modern stack onto a legacy core, they lose the founders and engineers once the earnout vests, and they misprice the regulatory and partner bank risk that comes attached,” Barrington said. “The recurring error is buying what looks like a growth company and ending up with a bank-owned product that stops growing.”

There’s also the risk of a more concentrated banking landscape: fewer banks means higher fees and diminished access to the kind of relationship-based banking that small towns and entrepreneurs rely on.

Barrington added that while scale can fund improved pricing and technology for users, “consolidation consistently narrows choice, closes branches and thins out relationship lending.

Yes, but …

Banks that fail to acquire or build the AI, data and digital capabilities that are currently reshaping the industry risk falling behind competitively.

“Those [banks] that will be successful are those that will be really ruthless about what are our capability gaps, what can we close inorganically, doing the proper diligence and then properly integrating it,” Lischwe added.

Capital One-Discover, Fifth Third-Comerica and Santander-Webster are recent deals that, so far, have held up. Whether pricier, more speculative targets — he cited digital banking upstart Revolut as an example of an asset banks are watching, despite its rich valuation — get bought will depend on whether acquirers can underwrite a clear strategic fit and value-creation case.

As for whether a change in political control in Washington could derail the trend, Lischwe remains skeptical.

“The regulatory tailwind is going to last,” he said, “through this administration and even into the next one.”

Anthony Noto covers corporate finance and private credit. Contact him at anoto@gfmag.com

Source link

Turkiye revokes operating licence of Iran’s Bank Mellat in Istanbul | Banks News

The Iranian lender has faced years of Western sanctions over alleged ties to Tehran’s nuclear programme.

Turkiye’s banking watchdog has revoked the operating licence of Iranian lender Bank Mellat’s branch in the Turkish city of Istanbul.

“It has been decided to revoke the operating licence of Bank Mellat, Head Office in Tehran, Istanbul Turkey Central Branch,” read the decision by the Banking Regulation and Supervision Agency (BDDK), published in the Official Gazette on Saturday.

Recommended Stories

list of 3 itemsend of list

The regulator said the decision was taken under a clause of Turkiye’s banking law allowing a bank’s licence to be revoked or withdrawn if its continued operation is deemed to pose a risk to depositors’ rights or to the security and stability of the financial system.

Bank Mellat has been subject to Western sanctions for years over accusations that Tehran was pursuing a nuclear weapon under the cover of a civil nuclear programme.

Those sanctions were lifted as part of a landmark 2015 deal between Tehran and world powers to curb Iran’s nuclear ambitions. However, the United States unilaterally pulled out of the agreement in May 2018, reimposing economic sanctions on the country.

Bank Mellat was hit by further US and Gulf sanctions in 2019 after being named as one of 25 entities linked to Iran’s Islamic Revolutionary Guard Corps (IRGC).

The Turkish notice did not cite the US measures or specify operational issues.

Earlier this month, the US Treasury Department imposed sanctions on a small Turkish investment bank and two subsidiaries over alleged ties to Iran.

The Treasury Department accused Golden Global Yatirim Bankasi Anonim Sirketi (Golden Global Bank) of facilitating “tens of millions of dollars’ worth of transactions for the Islamic Revolutionary Guard Corps-Qods Force” and providing the Iranian government with banking access to move its funds internationally.

Golden Global Bank has denied the accusations.

Source link

Bank of Japan raises rates to 31-year high of 1.25% as inflation rises | Banks News

Bank of Japan raises benchmark interest rate from 1 to 1.25 percent, pledging to help counter inflation risks.

The Bank of Japan (BoJ) has raised interest rates by 0.25 to 1.25 percent, pushing borrowing costs to their highest level in 31 years, amid rising inflation and wages, and pressure from Washington.

The move on Friday marked the first hike since June, and takes interest rates closer to levels the BoJ deems neutral to the economy, marking another step away from decades of ultra-low rates that cemented the yen’s status as a cheap global funding currency.

Japan is grappling to contain inflation, which is being driven by factors including rising energy prices, global supply pressures and domestic inflation exceeding the 2 percent target.

Core consumer inflation held steady near the target in August, data showed on Friday, as companies continued to pass on rising costs for a wide range of food and grocery items.

The country also faced a “slow-moving demographic shock” with a shrinking labour pool lifting wages, a structural factor that ⁠cannot be dismissed as temporary, BoJ Executive Director Koji Nakamura said on Monday.

The Federal Reserve’s rate hike on Wednesday, and the prospect of another one later this year, have added pressure on the BoJ to keep pace.

Further widening of the United States-Japan rate gap risks weakening the yen and lifting inflation through higher import costs, analysts told the Reuters news agency.

Its policy rate also remains lower than the European Central Bank, which raised its key rate to 2.5 percent last week.

Such pressure could affect the tone of BoJ Governor Kazuo Ueda’s post-meeting briefing, which will be closely watched by markets for clues on the timing and pace of further increases.

Source link

Central Banks Are Buying Gold Like De-Dollarization Is Already Happening — Are They Right?

Central banks’ record, price-insensitive gold buying is a more credible signal of the dollar’s structural trajectory than this year’s currency markets, because FX markets are structurally bad at pricing the discontinuous, wartime-style tail risk central banks are actually hedging — so this autumn’s calmer dollar should not reassure anyone that de-dollarization has stalled.

In June, the European Central Bank made an announcement most people missed: gold has overtaken US Treasuries as the world’s single largest reserve asset. Central banks bought 289 tonnes of it in the second quarter alone — a record for that quarter and five times Q1’s pace — with Poland’s central bank openly telling investors it was “buying the dip.” Here is the part that should stop you: gold’s price fell 22% between January and September. Central banks were never more convinced buyers of an asset than while it was crashing. Either the reserve managers are wrong, or currency markets — which show none of this urgency — are the ones asleep at the wheel.

Gold peaked at $5,589 an ounce on 28 January, the same month the dollar index hit a four-year low of 95.5 and the dollar’s share of global reserves fell toward its lowest level since 1995. Both moves reflected the same story: Fed rate cuts through 2025, a US debt load past $37 trillion, and BRICS states settling more trade outside the dollar. Then the picture split. Kevin Warsh, confirmed as Fed chair in May, signalled a hawkish pivot in August; the Iran war pushed oil and inflation higher through September, and markets began pricing a rate hike rather than a cut. The dollar index clawed back to 99.46. Gold fell to $4,330. Central-bank buying did not follow the price down — Poland alone added 82 tonnes this year toward a 700-tonne target, and a World Gold Council survey found a record 45% of central banks plan to buy more within twelve months.

State the gap plainly. Two signals, same underlying question — is the dollar-centred monetary order changing — and they disagree by a wide margin. The buying signal says yes, decisively: record quarterly purchases, gold displacing Treasuries at the ECB’s own reckoning, 74% of surveyed reserve managers expecting the dollar’s reserve share to keep falling over five years, and buyers adding tonnage through a 22% drawdown rather than fleeing it. The price signal says not yet: the dollar just posted one of its sharper rallies of the year, gold is down sharply from its high, and nothing in currency markets shows the kind of stress a genuine regime shift would produce.

Stay ahead of the geopolitical week.

MD Briefing delivers expert analysis across five global fronts — the Indo-Pacific, energy, geoeconomics, European security, and the Middle East — every Monday morning. Free.

The strongest objection to trusting the buying signal is a good one, and it needs to be taken seriously rather than waved away: foreign exchange is the deepest, most liquid market in the world, turning over more than $7 trillion a day. A few hundred tonnes of central-bank gold buying — perhaps $30–40 billion a quarter — is a rounding error against that. If professional currency traders, sitting on far more capital and far better short-term information than a handful of reserve managers, saw a serious de-dollarization story unfolding, it would already be in the price. Instead the dollar just rallied. On this view, central banks are not seeing something markets are missing; they are pattern-matching off 2022, when Russia’s $300 billion in reserves was frozen overnight, and over-hedging a tail risk that has not recurred and mostly will not.

That objection assumes FX markets and central-bank reserve committees are pricing the same kind of risk, on the same time horizon, and they are not. Currency markets are exceptionally good at pricing continuous, high-frequency variables — rate differentials, growth surprises, this week’s inflation print — because that is what moves flows daily. They are structurally poor at pricing discontinuous, low-probability events until those events occur: equity volatility did not price 2008 in 2007; sovereign spreads did not price the Russia reserve freeze in the weeks before it happened. A reserve freeze, a secondary-sanctions campaign, or exclusion from SWIFT-style settlement infrastructure is exactly that kind of event — binary, rare, and catastrophic for whoever it hits — which is precisely why Poland’s central bank governor, Adam Glapiński, described his buying not as a trade but as insurance: reserves that keep the state secure “under all circumstances, including wartime, which of course we’re not expecting.” That is not the language of someone chasing momentum. It is the language of someone who manages the one asset class that keeps its value if their country is ever cut off from the dollar system, and who would rather hold it and be wrong for a decade than not hold it and be wrong once.

The buying pattern itself supports that reading. Momentum money sells into a 22% drawdown; insurance money adds to it. Central banks did the latter through the first half of this year, which is the behavioural signature of a structural reallocation program with a fixed multi-year target — Poland’s is explicit, 700 tonnes — not speculative flow riding gold’s rally. Meanwhile the dollar’s autumn recovery has an identifiable, largely cyclical cause: a new, more hawkish Fed chair and a war-driven oil shock forcing a rate-hike repricing. Neither event reverses the debt trajectory, the BRICS settlement trend, or the reserve-freeze precedent that pushed the dollar to a four-year low in January. A rally built on this year’s Fed chair and this year’s war is not proof that last year’s structural story is over; it is evidence that a cyclical force is currently strong enough to mask it.

The Scenarios

Base case (55%): The gap persists rather than resolves. The dollar holds most of its autumn gains through the current rate-hike cycle, gold range-trades below its January peak, and central banks keep buying at a steadier, slower pace toward stated targets like Poland’s 700 tonnes. Nobody is “proven right” on any particular Tuesday, because reserve diversification is a decade-scale hedge, not a trade with a catalyst date. This is the least satisfying outcome for anyone wanting a verdict, and the most likely one.

Downside case (for dollar holders): A discrete trigger — a fresh reserve-freeze or secondary-sanctions episode, plausibly connected to the still-live US-Iran war spilling into action against a third country’s assets, or a shock to Fed independence under a more political Warsh chairmanship — crystallizes the exact tail risk central banks have been hedging. Gold spikes back through its January high, the dollar index breaks below its 95.5 low, and the gap closes in weeks rather than years, vindicating the reserve managers all at once and catching FX markets flat-footed exactly as the theory predicts.

Upside case (for the dollar): The Iran war resolves, Warsh’s rate hikes cool inflation without a recession, US fiscal metrics stabilize, and BRICS local-currency settlement growth stalls on friction between its own members. Central-bank gold buying does not reverse but plateaus as reserve managers hit conventional diversification ceilings — most target 15–20% of reserves in gold, not open-ended accumulation. The gap closes gradually as price drifts up toward the buying signal over several years, with no crisis required to force the reconciliation.

The Takeaway

The dollar’s calmer autumn is not evidence the de-dollarization hedge was a mistake; it is evidence that currency markets and central-bank reserve committees are pricing two different things on two different clocks, and only one of those clocks rings in a crisis. Central banks bought through a 22% drawdown because the point of the position was never this quarter’s return.

Watch for: the World Gold Council’s Q3 2026 Gold Demand Trends report, expected in early November. A third consecutive quarter of buying that ignores price direction will confirm this is policy, not opportunism — and the moment currency markets have to agree with that policy will not be a quiet one.

Source link

At Toronto, hunting for the next ‘Obsession’ on the banks of Lake Whatever

For 10 days, the center of the cinematic universe is the Toronto International Film Festival, whose closest geographical landmark is currently a ludicrous controversy.

“Welcome to TIFF and welcome to the beautiful shore of — say it with me — Lake Ontario,” festival CEO Cameron Bailey said on opening night as he introduced “Being Heumann,” director Sian Heder’s crowd-pleasing follow-up to her best picture Oscar-winner “CODA.”

The crowd said it back. Google Maps, however, insists that the festival is actually a 15-minute stroll to Lake America. I’ve yet to hear a single person call it that without an eyeroll.

What’s in a name? Last year in the spirit of patriotism, my favorite Toronto coffee shop taped over the menu listing for its Americano to re-dub it a Canadiano. This fall, the sign has returned to Americano. Taking a pause from politics, I ordered a flat white.

Yet, the festival’s programmers seem to be decentralizing their attention-hogging neighbors to the south. Typically, TIFF is a launch pad for awards contenders. But there are fewer high profile Hollywood filmmakers this year than usual — which was also the case in Cannes. Perhaps these international festivals are testing their own waters to see if they’re obliged to invite Americans to their party.

Instead, the Toronto line-up boasts pointed films about fascism. On its surface, Michaël R. Roskam’s “Le Faux Soir” is a procedural account of how a network of rebels in occupied Belgium published its own parody issue of a pro-Nazi newspaper on the 25th anniversary of Armistice Day in 1943. Most of the script’s energy goes to talking about typesetting and rotary press flongs, but right before the end credits roll, “Le Faux Soir” blurts out its timeliness about combating Le Fox News with comedy. Metaphorically alluding to the satirical newspaper “The Onion,” the narrator says that to pull off this operation, the team had to stick together like layers of an onion: “Never forget, onion is strength.”

Plenty of local comedies abound, including “The Stunt Driver” by Michael Dowse (“Goon”), an energetic biopic about Ken “The Mad Canadian” Carter, the ’70s speedster who vowed to vault across the mile-wide river between Ottawa and New York in a rocket-powered Lincoln Continental. The site of Carter’s jump is four hours away from the fest, although at his car’s top speed of 280 mph, you could get there in less than one. Safer just to enjoy Jay Baruchel’s funny and endearing portrait of a reckless risk-taker who hates being called a daredevil as much as he resents Ben Foster’s Evel Knievel attempting to give him some advice. “Canadians are God’s chosen people,” Carter growls defiantly. “The last thing we need is a Yankee doodle dandy telling us how to do our jobs.”

It’s also possible that this year’s lack of big films — unlike 2025’s “Frankenstein,” “The Smashing Machine” and “Wake Up Dead Man: A Knives Out Mystery” — is just a reflection of the industry’s changing tides. Two of the buzziest guests at this year’s fest have been Inde Navarrette of the micro-budget horror hit “Obsession,” which premiered at last year’s TIFF, and British Columbia-born Hudson Williams of the TV hockey romance “Heated Rivalry.” Twelve months ago, both actors were anonymous Gen Z-ers who could have easily popped into Tim Hortons for a maple-glazed donut without causing a stir. Now they’re stars.

Personally, I’m all for fresh talent. Audiences and critics alike are bored of film executives clinging to the same proven names and proven plots as tightly as worry beads. Yes, I’m hoping to see some Oscar contenders while I’m here and have my fingers crossed for a few movies I’ll be seeing shortly. But for the sake of filmgoing at large, I’d be more thrilled to spot another under-the-radar “Obsession.”

So far, I haven’t found one. However, I have seen ingenuity made for peanuts, like Jenna Cato Bass’ “Future Tense,” a South African sci-fi drama about a travel service that allows the wealthy to blip back to the 1600s to hot tub under the clear skies before the land was ruined by centuries of trash, trade and colonization. Mismatched new couple Tara and Lwando (Kristen Raath and Lawrence Maleka) — she’s white and sunny, he’s Black and snide — take a blistering vacation that their relationship might not survive.

The script gets screwy in the last act, but Bass proves she can pull off a bold time travel premise using only tastefully bland décor, gorgeous nature footage and a couple of menacing brutes with guns. As a bonus, Raath, her lead, has the spunk, charm and smile of Karen Allen, giving a breakout performance that’s such a delight that you could almost swear the “Raiders of the Lost Ark” ingenue had leapt back four decades to star in the film.

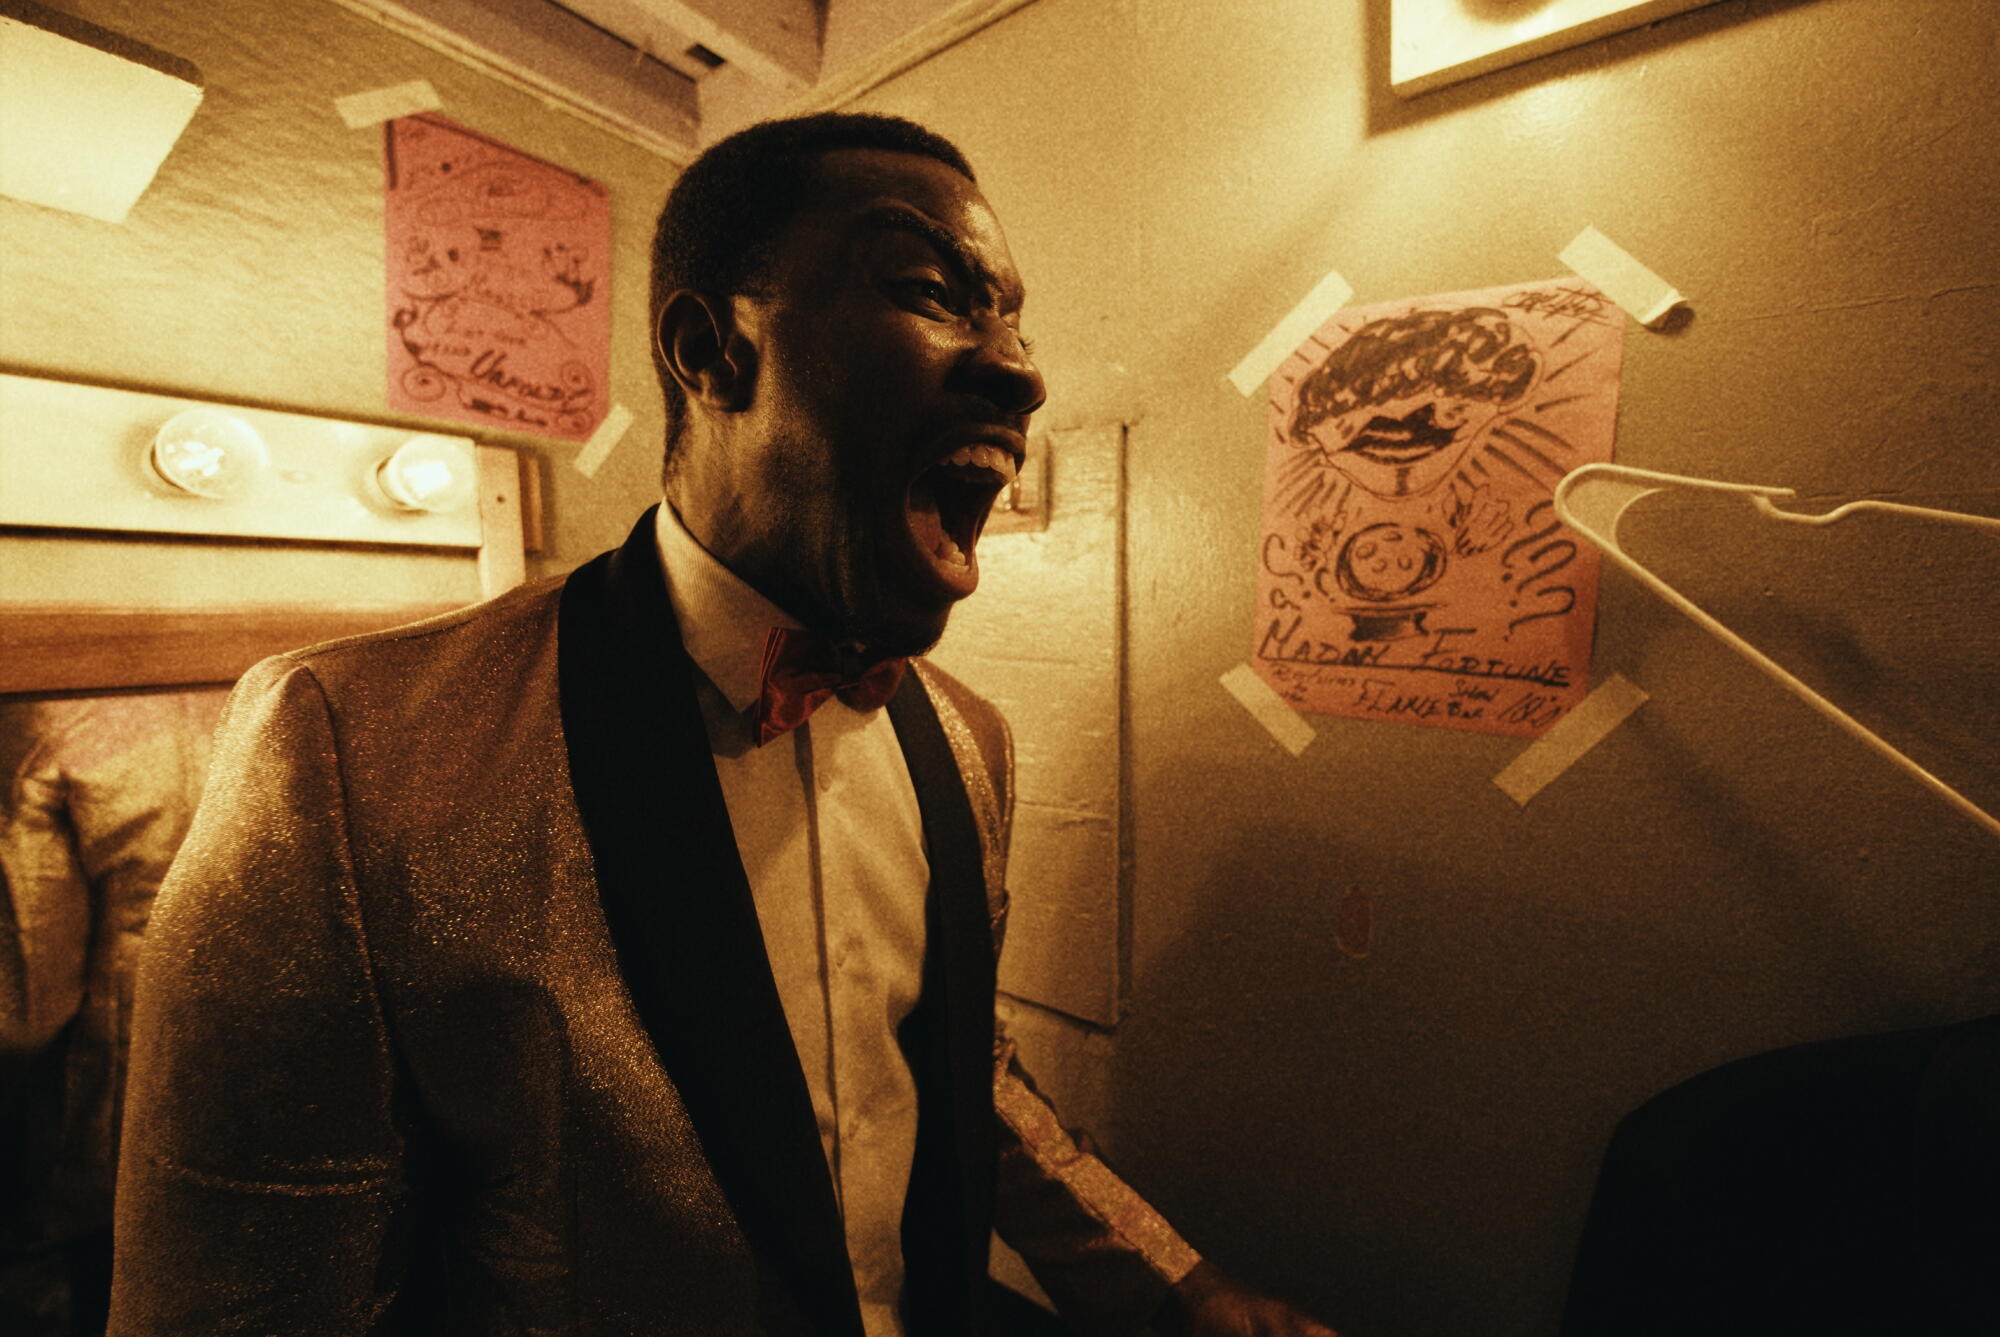
A man in a suit sings in a small room.

An image from “Voices,” a musical drama set in the 1960s.

(TIFF)

While we’re talking about pivotal moments in personal histories, nine years ago Deanté Gray was a rookie wide receiver for the Houston Texans. He tore his ACL in practice and, after muscling through that disappointment, is now a first-time feature director with “Voices,” a lean and loud musical-thriller about thwarted dreams. Set in one tatty motel room in 1967 Detroit, “Voices” is a vicious flick about rising two soul acts hellbent on getting on stage that night to impress Motown Records’ Barry Gordy.

Technically, only the Harmony Brothers, Bubbles and Melvin (Joe Maye and Jamal R. Averett), are booked to play the gig. But a fame-hungry bellboy, Jordan (Francis C. Edemobi), and his cousin Derrick (Ezekiel Ajeigbe) hatch an impulsive, half-baked plan to perform in their rivals’ place. Egged on by Derrick’s ambitious girlfriend Mia (Raél Ba), who’s angling to be the duo’s opening act, this bad idea crescendos with a half-dozen original songs — and a body count.

The sound design of “Voices” is raw and the rumored $50,000 budget so strapped that minor period piece inconsistencies like cheap plastic trash cans sneak into the frame. Who cares? Sam Buckner III and Charlie T. Savage’s smart and surprising screenplay is crowded with scenes that let its cast shine. Someone — ideally, several people — in here will wind up getting their own major break.

Admittedly, I’m biased. Morbid musicals are one of my favorite micro-genres, from “Little Shop of Horrors” and “All That Jazz” to “A Star Is Born” and “Cabaret.” (If you haven’t seen Steve Martin’s 1981 Depression-era hoofer “Pennies From Heaven,” do that this week.)

Add Theo Rhys’ “Stuffed” to that list. Jodie Comer (“Killing Eve”) plays a goth taxidermist; Harry Melling (“Pillion”) is a lonely man terrified of dying, buried and forgotten. Can she convince the sad sack to kill himself now to become a piece of her permanent collection?

The plot alone gives you the shivers, nodding to predatory internet meet-ups and that volatile mix of victimization and egomania that causes people to hurt themselves and/or others. Dark as the story is, though, co-writer Joss Holden-Rea’s tunes are stunners with limber melodies and creatively off-kilter lyrics. “My past is still before me,” Melling belts, picturing himself proudly mounted in a velvet suit and bronze plaque.

“Stuffed” isn’t for everyone. But my fellow sickos are going to love this bleak and lovely tragicomedy once it sets sail from these shores (whatever they’re called by then) to a theater near you.

Source link

China injects over €45 billion into state banks and insurers as growth slows

Beijing has reached for its chequebook.


ADVERTISEMENT


ADVERTISEMENT

The Chinese finance ministry is advancing a 360 billion yuan (€46.1bn) package to businesses, announced on Sunday through statements from the companies involved and reported by state news agency Xinhua, making it one of the larger interventions in China’s financial system this year as growth slows.

The Chinese banks take the bulk of it, roughly 290 billion yuan (€37.2bn), intended to preserve their capacity to keep lending as Beijing presses them to increase support for economic activity.

Xinhua reported the injection would strengthen the institutions’ “sound operating capabilities, risk resistance capabilities and ability to serve the real economy.”

The Agricultural Bank of China is pursuing a private placement of A-shares worth up to 160 billion yuan (€20.5bn) and the Industrial and Commercial Bank of China up to 100 billion yuan (€12.8bn), with the finance ministry among the investors.

Unusually, so is the China National Tobacco Corporation, which operates the state tobacco monopoly and the Export-Import Bank of China which will receive 30 billion yuan (€3.85bn).

Insurers account for the remaining 70 billion yuan (€9bn).

China Life Insurance Group, the country’s largest life insurer, gets 35 billion yuan (€4.5bn) and China Taiping Insurance Group 7 billion yuan (€900mn).

The People’s Insurance Company of China plans to raise up to 15 billion yuan (€1.9bn) through a private placement to the ministry, China Export and Credit Insurance Corporation receives 10 billion yuan (€1.28bn), and China Reinsurance Group is raising 3 billion yuan (€385mn).

Insurers have been squeezed from two directions as years of low interest rates have eroded investment returns, while the government has directed them to put money into Chinese equities.

The currency has been moving in the same direction.

The Chinese yuan reached its strongest level against the US dollar since January 2023 on Monday, trading at around $0.149, a firmer exchange rate that also happens to blunt a long-standing American complaint about Chinese currency management, weeks before talks in Washington.

Beijing’s busy month

The capital injection is not the only move Beijing is making this month.

Chinese President Xi Jinping is reportedly preparing to bring a large delegation of business executives to his Washington visit on 24 September, according to sources cited by news agencies.

It would be a notable departure from customary practice.

Xi rarely travels with corporate leaders, many of whom lost standing after the regulatory crackdowns on technology, education and property that began in 2020, and the last comparable delegation accompanied him to the US more than a decade ago, in 2015.

Washington’s response has also been curious.

“The White House is not tracking a Chinese CEO delegation,” a US official said, without explaining what tracking meant in this context, leaving the statement short of either confirmation or denial.

The gesture would be reciprocal in any case.

When US President Donald Trump visited Beijing in May, he brought a roster of American CEOs including Elon Musk, Tim Cook and Jensen Huang. Bringing Chinese counterparts to Washington would signal a willingness to invest and trade with the US, while handing the White House potential economic wins before November’s midterm elections.

Expectations for the summit itself remain modest, with the two sides still divided over which products should count as non-sensitive under trade arrangements.

US Treasury Secretary Scott Bessent, US Trade Representative Jamieson Greer and Chinese Vice Premier He Lifeng are due to meet in early September to work on deliverables.

Source link

US imposes sanctions on Turkish bank, prompting legal threat | Banks News

US sanctions Turkish bank over alleged IRGC ties, accusing it of facilitating millions in transactions for Iran.

The United States Treasury Department has imposed sanctions on a Turkish bank and its subsidiaries over alleged ties to Iran, as Washington seeks to economically isolate Tehran.

The Treasury Department accused Golden Global Yatirim Bankasi Anonim Sirketi (Golden Global Bank) on Friday of facilitating “tens of millions of dollars’ worth of transactions for the Islamic Revolutionary Guard Corps-Qods Force” and providing the Iranian government with banking access to move its funds internationally.

Recommended Stories

list of 4 itemsend of list

Washington alleged the bank “was established for the purpose of enabling Iran’s rahbar network [shadow banking system] to transfer oil revenues from China to Turkey” using gold and cash.

Golden Global Bank responded on Friday, saying it fulfilled all local and international banking compliance rules and would take legal action against the US-imposed sanctions.

There are no transactions conducted by Golden Global Bank that could substantiate the claims made by the US, the bank said in a news release.

“We will exercise all our rights of objection and legal recourse in the most effective manner and will take the necessary actions at the earliest against these allegations and the decision,” the Turkish bank added.

“Financial institutions continue to find out the hard way that we are serious about Operation Economic Outcast,” said Secretary of the Treasury Scott Bessent in a statement published by the department on Friday.

The sanctions place the bank and its two subsidiaries on the US Office of Foreign Assets Control (OFAC)’s Specially Designated Nationals list, cutting off access to the US financial system.

The bank said individuals and entities named in the OFAC decision “have never been and are not currently customers” of Golden Global.

US Ambassador to Turkiye Tom Barrack said on Saturday that it would be a mistake for Turkish officials “to read [the US’s] narrow measure as a judgement upon Turkiye”.

“The health of the Turkish financial system is not in question; the conduct of one institution was,” Barrack said on X.

Last week, the US took steps towards severing the UAE operations of Egypt’s second-largest bank from financial access after accusing it of processing transactions for companies linked to Iran’s shadow-banking system.

Bessent said on Tuesday on the sidelines of a G20 summit that Washington would likely announce a bank sanction this week and another next week, as it ramps up its economic campaign against Tehran.

Source link

‘Buy holiday cash now’ and ‘save €230’ ahead of ‘change after this week’

Experts have given their take on where the Pound is

Experts have urged Brits to buy holiday cash now as the Pound is expected to weaken over this week’s market chaos with a warning that “it’ll hit wallets immediately”. Bond yields have risen sharply, increasing the cost of government borrowing and renewing concerns about whether Britain’s growing public-debt burden is sustainable.

Although higher yields can sometimes support a currency by offering investors better returns, Sterling has weakened as markets focus instead on inflation, rising debt costs and the Government’s limited financial room ahead of the Budget. The Bank of England is expected to hold interest rates at 3.75% this month, leaving it caught between supporting economic growth and preventing higher energy and import costs from fuelling another wave of inflation.

For households, a weaker Pound could mean more expensive holidays, fuel, food and other imported goods. Rising gilt yields can also push up swap rates, placing further pressure on fixed mortgage pricing just as many borrowers prepare to refinance.

Dave Huggett, founder of Lucid Foreign Exchange, said there was no need to be patient when buying your holiday cash.

He added: “Higher gilt yields and worries about debt sustainability tend to weigh on the Pound. Not always straight away and not always by much, but it’s one more thing dragging on sentiment. When investors get nervous about a country’s finances, they usually want more reward to hold that currency, or they just move their money elsewhere.

“So what do you do? Buy it all now, or hold in the hope of a recovery. The answer to that always lies in the need, not the want. If you’re buying currency to go on holiday, you basically get what you’re given. ‘Getting it right’ on a few thousand Pounds still doesn’t really move the dial. But if the numbers are bigger, and the situation can afford a bit more patience, then zooming out and looking at the situation objectively often pays.”

Iain Thompson, director of Evolve Finance, said everything was affected by a weaker Pound.

He added: “A sliding Pound is a quiet inflation tax on everyday households. When the Bank of England holds interest rates down while government borrowing costs climb, currency markets lose confidence, causing Sterling to steadily weaken against the Dollar and Euro. For the average person, this isn’t just an abstract financial chart – it’ll hit wallets immediately.

“A weaker Pound means everything the UK imports, from petrol to supermarket groceries, becomes instantly more expensive, keeping domestic inflation sticky. Holidaymakers will feel the sting the fastest at the exchange bureau. If you have a trip planned over the coming months, waiting and hoping for a sudden Sterling recovery is a high-risk gamble.

“While predicting currency is never guaranteed, the downward pressure is real. If your holiday budget is tight, locking in half of your travel cash now protects you from worst-case rate drops, ensuring a sudden currency dip won’t derail your family holiday budget before you even pack your bags.”

Tony Redondo, founder of Newquay-based Cosmos Currency Exchange, said the Bank of England was between a rock and a hard place.

He added: “Rising UK gilt yields are a double-edged sword for the Pound. At first, they boost Sterling’s appeal, a fatter carry-trade return over rival currencies. But soon markets ask why yields are climbing: borrowing costs rising as investors fret over debt sustainability, with the UK’s debt pile racing toward £3 trillion.

“That leaves the Bank of England boxed in; raise rates to choke off the inflationary wave from Brent crude above $95 or hold rates down to protect growth. My money’s on Sterling grinding lower, toward $1.30 and €1.13 ahead of the 28 October Budget, as fiscal deficits erode investor confidence.

“For consumers, a weaker Pound means pricier holidays abroad and imported inflation with higher supermarket bills, fuel costs, and goods prices. Elevated yields also lift swap rates, pushing fixed mortgage pricing higher. Anyone with confirmed overseas costs should buy currency in tranches now, hedging against further falls without gambling on timing.”

Prem Raja, head of trading floor at Currencies 4 You, said people could save as much as €230.

He added: “The rise in gilt yields is not automatically good news for Sterling. UK 10-year borrowing costs reached 5.29%, their highest since 2007, but the Pound still fell below $1.35. Investors appear more concerned about inflation, debt costs and the Government’s limited room ahead of the October Budget than attracted by higher yields.

“The Bank of England is expected to hold rates at 3.75% this month. If markets scale back expectations of a later rise, Sterling could lose another 1-2% over the coming months. GBP/EUR is around €1.16-€1.17, but €1.15 is realistic if fiscal concerns grow. GBP/USD could retest $1.33-$1.34, although US developments matter too.

“Travellers would notice that: a 2% fall means roughly €230 less when exchanging £10,000. I would not tell everyone to buy everything now, but anyone with a confirmed Euro or Dollar requirement should consider securing part of it and staggering the balance. That limits the risk of further weakness without committing everything at one rate.”

Anita Wright, chartered financial planner at Ribble Wealth Management, said a weaker Pound arrived in people’s shopping baskets within weeks, not months.

She added: “Everyone will watch the Pound against the Dollar and Euro. That’s the wrong yardstick. Those currencies are run by governments with the same problem so the Pound can look stable at the bureau de change while quietly losing purchasing power where it matters the supermarket, the petrol station, the energy bill.

“The real test of a currency is what it buys at home, and on that measure Sterling has been slipping for some time. What’s actually going on is this. The BoE holds bank rate down while the gilt market demands 5% and more. That gap gets filled by the Bank buying gilts, which is printing money by another name.

“More Pounds chasing the same goods. Diesel is already tightening and Britain imports most of its energy and much of its food, so a weaker Pound arrives in your shopping basket within weeks, not months. On holiday money swapping Pounds for Euros just moves you from one leaking boat to another.”

Samuel Mather-Holgate, managing director and IFA at Swindon-based Mather and Murray Financial, said there was no point waiting for the Pound to get stronger.

He added: “Sterling is not staring at an instant cliff edge, but the warning lights are flashing. With 10-year gilt yields around levels last seen in 2008 and the Pound slipping below $1.35, markets are telling Britain the free lunch is over. Higher borrowing costs squeeze the Treasury, unsettle mortgage markets and make imported goods, fuel and holidays more expensive if the Pound weakens further.

“For families, this is felt at the airport exchange desk, in supermarket prices and in the next remortgage quote. I would not tell people to gamble on currencies, but anyone with a known Euro or Dollar cost in the next few months may prefer certainty over trying to outguess a very twitchy market. Waiting for a stronger Pound is starting to look like a heroic assumption.”

Nouran Moustafa, practice principal and IFA at Roxton Wealth, said the weak Pound could be seen in airports.

She added: “The Pound is being squeezed from both sides. UK borrowing costs are rising, but markets still expect the Bank of England to hold Bank Rate at 3.75% this month. Sterling has already slipped to around $1.35 and €1.16. For households, this becomes painfully real at the airport.

“A weaker Pound means your hotel, meals and spending money abroad quietly become more expensive without the price tag changing. But I would not tell somebody to panic-buy thousands of Euros today based on a currency forecast. Nobody can reliably call Sterling over the next few weeks.

“If you know you need €2,000 or $3,000 for a trip, buying it in stages is far more sensible than gambling your entire holiday budget on one exchange-rate prediction. The bigger warning is this: when markets lose confidence in government finances, ordinary people eventually feel it. The bond market may look boring. Its consequences absolutely are not.”

Source link