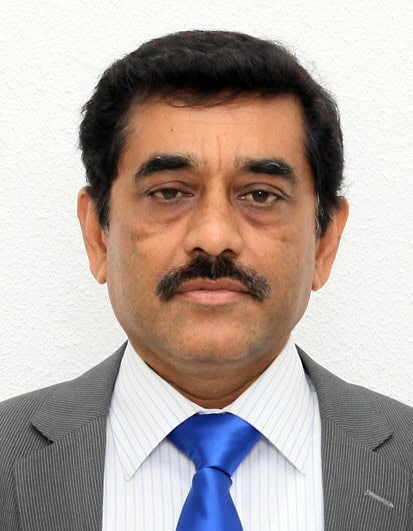
Sri Lanka’s central bank governor discusses reforms supporting the country’s recovery and resilience to shocks.
Nandalal Weerasinghe has served as governor of the Central Bank of Sri Lanka since April 2022, delivering his trademark steady post-crisis stewardship amid new external supply shocks. In Global Finance’s October Central Banker Report Cards, he received a B+.
He achieved macroeconomic stabilization after Sri Lanka’s 2022 financial crisis, and perhaps most tellingly, headline inflation—which had been negative or near zero through much of 2025—turned positive. It rose to 8% as of August, driven by energy price pressures linked to the Middle East conflict. Gross official reserves held firm at around $6.5 billion to $6.8 billion, their highest level since the crisis, burnishing Weerasinghe’s credentials as a safe pair of hands, supported by net FX purchases and IMF program inflows.
Global Finance: Four years after the 2022 default, what would you tell a global investor is durable about Sri Lanka’s recovery now?
Nandalal Weerasinghe: A key improvement since the crisis has been the restoration of a more stable and predictable macroeconomic environment, supported by a comprehensive governance framework and reform agenda, including the new Public Financial Management Act, the new Central Bank of Sri Lanka Act, a strengthened anti-corruption framework, and progress on debt restructuring. Unlike the pre-crisis period, Sri Lanka now operates within stronger policy and institutional frameworks, with predictable policies and improved policy buffers, making the economy more resilient to shocks.

This resilience has been evident in the country’s ability to absorb recent shocks, including Cyclone Ditwah and the ongoing Middle East conflict, while maintaining macroeconomic stability. With continued policy discipline and effective coordination, Sri Lanka is better positioned to manage external shocks, preserve stability, and sustain the economic recovery.
GF: With inflation targeting 5% and the Overnight Policy Rate held at 8.75%, how do you weigh the risk of easing too soon to support growth against the risk of letting prices drift and having to tighten again?
Weerasinghe: After nearly three years of an accommodative monetary policy stance, the Central Bank proactively tightened policy in May 2026 by raising the Overnight Policy Rate by 100 basis points to 8.75% to anchor inflation expectations and dampen second-round effects of the energy shock. While inflation initially stemmed from higher global energy prices, domestic demand has also strengthened, as reflected in robust private-sector credit growth and rising import demand.
Monetary policy will remain focused on maintaining inflation at the target rate and will remain data-driven. Policy decisions are also taken in a more forward-looking manner. In this context, we will closely monitor global developments, particularly in the Middle East and their implications for Sri Lanka and calibrate the policy stance as warranted by the evolving outlook.
Meanwhile, economic growth has been robust, with real GDP growing by 5.1% and 4.2% in Q1 and Q2 2026, respectively, following two consecutive years of over 5% annual growth. We expect growth to be driven by growth-supportive reforms rather than short-term policy stimulus.
GF: Official reserves have rebuilt toward the $7 billion range, yet the rupee still moves sharply — under what conditions will the Central Bank buy dollars, sell dollars, or stay out and let the market set the rate?
Weerasinghe: The Central Bank continues to maintain a flexible, market-determined exchange rate regime in line with the Flexible Inflation Targeting (FIT) framework. A flexible exchange rate serves as an automatic stabilizer, allowing the currency to adjust to external and domestic shocks. The Central Bank’s foreign exchange market interventions primarily aim to minimize excessive exchange-rate volatility and support the accumulation of foreign exchange reserves to strengthen external sector buffers. From January to August 2026, the Central Bank purchased US$1.5 billion net from the domestic foreign exchange market.
GF: After domestic debt optimization and the IMF Extended Fund Facility reviews, when will Sri Lanka regain routine access to international capital markets, and what would a first post-restructuring sovereign issue need to look like?
Weerasinghe: Following the completion of the debt restructuring process, the IMF’s recognition of the progress achieved under the EFF-supported program, the Government’s strong fiscal performance and continued commitment to reforms, together with improvement in Sri Lanka’s sovereign credit ratings, provide a stronger foundation for rebuilding investor confidence and gradually restoring access to international capital markets. Nevertheless, Sri Lanka’s re-entry into international capital markets should be viewed as a market-driven process rather than being tied to a predetermined timeline. With the ongoing fiscal consolidation process, which has been faster than envisaged, there is no urgency to access international capital markets, and the government’s decision will depend on multiple factors, including global market conditions.
GF: The 2023 Central Bank Act split the old Monetary Board into a Governing Board and a Monetary Policy Board — how does that new architecture protect the Bank if fiscal or political pressure returns before the next election cycle?
Weerasinghe: The Central Bank of Sri Lanka Act No. 16 of 2023 strengthens the institutional separation between monetary and fiscal policy. The Secretary to the Treasury is no longer a member of the Bank’s decision-making bodies. Board members are appointed through a rigorous process for six-year terms, and the Act subjects their removal to specified statutory grounds and the approval of the Constitutional Council. These provisions provide critical safeguards for the independence of the Bank’s decision-making bodies. The Act provides for the Bank’s autonomy and accountability and safeguards the exercise of its statutory functions. The prohibition on direct monetary financing of the Government provides an important safeguard against fiscal dominance.
The provisions of the Central Bank Act, which rule out fiscal dominance and ensure independent, accountable, and transparent policymaking, will support monetary discipline and financial stability for years to come.
Jonathan Rogers is a contributing writer based in Vietnam.