finance

How China Plus One Is Transforming ASEAN Trade

Supply-chain diversification fuels a growing Southeast Asian financial ecosystem.

This article appears in the October issue of Global Finance Magazine.

China Plus One (C+1) is a supply-chain-focused strategy in which companies retain substantial manufacturing and sourcing in China while adding at least one other country. The C+1 strategy is rapidly shifting manufacturing to countries in the Association of Southeast Asian Nations (ASEAN), boosting foreign direct investment (FDI), expanding trade surpluses, and driving GDP growth.

At the same time, the Regional Comprehensive Economic Partnership (RCEP)—a free trade agreement among 10 ASEAN member countries plus Australia, China, Japan, New Zealand, and the Republic of Korea—is boosting intraregional trade and the cross-border use of local currencies, thereby germinating a potentially formidable Southeast Asian financial ecosystem.

China’s unmatched supplier density, scale, and infrastructure are retained, but concentration risk is mitigated by building capacity in ASEAN (or elsewhere). If a manufacturing site or supplier faces a tariff hike, lockdown, or political shock, production can shift rather than halt. Even without these factors, costs are substantially reduced.

A clear example of C+1 in action is Taiwan’s Foxconn, which operates factories in Bac Ninh Province in northern Vietnam, where its plant assembles Apple’s AirPods and MacBooks using high-value parts manufactured in China.

The industrial base remains in China, with ASEAN serving as a tariff and resilience hedge. Vietnam has benefited from a cumulative $5 billion in Foxconn’s FDI in the country from 2007-2026—according to Taiwan Stock Exchange and Bac Ninh local government data—to create manufacturing capacity and more than 100,000 jobs in Vietnam.

The FDI story exemplified by Foxconn has been echoed across ASEAN. “Since 2021, FDI in the region has been exceptionally strong, with annual inflows exceeding $200 billion, compared with an annual average during the last decade of less than $130 billion,” according to the ASEAN Investment Report 2025, published last October by the ASEAN Secretariat and the UN Conference for Trade and Development (UNCTAD).

That report tallies 2024 inflows at $226 billion. Underlining the ASEAN dynamic in relative global terms, FDI was up by 8.5% that year while global FDI fell 11%.

“The strategic importance of ASEAN in global supply chains has strengthened significantly over the past decade, catalyzed by the China Plus One strategy, which aims to mitigate risks arising from geopolitical tensions and search for more-resilient production networks,” said Han Teng Chua and Radhika Rao, senior economists at DBS. 

“The region’s open and foreign-investor-friendly policies, coupled with companies’ efforts to expand markets, diversify risks, and optimize costs, could drive ASEAN-6’s FDI inflows to grow at a robust CAGR of 7% over the next decade.” ASEAN-6 is a bloc comprising Indonesia, Malaysia, the Philippines, Singapore, Thailand, and Vietnam.

Funding the Trade Finance Gap

Alongside the FDI narrative sit two burning issues: the pressing need to finance ASEAN trade, which is characterized by an “unmet gap” between demand and trade finance; and the underpinning of the region’s economies by micro, small, and midsize enterprises (MSMEs) and SMEs.

A joint assessment by the U.K. Growth Gateway and Boston Consulting Group, dated February 2024, puts the ASEAN-specific unmet gap at roughly $350 billion to $400 billion and estimates that closing even 10%-20% of that gap could unlock $85 billion to $105 billion in “trade value uplift” and about 6 million jobs in the region’s trade-related industries.

But a big reason for the region’s unmet gap is the preponderance of SMEs and MSMEs. According to the ASEAN Secretariat, these account for 97.2% to 99.9% of all business establishments. Collectively, SMEs and MSMEs generate about 85% of employment, contribute 44.8% of GDP, and supply 18% of national exports, making them central to job creation, inclusive growth, and value-added activity across both urban and rural areas.

The sobering fact is that about 40% of these companies’ trade-finance applications are rejected, according to the Asian Development Bank (ADB), often because applicants lack sufficient collateral, complete documentation, or an established credit history.

This is compounded by ASEAN’s fragmented nature and the urgent need to fully digitize trade and trade finance in a region that still relies on paper documentation. The Model Law on Electronic Transferable Records (MLETR) is the solution: a legal template that ASEAN countries can incorporate into law so that a digital original of trade documents has the same legal status as a paper original.

Singapore implemented MLETR in 2021, and the hope is that ASEAN’s Digital Economy Framework Agreement will push the rest of the region to align with it.

“Carbon copies still choke ASEAN trade—slow ships, costly credit, shut-out SMEs. MLETR is the legal unlock. Singapore is live. Mass uptake isn’t guaranteed, but the shift would be seismic,” said Alicia Garcia-Herrero, chief economist for Asia Pacific at Natixis, in Hong Kong.

Singapore’s move came in preparation for the RCEP, which came into force in 2022 for the first 10 ratifying countries. The 15 RCEP member countries represent the world’s largest trade bloc by population and economic size—about 30% of global population and GDP.

The RCEP aims to cut tariffs on more than 90% of goods traded among its members by 2042 and also covers services, investment, e-commerce, and intellectual property. Intra-RCEP trade rose sharply in 2022 to around $1 trillion and stood at around $6 trillion last year. The agreement has positively impacted trade for Cambodia, Laos, Myanmar, and Vietnam with other RCEP partners—exports from Cambodia to RCEP countries account for more than 60% of the country’s total trade.

Rebuilding ASEAN’s Trade Plumbing

Digitalized supply-chain finance—anchored in distributed-ledger technology—and local-currency settlement can rebuild ASEAN’s trade plumbing around firms, not just banks. Anchor buyers channel liquidity to SME and MSME suppliers, bypassing the need for collateral and thereby helping to fill the unmet gap.

The ADB’s Trade and Supply Chain Finance Program (TSCFP) helps close the unmet gap in SME trade finance by issuing AAA-rated guarantees and loans through more than 250 partner banks, enabling smaller firms in developing Asia to import, export, and access supply-chain working capital that private lenders would otherwise typically withhold.

In August, Steven Beck, TSCFP director, relocated to Singapore, in a move that reflects the city-state’s preeminence as an ASEAN supply-chain and trade-finance hub. “Being here means we can work much more closely in this energized ecosystem, feeding off the energy and exchanging ideas in a way you just can’t do remotely,” he said.

“It’s been a remarkable year,” Beck added. “Our business is up over 60% compared to the same period last year, which is a huge jump for a program that already supports about 20,000 transactions worth over $5 billion annually. Part of that is just persistent, unmet demand for trade finance in markets that have historically been underserved.”

Settling invoices through ASEAN’s Local Currency Transaction Framework alleviates dollar scarcity that bedevils the trade arena in smaller ASEAN economies and reduces foreign exchange spreads and correspondent-bank delays that hinder SME and MSME exporters. Linked digital platforms—e-invoicing, QR-code payment networks, and regional payment connectivity—convert those flows into reusable credit data. The result is a tighter, cheaper intra-ASEAN financial ecosystem in which trade transactions themselves become the collateral.

Jonathan Rogers is a contributing writer based in Vietnam.
Source link

U.S. Banks’ Urge to Merge

This article appears in the October issue of Global Finance Magazine.

U.S. banks are merging again as a rare combination of a friendlier regulatory environment, excess capital among the bigger players, and the rising cost of competing in artificial intelligence continues to drive broad industry consolidation.

S&P Global Market Intelligence data shows that 81 banking deals were announced in the U.S. in the first half of 2026, the largest first-half tally since 2021.

The resurgence in banking mergers and acquisitions follows a regulatory shift that began in May 2025, when the Office of the Comptroller of the Currency restored expedited review and a streamlined application process for the industry’s mergers. Two months later, the Federal Deposit Insurance Corp. rescinded its 2024 policy statement on bank mergers and returned to its earlier guidelines, broadening the regulatory overhaul.

The practical effect has been a shorter path from announcement to completion: Median deal time fell from 187 days in 2024 to 134 days in 2025 and 94 days so far this year, according to S&P Global.

Bankers responded with a series of deals, including Huntington Bancshares’ acquisitions of Veritex and Cadence Bank and PNC’s purchase of FirstBank. By the fourth quarter of 2025, bank deal value had reached $26.3 billion, the highest quarterly total since early 2019.

“If you are a bank looking ahead at succession planning or at the technology investments to compete as you get bigger, there is this window within this administration,” said Catherine Mealor, a Keefe, Bruyette & Woods managing director. “If you think you might want to sell within the next three or four years, you might as well go now. You can get it closed quickly.”

According to PwC research, five banking deals worth more than $5 billion were announced in the latest four-quarter period, pushing aggregate deal value to roughly the same level as the previous four quarters despite a lower volume of transactions.

The consolidation pressure is also coming from the capital side of the equation. Recent research by Bain & Co. found that 17 U.S. lenders each held more than $10 billion in excess capital at the end of June, with seven above $20 billion.

The same research also found that deals combining scale with new capabilities delivered total shareholder returns 14 to 18 percentage points above scale-only transactions over the past two years, as banks face rising costs to build and maintain technology and artificial intelligence capabilities.

Bigger Deals Become the Norm

That appetite for scale is visible in this year’s largest transactions. Santander’s $12.2 billion acquisition of Webster Financial created a $327 billion-asset bank, while Fifth Third’s $10.9 billion purchase of Comerica produced the ninth-largest U.S. bank. Pinnacle Financial Partners’ merger with Synovus created another institution with more than $120 billion in assets.

Sellers, though, may not agree with buyers regarding a franchise’s worth. The median price paid for a bank seller is about 141% of tangible book value, according to Piper Sandler, while 68% of banks surveyed by Bank Director say they would require at least 175% to sell.

Thomas Monteiro is a contributing writer based in Spain.

The post U.S. Banks’ Urge to Merge appeared first on Global Finance Magazine.

Source link

G20 finance ministers, central bankers gather amid fallout from Iran war | Business and Economy News

The G20 finance ministers and central bank governors are gathering in Bangkok, Thailand, on Thursday amid an uncertain global outlook shaped by the US-Israel war on Iran.

The meetings are being held in conjunction with the annual meetings of the International Monetary Fund (IMF) and the World Bank, taking place in the Thai capital from October 12 to October 18.

Recommended Stories

list of 4 itemsend of list

Here are some of the key details about the meetings:

What are the G20, the IMF and the World Bank?

The G20 is an economic forum comprising 19 large economies, including the United States, China, the United Kingdom, Australia, Brazil, India, Japan, Indonesia and Saudi Arabia, as well as the European Union and the African Union.

The grouping has an annually rotating presidency, currently held by the US.

Together, the G20 countries account for about 85 percent of global gross domestic product (GDP) and three-quarters of global trade.

The G20 was established in 1999 as a forum for finance ministers and central bank governors to address shared economic concerns in the wake of the Asian Financial Crisis, before expanding into a broader forum for national leaders.

The IMF, based in Washington, DC, is an international financial institution that promotes international cooperation on monetary policy, trade and economic growth.

Its membership includes all but a handful of the world’s sovereign states, including North Korea, Cuba, the Vatican City and Monaco.

The World Bank, also based in Washington, DC, primarily serves as a provider of loans and grants to developing countries. It has 189 member countries.

The IMF and the World Bank were created at the 1944 Bretton Woods conference in the US, convened by the Allied Powers to establish the contours of the post-World War II international financial order.

Who will be attending the meetings?

Most finance ministers and central bank governors of the G20 will be in Bangkok, along with IMF Managing Director Kristalina Georgieva and World Bank Group President Ajay Banga.

US Treasury Secretary Scott Bessent will be a notable absence from the gatherings, as the top economic official of the world’s biggest economy and G20 chair.

US officials have cited “domestic engagements” for Bessent’s decision to skip the events, at which Washington will be represented by Deputy Secretary Francis Brooke and Undersecretary for International Affairs Erin Browne.

The G20 meeting, one of several gatherings of the group’s finance ministers each year, will help shape the agenda for the headline leaders’ summit in Miami, Florida, taking place on December 14-15.

What is on the agenda?

The economic fallout from the US-Israel war on Iran is expected to dominate discussions.

Attacks across the Middle East have upended economic activity across the region, while disruption to shipping in the Strait of Hormuz has driven a surge in energy prices worldwide.

Crude oil prices have exceeded $100 a barrel for much of the past eight months, placing a strain on government coffers and household budgets, particularly in the Gulf region and the rest of Asia.

In advance of the meeting, Australia’s Treasurer Jim Chalmers MP said he would use the discussions to call for an end to the conflicts in the Middle East and the reopening of the Strait of Hormuz “because that’s what the global economy desperately needs”.

“The war in the Middle East is having a devastating economic impact and is pushing up fuel prices, inflation and interest rates around the world,” Chalmers said in a statement.

Other issues likely to feature on the agenda include the ballooning debt levels of many countries, which exceed 100 percent of GDP in the US, Canada, Japan, Italy and France.

In a speech on Wednesday, Georgieva warned that mounting debt posed a threat to the global economy and that there was no “magic” formula that would allow governments to avoid tax hikes or spending cuts.

G20 members will also bring more specific individual concerns to the table based on their economic and geopolitical priorities.

The US, for example, has repeatedly expressed concern about “global imbalances”, a veiled reference to China’s state-driven industrial model that has allowed Chinese exporters to flood overseas markets with cheap goods.

US President Donald Trump has long claimed that China’s large trade surplus, which stood at a cumulative $938bn in September, proves that international trade is stacked against US manufacturers.

In a statement addressed to the IMF on Wednesday, Bessent called for action to address mismatched trade balances.

“This especially includes strengthening its analysis and engagement on the role non-market policies and practices and exchange rates play in driving external imbalances,” Bessent said.

“Policymakers around the world are having difficult discussions about how to sustain market-based systems amid distortionary policies from some economies that skew competition and hurt employment.”

Divisions and competing interests cloud the prospects for coordination, however.

At the last meeting of G20 finance ministers in Asheville, North Carolina, US, held on August 31 and September 1, member countries failed to issue a joint communique after China objected to language to do with trade.

Source link

Middle East Conflict Opens New Shipping Opportunities for Africa

As ships bypass the Red Sea, increased traffic around the Cape of Good Hope could benefit African economies.

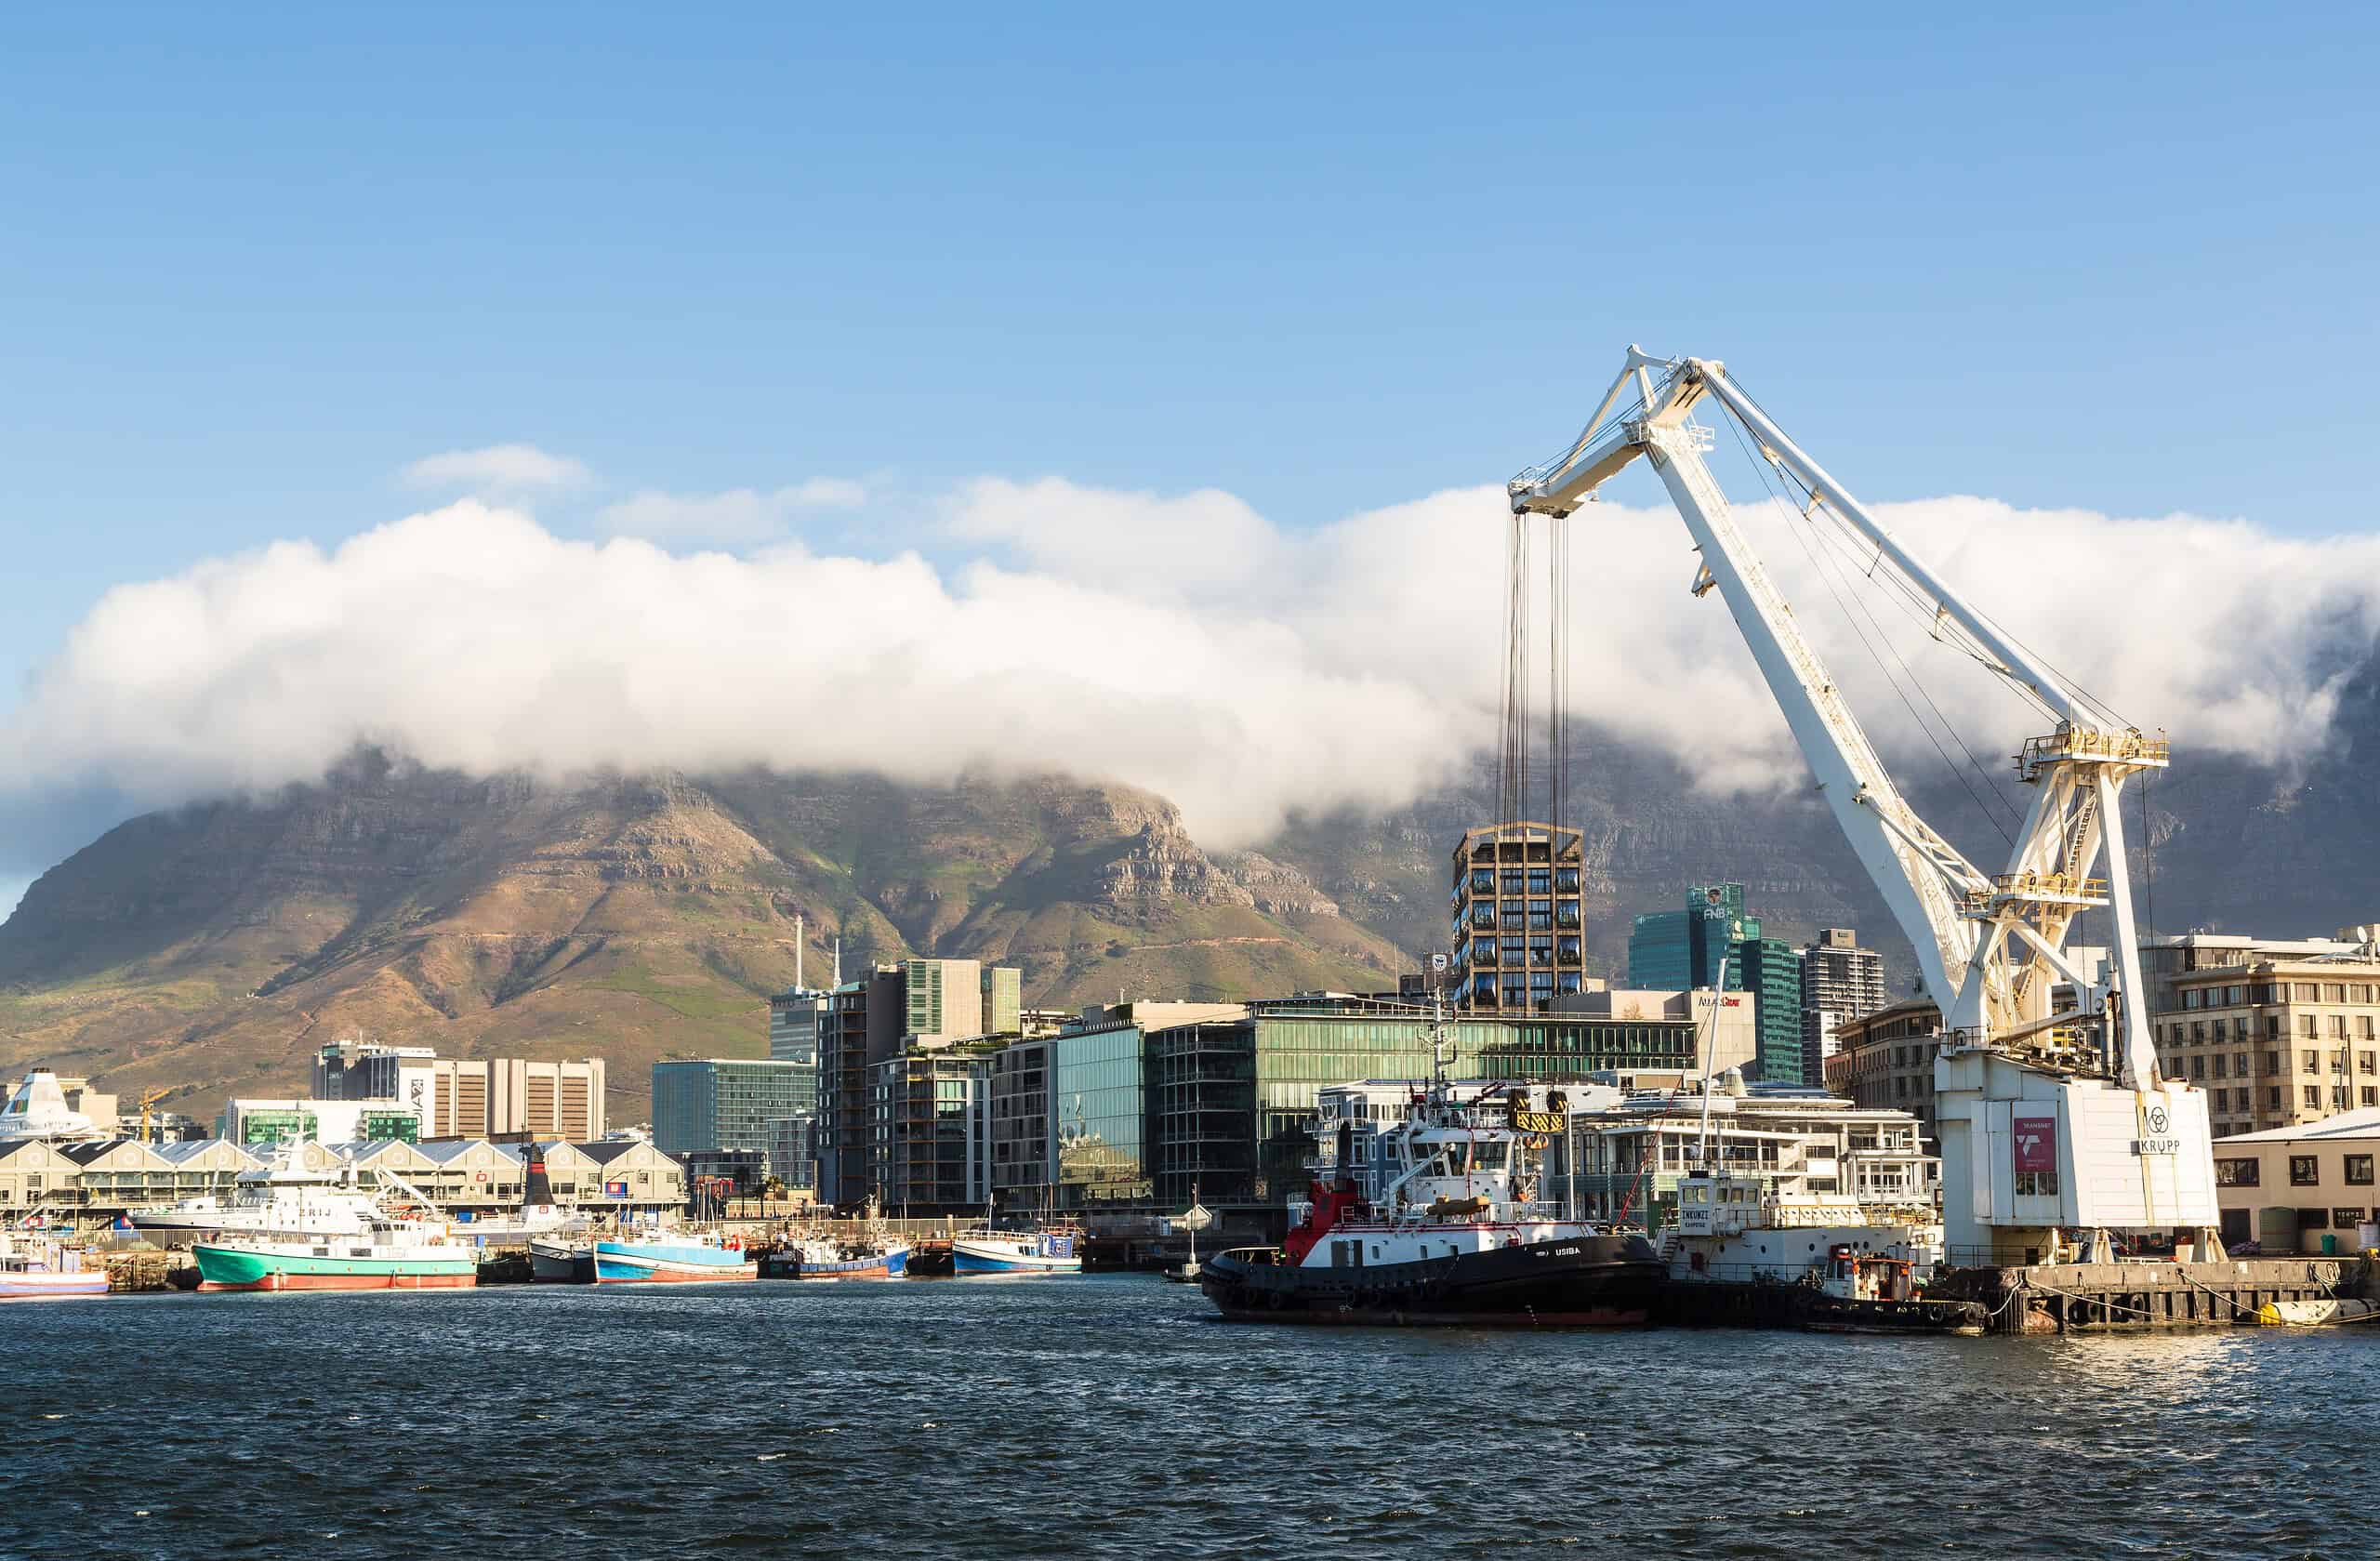
The ongoing conflict with Iran in the Strait of Hormuz and attacks by the Houthis, a Yemen-based militant group, in the Bab el-Mandeb Strait have forced many shipping companies to explore alternative routes around Africa. While the financial and operational costs are significant, the shift presents new economic opportunities for African countries, particularly those positioned to serve the growing volume of maritime traffic.

The main detour causes international shippers to bypass the Red Sea and the Suez Canal corridor, traveling around the southern tip of Africa past the Cape of Good Hope. This longer route can add up to two weeks to a trip from Europe to Asia, increasing energy and shipping costs.

The Cape of Good Hope was already one of the world’s busiest sea routes before recent developments, driven by the conflict with Iran that began in February 2026. According to the U.S. Energy Information Administration (EIA) World Oil Transit Chokepoint Report, released in March 2026, approximately 9 million barrels per day of crude oil and petroleum products pass around the Cape of Good Hope, accounting for 11% of global seaborne oil trade.

Despite the additional shipping time and cost, many major container operators still chose to divert mid-voyage from the original Suez Canal route because of ongoing threats and blockades, as the Houthi forces continue to advance along the Red Sea coast and target regional maritime traffic.

New Shipping Opportunities for Africa

The increase in traffic around Africa, and more specifically around the Cape of Good Hope, provides various African countries with new economic and diplomatic opportunities. The main economic benefits stem from the expenses and services associated with the new shipping routes. 

First, the Institute for Strategic Studies Africa 2026 Report highlights that most vessels do not call at South African ports. These ports can offer international shippers key high-value services, including ship repair and maintenance, crew changes, resupply, and medical support. While major South African and Namibian ports, such as Durban and Walvis Bay, can provide a full range of services and logistics connectivity for this new traffic pattern, other countries, such as Kenya and Mauritius, can also connect this traffic to the Indian Ocean shipping needs.

Second, global pressure to replace shipping fuel with more sustainable, environmentally friendly alternatives is creating strong renewable energy markets and green hydrogen potential in African nations, along with an opportunity to capitalize on this shift. A recent report by the European Council on Foreign Relations shows that countries such as Morocco and Kenya can serve as major marine refueling hubs. As trade and investment in renewable energy have become a diplomatic currency in Africa, the ability to influence shippers’ emissions can strengthen diplomatic relations among relevant nations.

Finally, as almost 70% of the previous Red Sea freight has been rerouted around South Africa, according to the Center for Security and International Studies, African nations like Djibouti are becoming key players in the new maritime security space. These nations can offer foreign nations improved physical and technological maritime security and use it to advance negotiated diplomatic and commercial goals.

Source link

After Bangkok Floods, IMF and World Bank Weigh Global Risks

IMF and World Bank’s annual meeting explores economic resilience amid climate risk, debt pressure, and AI.

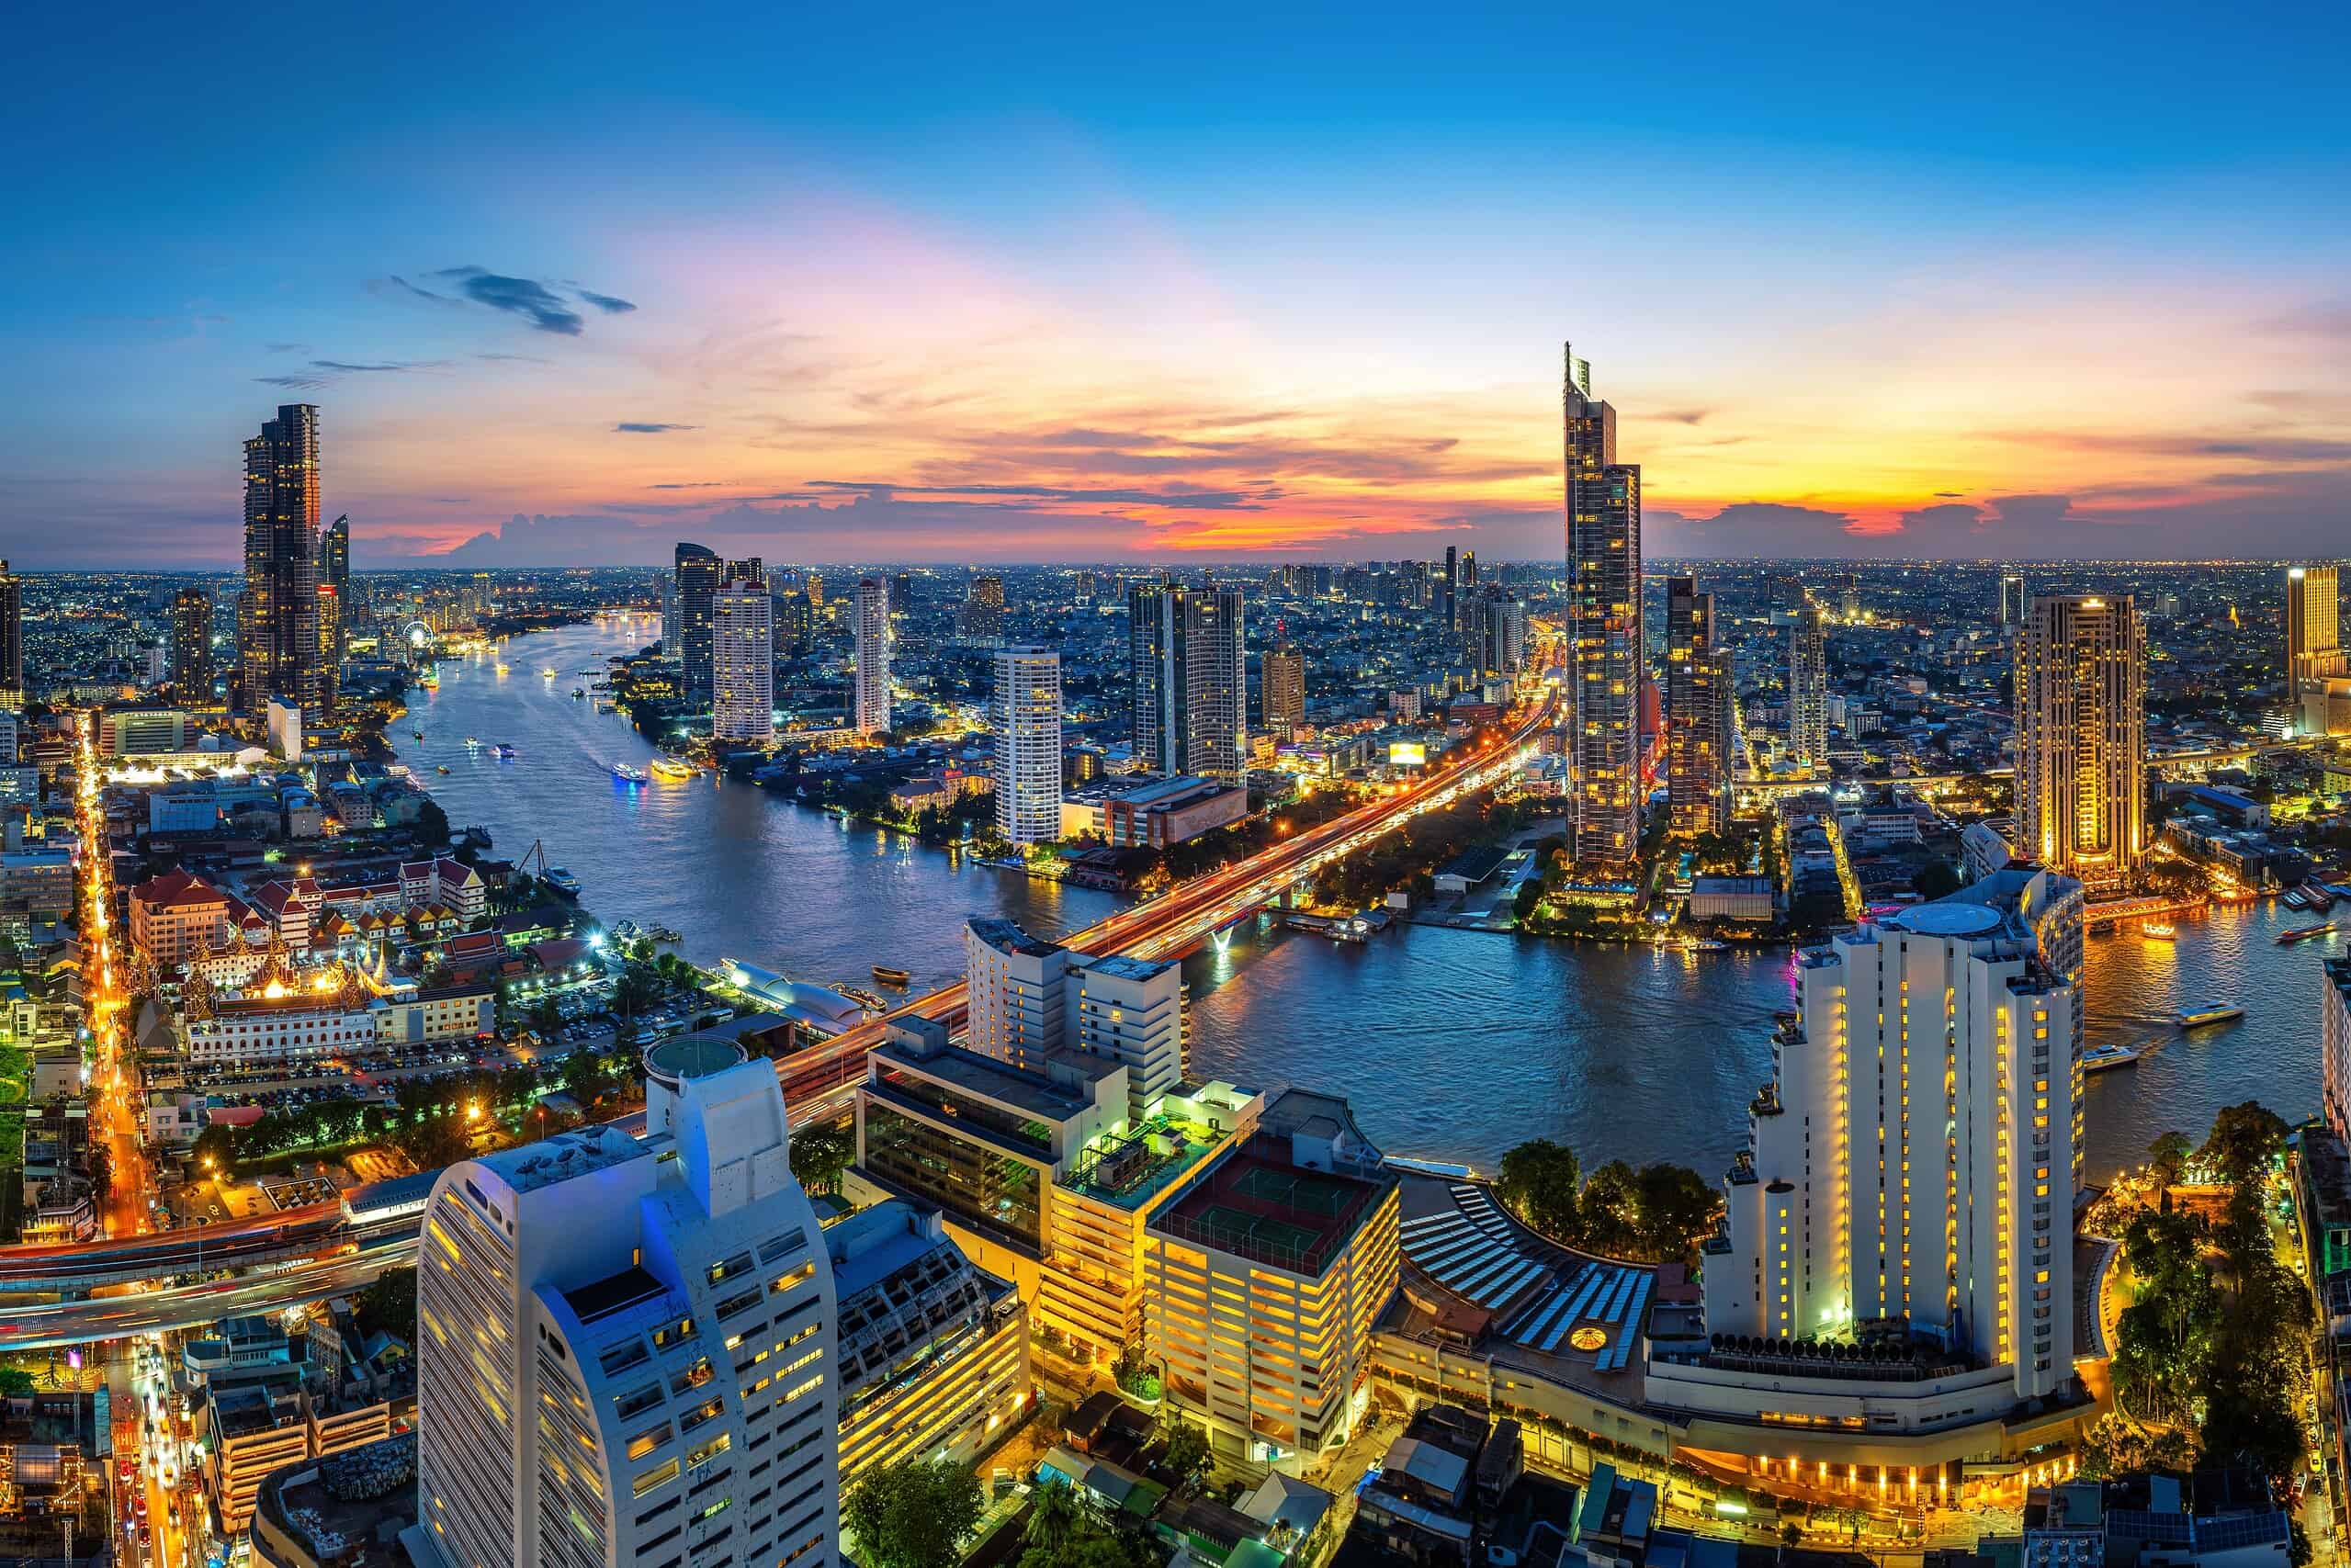
While walking around central Bangkok, it’s easy to miss the damage that prompted IMF and World Bank officials at their annual meeting to consider postponing this week’s event. 

No evidence of the extreme flooding elsewhere in the city, which caused so much damage and loss of life just a week ago, is visible. Life goes on—scooters buzz and trucks barrel down the expressways and narrow streets where vendors hawk exotic foods and trinkets. Bangkok officials did an admirable job cleaning up to prepare for the arrival of some 15,000 attendees, and the area surrounding the convention center is as dry—and secure—as it’s probably ever been. 

Inside the meetings, though, the question was how much more disruption—climate-related or otherwise—the global economy can absorb, and who can afford to recover when the next shock arrives.

At Tuesday’s World Economic Outlook briefing, IMF Chief Economist Silvana Tenreyro described a world economy being pulled in two directions. Conflict in the Middle East has pushed energy prices higher, while investment in artificial intelligence has helped drive growth. The IMF outlook projects global growth of 3.1% this year, but that headline figure masks sharp differences among countries. Energy exporters and countries driving the AI boom are better positioned, she said, than those that must import fuel or have little stake in the massive technology surge.

“The economy has been resilient, but that resilience is reaching its limits,” Tenreyro said at the briefing.

The economy is holding up, in part, because countries and companies have navigated disruptions by rerouting supplies, drawing down inventories, improving efficiency, and finding alternatives. Without those adjustments, the IMF estimates global growth would be closer to 2.5%.

But these measures have limits. Inventories run down. Efficiency gains can only go so far. And another shock—whether geopolitical or climate-related—could arrive before economies have recovered from the last one.

G-24’s Climate and Debt Dilemmas

The Intergovernmental Group of Twenty-Four on International Monetary Affairs and Development, or G-24, which represents emerging-market and developing economies, brought the issue closer to home. Nigeria’s finance minister and G-24 chair, Taiwo Oyedele, cited the flooding in Thailand to argue that climate commitments need to be backed by money, not just promises.

“Our appeal to world leaders is to put their money where their mouth is,” he said in a separate briefing shortly after WEO’s.

For businesses, resilience has a price. Holding extra inventory, diversifying suppliers, and keeping cash on hand can seem like unnecessary costs when markets are stable. But during a disruption, they can keep production moving and prevent higher costs from affecting the business.

Countries face a similar trade-off but lack the same resources. Developing economies need funding for infrastructure, climate preparedness, and basic services, even as debt payments consume a large share of public funds. Oyedele cited estimates that developing countries pay roughly $500 billion more in debt costs than developed economies. His broader point is clear: The countries that need to invest in resilience often face the highest financing costs.

Iyabo Masha, director and head of the Secretariat of the G-24, described the dilemma this way: “Debt is something that restrains growth.” When governments spend so much on creditors, she said, they have less left to invest in their economies.

The AI Factor

Another uncertainty in the IMF’s outlook is that AI investment may boost growth, but its benefits do not necessarily translate into jobs. Oyedele warned that countries with younger populations could see growth alongside rising unemployment if they do not plan carefully. Growth, he said, “has to be job rich; it has to be inclusive.”

That’s a broad definition of resilience—not simply keeping an economy growing, but ensuring people benefit and that governments retain the capacity to respond when circumstances change.

In Bangkok, the discussions have ranged from growth forecasts to debt and climate finance. But the underlying question is who can afford to prepare for the next disruption and who will be left to pay for recovery.

Central Bangkok shows little sign of the recent flooding, but that doesn’t mean the damage elsewhere was any less severe. The same holds for the global economy: A resilient growth forecast doesn’t mean every country is equally prepared for the next shock. The question is how much each can afford to absorb—and what it might have to give up to recover.

Paul Curcio is the editor of Global Finance Magazine. Contact him at paul.curcio@gfmag.com.

Source link

This is where earnings growth is coming from in Q3 – Citadel Securities’ Rubner (MU:NASDAQ)

Financial and Technical Data Analysis Graph Showing Search Findings

MicroStockHub

Micron Technology (MU) and Nvidia (NVDA) alone account for 36% of expected S&P 500 (SP500) earnings growth in the third quarter, according to Scott Rubner, head of Equity and Equity Derivatives Strategy at Citadel Securities.

Consensus entered Q3 reporting looking

Source link

The Caribbean’s Payment Rail Moves to Pilot

CAPSS has entered its pilot phase, bringing real-time local currency payments to 11 Caribbean nations.

This article appears in the October issue of Global Finance Magazine.

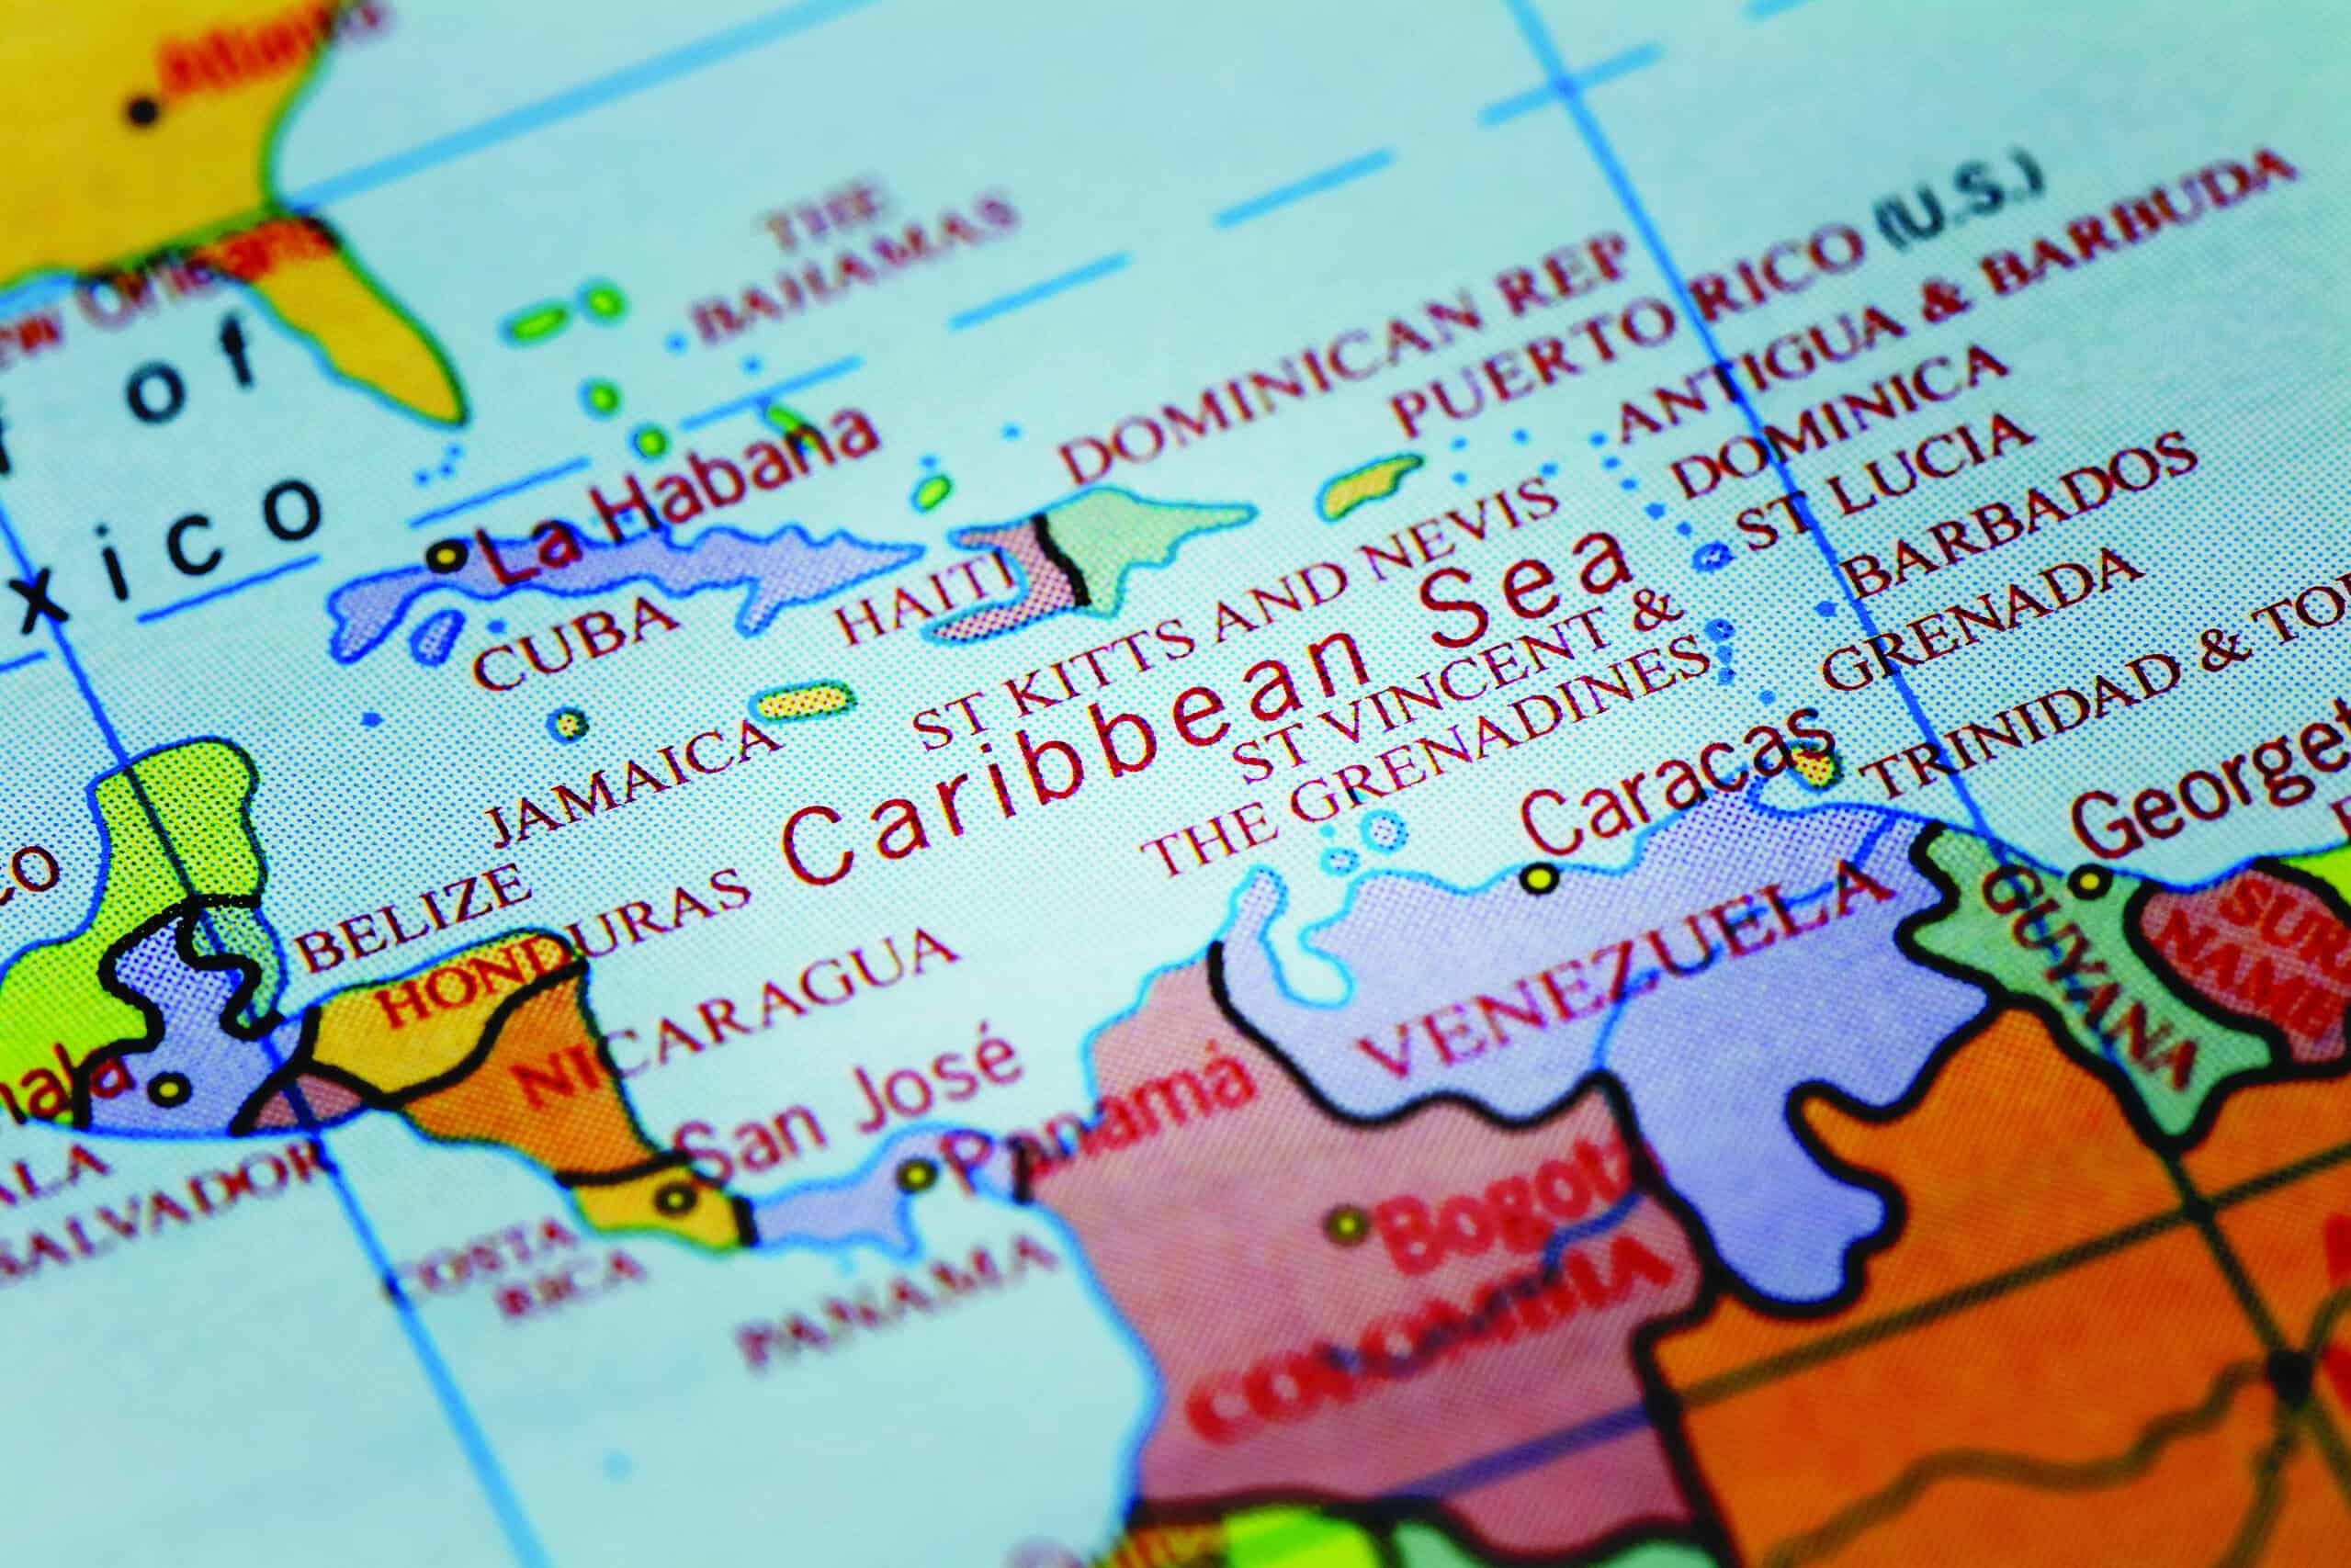
The long-awaited CARICOM Payment and Settlement System (CAPSS), designed to transform cross-border payment settlement across the Caribbean, has entered its pilot phase, putting the region’s vision for real-time payments in local currencies into practice across 11 jurisdictions.

Developed by the region’s central banks in partnership with the African Export-Import Bank (Afreximbank), CAPSS connects national payment systems to enable real-time cross-border payments in local currencies, allowing businesses and consumers to bypass the U.S. dollar as an intermediary.

“While background settlements will still involve U.S. dollars among central banks, day-to-day transactions will use local currencies — a key innovation with broad potential,” said Timothy Antoine, governor of the Eastern Caribbean Central Bank, which serves eight Caribbean countries and territories that share a common currency.

Cutting Costs

The project aims to boost intra-CARICOM trade, with goods exports to regional partners accounting for roughly 8% of the bloc’s total goods exports, according to the IMF.

Settling directly in local currencies cuts foreign exchange conversion costs and makes smaller cross-border transactions worthwhile, which matters most to small- and mid-sized businesses, who pay the highest relative costs for international payments.

“If for instance, I am in Barbados and I want to buy goods from Trinidad and I don’t have the U.S. dollars to make that payment, then it becomes simply wishful thinking. We think that stifles trade,” said Okechukwu Ihejirika, acting chief operating officer at Afreximbank’s Caribbean office.

CAPSS also offers a route around the region’s shrinking correspondent-banking network. Research by the Economist Intelligence Unit in 2024 found that about 40% of correspondent banks had withdrawn from the Caribbean over the previous 15 years.

An IMF working paper published in May, “Mind the Gaps: Caribbean Trade Patterns and the Connectivity Constraint,” found cross-border banking relationships lift CARICOM trade at less than half the global rate.

Modeled On African Payment Rail

The system is modeled on the Pan-African Payment and Settlement System, or PAPSS, launched by Afreximbank and the African Union in 2022. PAPSS provides a framework for real-time cross-border payments in local currencies and now connects banks and payment providers across 16 African countries.

The Caribbean push began in October 2023, when every CARICOM central bank adopted PAPSS as its preferred settlement system. 

A proof of concept took place in February 2025 at the Central Bank of The Bahamas, where a live payment between Barbados and The Bahamas settled in each country’s own currency, with no dollars passing between them. Afreximbank and PAPSS provided a design already running in Africa, while payments software firm Montran Corp. built the connection between the two national systems. Trinidad and Tobago’s central bank took part, and Suriname sent an observer.

Governors expanded the test last November. CARICOM’s central bankers meet again in November, the next point at which the timetable could firm up.

Beyond the pilot, central banks plan to link CAPSS to PAPSS, building a payment bridge between Caribbean and African markets.

Thomas Monteiro is a contributing writer based in Spain.

Source link