Finance Desk

Uber Offers Early Indicator of the AI Effect

As Uber slashes corporate headcount, the cuts hint at how companies could finance an automated future.

When a highly profitable, fast-growing company decides to cut a tenth of its workforce, you must look beyond its formal statements. Uber Technologies’ recent move to run through three rounds of layoffs—cutting 10% of its global corporate team, or about 3,300 people—isn’t standard, defensive cost-cutting.

Instead, it offers a fascinating look at where big corporate money is moving. At the same time these office desks are being cleared, Uber is gearing up to pour up to $10 billion over the next few years in self-driving cars and autonomous vehicle networks. CEO Dara Khosrowshahi said the goal is to make the company “simpler and faster,” but that points to a much bigger trend in boardrooms everywhere: corporate layoffs are starting to look like a funding mechanism for an automated future.

Pinning down a direct link between artificial intelligence and job cuts requires reading between the lines of carefully crafted corporate PR. In its official announcements, Uber has been quiet on this front, explicitly linking only an early 10 percent cut in its customer service department to the embrace of AI. Later rounds in HR, recruiting, and middle management were described as strategic flattening and the removal of organizational layers. Yet broader data shows a trend moving much faster than company memos suggest. According to data from outplacement firm Challenger, Gray & Christmas, AI was cited as a reason for over 100,000 announced layoffs in the US during just the first half of the year—a massive jump compared to previous years.

This tension between streamlining operations and pivoting to new technology highlights a deep shift in how companies are built. Danielle LaFleur, an enterprise automation strategist and partner at TextBernie.me, believes we should view Uber’s layoffs as a sign of things to come for operations-heavy industries, rather than a one-off event. “Uber’s 10% reduction is a leading indicator, not an anomaly,” LaFleur said. “A profitable company does not cut a tenth of its workforce during a growth period to save money. It does so to reallocate resources: shifting investment from a labor model built on human drivers to one built on autonomous infrastructure.”

Reallocating for Autonomy

Moving capital away from old, labor-intensive setups marks a fundamental shift in how technology interacts with business. “Most corporate AI adoption to date has been additive,” LaFleur said. “Firms kept their organizational structures intact and layered AI tools on top. Uber represents the next phase, in which AI alters the firm’s structure itself. Operations-heavy industries should expect similar restructurings as autonomous systems mature.”

But the human side of this shift shows that the impact goes far beyond a smaller headcount. As independent coach Nataliia Rastehaieva pointed out: “AI may not simply remove jobs. It may change roles, responsibilities and expectations much faster than before. That creates uncertainty for the people who leave, but also for those who stay. They need to understand what is changing and what their place in the company will be. I would not treat Uber as proof of what AI will do to every company. But it may be an early example of how technology and management decisions together are reshaping work.”

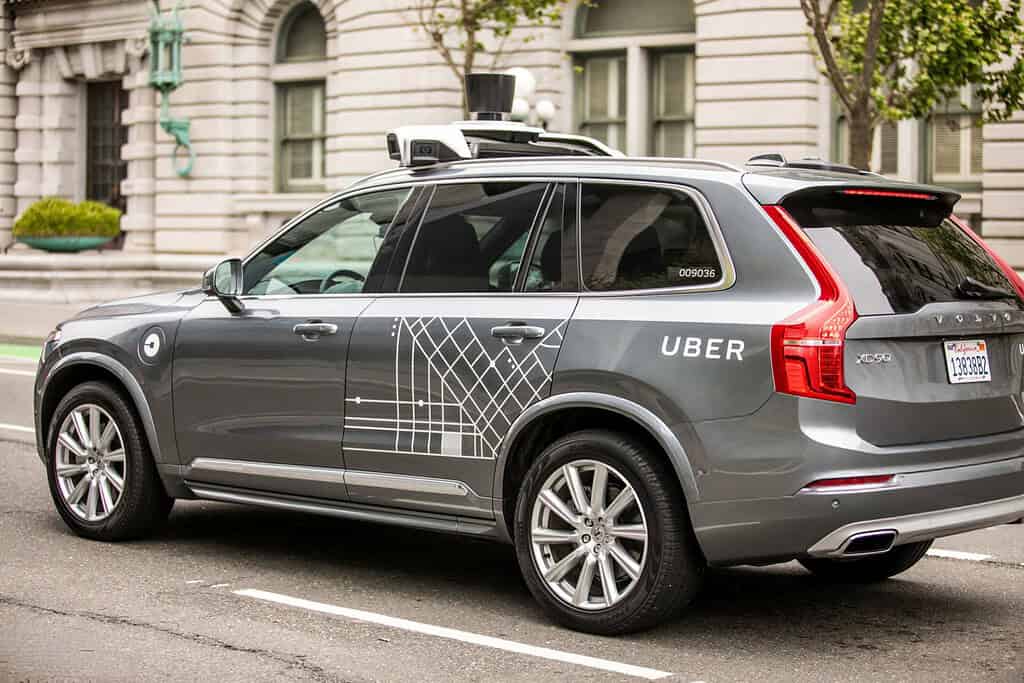
An Uber self-driving test vehicle equipped with sensor equipment navigating a San Francisco street.
An Uber self-driving car in San Francisco.

Serhii Nikolaichuk, a former Uber driver and founder of The Capital Index, offers a closer look at the corporate layers being targeted. “Uber’s cut of about 3,300 jobs, roughly 10% of its workforce, isn’t aimed at drivers,” Nikolaichuk said. “It’s aimed at management: about a fifth of its managers, teams of one or two, and reporting chains more than seven levels deep. Technically, that makes sense. Most coordination work is routing: collect status, compress it into a report, and pass decisions down. That’s exactly what language models and workflow agents now do in seconds.

“The memo (of the company) doesn’t blame AI, but the money tells the story: more than $10 billion committed to autonomous vehicles. Uber already runs robotaxi rides in four U.S. cities, including Austin, [Texas] and has about 20 autonomous-vehicle partners. It even pays some drivers, between rides, to complete data tasks for its AI unit, whose clients include self-driving companies. The workforce is helping train the machines that will compete with it.”

A Leaner Future of Work

This leaves a big question for the rest of corporate America: what does this playbook mean for everyone else? Kyle Elliott, founder of Tech Career Coach and CaffeinatedKyle.com, sees it clearly: “Fewer managers and fewer layers between frontline employees and senior leaders. Companies will look for leaders who can manage larger teams without relying on several levels of management beneath them. AI does often play a supporting role in layoffs. Tools that speed up performance reviews, internal communications, and reporting let one manager oversee more people, which, in theory, makes some management layers easier to cut.”

At the end of the day, Uber’s latest moves carry significant weight for companies of all sizes and across sectors. As AI shifts from tech experiments to everyday infrastructure, the classic corporate setups designed to manage massive human networks will continue to shrink. The layoffs and reshuffling we’re seeing now aren’t just temporary speed bumps—they are early signs that tech and leadership decisions are completely changing the way we work.

Andrea Fiano is editor-at-large at Global Finance Magazine. Contact him at afiano@gfmag.com.

Source link

Neptune projects about $238M of 2027 revenue with about 61% adjusted EBITDA margin as Atlas+ adoption expands (NYSE:NP)

Earnings Call Insights: Neptune Insurance Holdings Inc. (NP) Q3 2026

Management View

  • “The third quarter was another record for Neptune. Revenue grew 34% year-over-year to $59.6 million. Adjusted EBITDA grew 38% to $36.8 million at a 62% margin, an improvement of 147 basis points from a year ago.” (President & Chief

Seeking Alpha’s Disclaimer: This article was automatically generated by an AI tool based on content available on the Seeking Alpha website, and has not been curated or reviewed by humans. Due to inherent limitations in using AI-based tools, the accuracy, completeness, or timeliness of such articles cannot be guaranteed. This article is intended for informational purposes only. Seeking Alpha does not take account of your objectives or your financial situation and does not offer any personalized investment advice. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank.

Source link

Intuitive narrows 2026 procedure growth outlook to 14%-15% amid I&A pricing actions targeting 3%-5% per-procedure reduction (NASDAQ:ISRG)

Earnings Call Insights: Intuitive Surgical (ISRG) Q3 2026

Management View

  • CEO David Rosa said Q3 was “a strong quarter for Intuitive with broad-based adoption across our multiport, single-port and Ion platforms,” adding that “total procedures increased 15%, driven by 14% growth in da Vinci procedures and

Seeking Alpha’s Disclaimer: This article was automatically generated by an AI tool based on content available on the Seeking Alpha website, and has not been curated or reviewed by humans. Due to inherent limitations in using AI-based tools, the accuracy, completeness, or timeliness of such articles cannot be guaranteed. This article is intended for informational purposes only. Seeking Alpha does not take account of your objectives or your financial situation and does not offer any personalized investment advice. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank.

Source link

Why Bank of America’s AML Failure Is a Wall Street Warning

Experts warn Bank of America’s hefty AML fine signals a reckoning for aging banking compliance.

When Bank of America released third-quarter financials on Oct. 14, shareholders took note of a $1.2 billion non-tax-deductible blow to earnings. The anti-money laundering, or AML, and sanctions penalty shaved 17 cents off its per-share net income.

But the fine itself may be the least of the bank’s worries.

Financial crime and AML experts told Global Finance that this penalty was not an outlier but a warning to the rest of the industry.

“If you looked at every bank in detail, you’d find problems,” ThetaRay CEO Brad Levy said in an interview. “It’s kind of like every house — when the inspector comes, there’s something wrong.”

What Happened

The Treasury Department’s Financial Crimes Enforcement Network (FinCEN) addressed the penalty. The segment cited Bank of America’s “failure to mitigate and report priority national security risks, including Chinese Money Laundering Networks and illicit finance along the southwest border.”

The fine is the third-largest in the department’s history, behind a roughly $4 billion settlement with Binance in 2023 and an approximately $3 billion settlement with TD Bank in 2024.

This particular cost includes $750 million that goes to the Office of the Comptroller of the Currency — the largest fine that regulator has ever imposed— plus $11.6 million to the Treasury’s Office of Foreign Assets Control over apparent violations of sanctions programs covering Iran, Russia, narcotics and global terrorism.

A Bank of America spokesperson issued the following statement to Global Finance: “Financial crime compliance is serious, and we are responsible for getting it right. We worked with regulators to reach these penalty resolutions stemming from violations cited in the previously reported 2024 OCC Consent Order and FinCEN’s investigation. We have invested billions of dollars in technology and dedicated thousands of employees to combat financial crime, and our team is far along with and committed to completing the work required to address the issues raised by our regulators.”

Fallout Extends Beyond Government Agencies

For Nikhil Raghuveera, CEO of Predicate, a startup that uses blockchain technology for AML enforcement, the real government-inflicted damage is not to Bank of America’s coffers but to its goodwill.

“The bank faces business and reputational damage with counterparties,” Raghuveera said. Partner institutions, clearing banks, and corporate clients typically tighten their own risk thresholds to protect themselves from secondary liability and run their own risk assessments. And a Bank Secrecy Act violation feeds directly into them, he explained.

“A large bank doesn’t lose its ability to operate, but it does face greater scrutiny and the potential loss of business opportunities,” Raghuveera added. “The regulator now sees the bank as unable to fix things itself. As a result, every new product or expansion gets reviewed through that lens.”

Regulatory Trust Broken

The hefty fine grabbed headlines, but according to Will Lawrence, CEO of San Francisco-based AML software maker Bretton AI Inc., the money matters less than what the bank has lost in regulatory trust.

Will Lawrence,
Bretton AI
Will Lawrence,
Bretton AI

“For a large bank, even a significant financial penalty may be manageable,” Lawrence said in an email. “What’s much harder is operating once regulators lose confidence in the institution’s ability to manage risk.”

That can mean independent monitoring, more board scrutiny and limits on growth.

“Even without formal restrictions on growth or acquisitions, unresolved compliance issues can complicate a bank’s expansion plans,” he said. “The financial penalty may be immediate, but remediation can take years.”

Big-name banks are also vulnerable if their methods for flagging suspicious activity remain outdated.

For example, when a typical analyst pulls data from different systems, reconstructs transactions, and documents the findings, that approach often falls short against sophisticated laundering networks, Lawrence explained.

“These are not necessarily risks you can understand by looking at one transaction or one customer in isolation,” he said. “You need to connect activity across accounts, counterparties and payment channels to identify broader patterns.”

Large penalties are rarely a one-time blip, Raghuveera said. “They tend to reflect patterns: transaction monitoring that’s poorly calibrated, SARs filed late or not at all, watchlists that aren’t kept current, and compliance teams lacking the staff, tools or authority to escalate.”

24/7 Reality Check

For Lawrence, true accountability raises certain questions: Who knew about the risks? Who had the authority to address them? Was appropriate action taken?

“A bank can have sophisticated monitoring systems, but if serious issues aren’t escalated or leadership doesn’t respond, the program isn’t working,” he added.

Also, Lawrence said, a bank can’t spend its way out of the problem. Regulators want evidence that changes are working, not just new policies or software.

“A bank can hire more analysts, purchase new technology, and rewrite its policies without fundamentally improving its ability to identify financial crime,” Lawrence said. Banks have also long tracked activity counts, such as the number of alerts reviewed or cases closed. “Those numbers tell you something about workload, but not necessarily whether you’re managing risk effectively.”

Levy, who spent nearly 20 years at Goldman Sachs before joining ThetaRay, expressed a similar sentiment. To put it plainly, legacy technology hasn’t kept pace.

“Most of these systems and processes are 10 to 30 years old,” he said, stressing the need for serious internal audits to accommodate the 24/7 banking world.

“Ten years ago, you could get away with it,” he said. “In the next five, you actually can’t… the speed-up in technology is going to be breathtaking.”

Anthony Noto covers corporate finance and private credit. Contact him at anoto@gfmag.com

Source link

Global Salon: Building the Rails for a $3.5 Trillion Empire

Apex Group’s Peter Hughes on AI hype, tokenization, private credit and what Jeff Bezos got wrong.

Peter Hughes founded Apex Group Ltd. in Bermuda in 2003. Today, it manages more than $3.5 trillion in assets across 52 countries, with 100-plus offices, 13,000 employees, and 90 regulatory licenses—growth built on more than 50 acquisitions over eight years and a bet Hughes made roughly five years ago that traditional finance and decentralized finance, or DeFi, were headed for convergence, not collision.

In this conversation with Global Finance, Hughes—who spent time at KPMG and Hemisphere Management before founding Apex—traces that bet from BlackRock Inc.’s decision to add bitcoin to its balance sheet to Apex’s enabling the development of the compliance-focused Layer 2 blockchain initiative, T-Rex. He pushes back on Jeff Bezos’s prediction of an artificial intelligence-driven labor shortage, defends private credit against claims that it’s a broken asset class, and argues that traditional exchanges and crypto-native platforms are racing toward the same end state.

Global Finance: Was there a critical moment or aha moment that sparked a major change in your firm?

Peter Hughes: Absolutely. Bridging traditional finance and DeFi has been my focus for five years. Before that, we serviced crypto funds investing in bitcoin, working strictly with regulated partners to manage risk. I wasn’t sure if crypto would go mainstream, but seeing BlackRock put bitcoin on its balance sheet five years ago proved it was here to stay. That was the turning point.

We later ran a project with a client, lowering a fund’s subscription minimum in Luxembourg from 1 million Swiss francs to 1,000 so more people could access it. That was great, but our real value proposition lay in our scale—we operate across 50 countries under 35 regulators.

So you take something that’s high risk, like crypto, and then you say, “Well, actually, if it’s regulated and you’ve got clean AML around it, it’s a digital asset, and then it becomes accessible for everyone.” From there, I focused on building the distribution rails. We are now approved in 20 jurisdictions for on-chain transfer agency, enabling seamless settlement of digital securities. Our target by next year is a platform giving funds access to 50 new distribution channels across wealth, retirement, retail, and crypto-native channels. As tokenized money market funds transition to a 24/7/365 operational model, the broader asset world will inevitably follow. Building these locked-in distribution rails today ensures a highly valuable position for the future.

GF: Has blockchain changed the way your business operates, and do you see it likely becoming more integral in the future?

Hughes: Blockchain is the end state for how everything ends up; crypto is just a small piece of what we service. We focus on the regulated side—digital assets backed by clean AML.

My view is that everything will move on-chain, creating cheaper fund structures and frictionless finance. But that only works in a regulated environment. We favor public, permissioned chains because you know where the money is coming from, where it’s going, and that it’s clean. We supported the launch of the Layer 2 compliance initiative, T-Rex, which is operated by an independent foundation, to validate that every transaction moving across chains is fully verified.

I’m looking toward a world where custody, administration, transfer agency, and distribution all sit on-chain and interlink seamlessly—yielding faster speeds, higher volumes, and lower costs. So we’re all-in on blockchain. Crypto is part of it, but the core focus is digital assets: regulated securities that trade 24/7/365 like crypto, but with the institutional guardrails built in.

GF: Do you expect any relaxation for crypto in China?

Hughes: It’s difficult to tell, but stablecoins will eventually replace fiat on corporate balance sheets because they function as both payment tools and yield-bearing instruments. Their growth is currently limited by regulation—like MiCA in Europe and the Genius Act and Clarity Act in the US—designed to protect traditional bank deposits. But tokenized money market funds already offer the same yield without the payment functionality. It’s only a matter of time before yield- bearing stablecoins gain widespread adoption.

GF: Will Apex pursue any more acquisitions in the near future?

Hughes: We don’t need any new acquisitions. I bought 50 businesses over an eight-year period, each designed to add a new technology, open a new geography, or add a new product set. Every one is handpicked to complement what’s already there, so you can cross-sell both ways. People look at that from the out- side and say we just buy businesses—but for the last three years, it’s really been distribution businesses and technology businesses, aimed at building the technology rails to be the distribution leg for asset managers globally. That’s the direction I’ve always been moving in not just being good infrastructure and doing a good job for clients like other asset servicers but layering in and distributing their products to help them get bigger. That’s when you go from being a vendor to a real partner—when you’re shifting their P&L upwards. In September, I announced we’ve brought in a head of product from Revolut, because I want us building products and releasing them in eight-week sprints. If you’re not moving that fast in a tech evolution like this, you get left behind. So now it’s about building the technology of the future ourselves, rather than buying it in. We’re already servicing tokenized money market funds that run 24/7/365, fully on our own tech stack—and we want to keep enhancing that.

GF: Will there be fewer workers in the future due to AI or tech innovation?

Hughes: I hosted a conference for our clients in London and told them people are running an AI race that ends in a trap—you embed AI across everything, decide you don’t need people any- more, and suddenly your AI costs go up tenfold. That kills businesses. I’m not rushing into that trap. I’m adding AI thoughtfully, so data flows seamlessly end to end instead of being pushed and pulled by people, and I’m using it to build incremental products that add value for clients. I don’t think we’ll have fewer people, and I don’t think our salary costs go down—I think the same people will service more revenue. What it does change is who we hire. Instead of people doing manual work in Excel, we can bring in people who add real thought leadership, PhDs who help us think about how to value funds for the future. It doesn’t get cheaper for us. We just get better talent.

GF: Jeff Bezos insists AI will cause a labor shortage.

Hughes: I don’t see how it leads to a shortage. In places like India, where 18 million people enter the workforce every month, it’s exactly those keying-into-dashboards, keying-into-keyboards jobs that a lot of that workforce would traditionally have done—and a lot of people there see AI as a real threat because of it. So no, I don’t agree. When the manual layer goes, even my son—he’s at university in the UK—asks me, well, what job is he going to do when he leaves? He’s not going to start as an accountant, not going to start as a lawyer, because the bottom rungs of the ladder are being taken out. Firms are only hiring the top 10% into those entry positions now, whether that’s investment banking or what- ever else. So I don’t see it. Bezos is obviously very successful, but I don’t see how he’s right on this.

GF: What’s your view of the turbulent private credit space?

Hughes: The turbulence comes from growth—the volume of investor capital coming in but coming into a format that doesn’t work: a mismatch in liquidity. If you want to get out, you can’t, and that’s a structuring problem, not a problem with underly- ing returns. I still think private credit is a great asset class—10% annualized returns with low volatility. The friction came from structuring it into interval funds, which isn’t the right structure for private credit. When people raised concerns, the response was “wait for the next valuation, in four months you’ll see there’s no problem”—but the technology exists for weekly or daily valuation. If that information had come through faster, people wouldn’t have panicked. Instead, redemptions piled up and it became a vicious circle. The asset class itself is as strong as it always was—it was the structure, and the slow information flow, that caused the problem. And there’s no real slow down here: Revolut recently announced that Ares and Apollo are making their private credit funds available on the platform, with a €1 minimum investment. That’s not just a headline—it shows both the confi- dence in the asset class and what’s now possible in terms of democratizing it.

GF: Can we say that there is also an element of democratization of finance in what you do?

Hughes: That’s been a theme for the last three or four years — democratization, giving more access. But I think the way access happens will get more appropriate and more sophisticated going forward. People talk about interval funds in the U.S. as democratizing private markets, but for me that’s the wrong structure — it’s exactly why you saw noise around private credit funds: they were structured for retail, but there was a mismatch in liquidity. I think democratization gets broader and more sophisticated from here. It started with high-net-worth and wealth; as regulators get more comfortable, it’ll extend into wealth, retirement and retail. Think about why a private equity fund is high risk: it’s illiquid, you’re locked in for seven to ten years, it has a big ticket size, and it’s valued infrequently. Take away those three barriers and it trades like a normal equity, with a normal equity’s risk profile — which means it should be accessible to retail. Regulators are starting to understand that, though it’ll take time.

Anthony Noto covers corporate finance and private credit. Contact him at anoto@gfmag.com

Source link

U.S. to allow ‘dark fleet’ tankers to ship oil legally

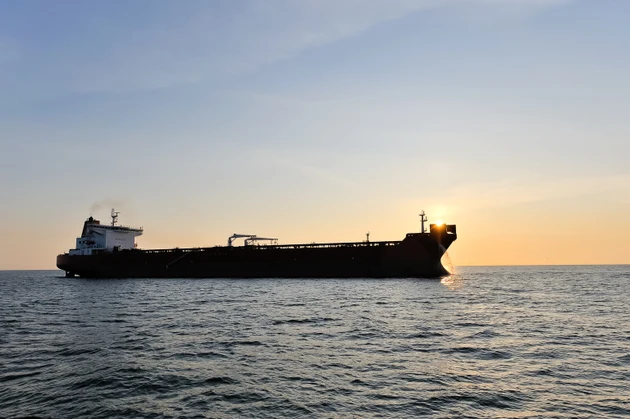
Crude oil tanker in the sea at sunset.

Alexey Bakharev

The U.S. government will authorize the sale of sanctioned oil tankers, allowing these vessels to ship crude legally to help rein in soaring shipping costs, Energy Secretary Chris Wright said during a Citadel Securities event on Monday.

He noted that “a

Source link