Finance Desk

Global Economy Struggles to Achieve Balance in Divided Times

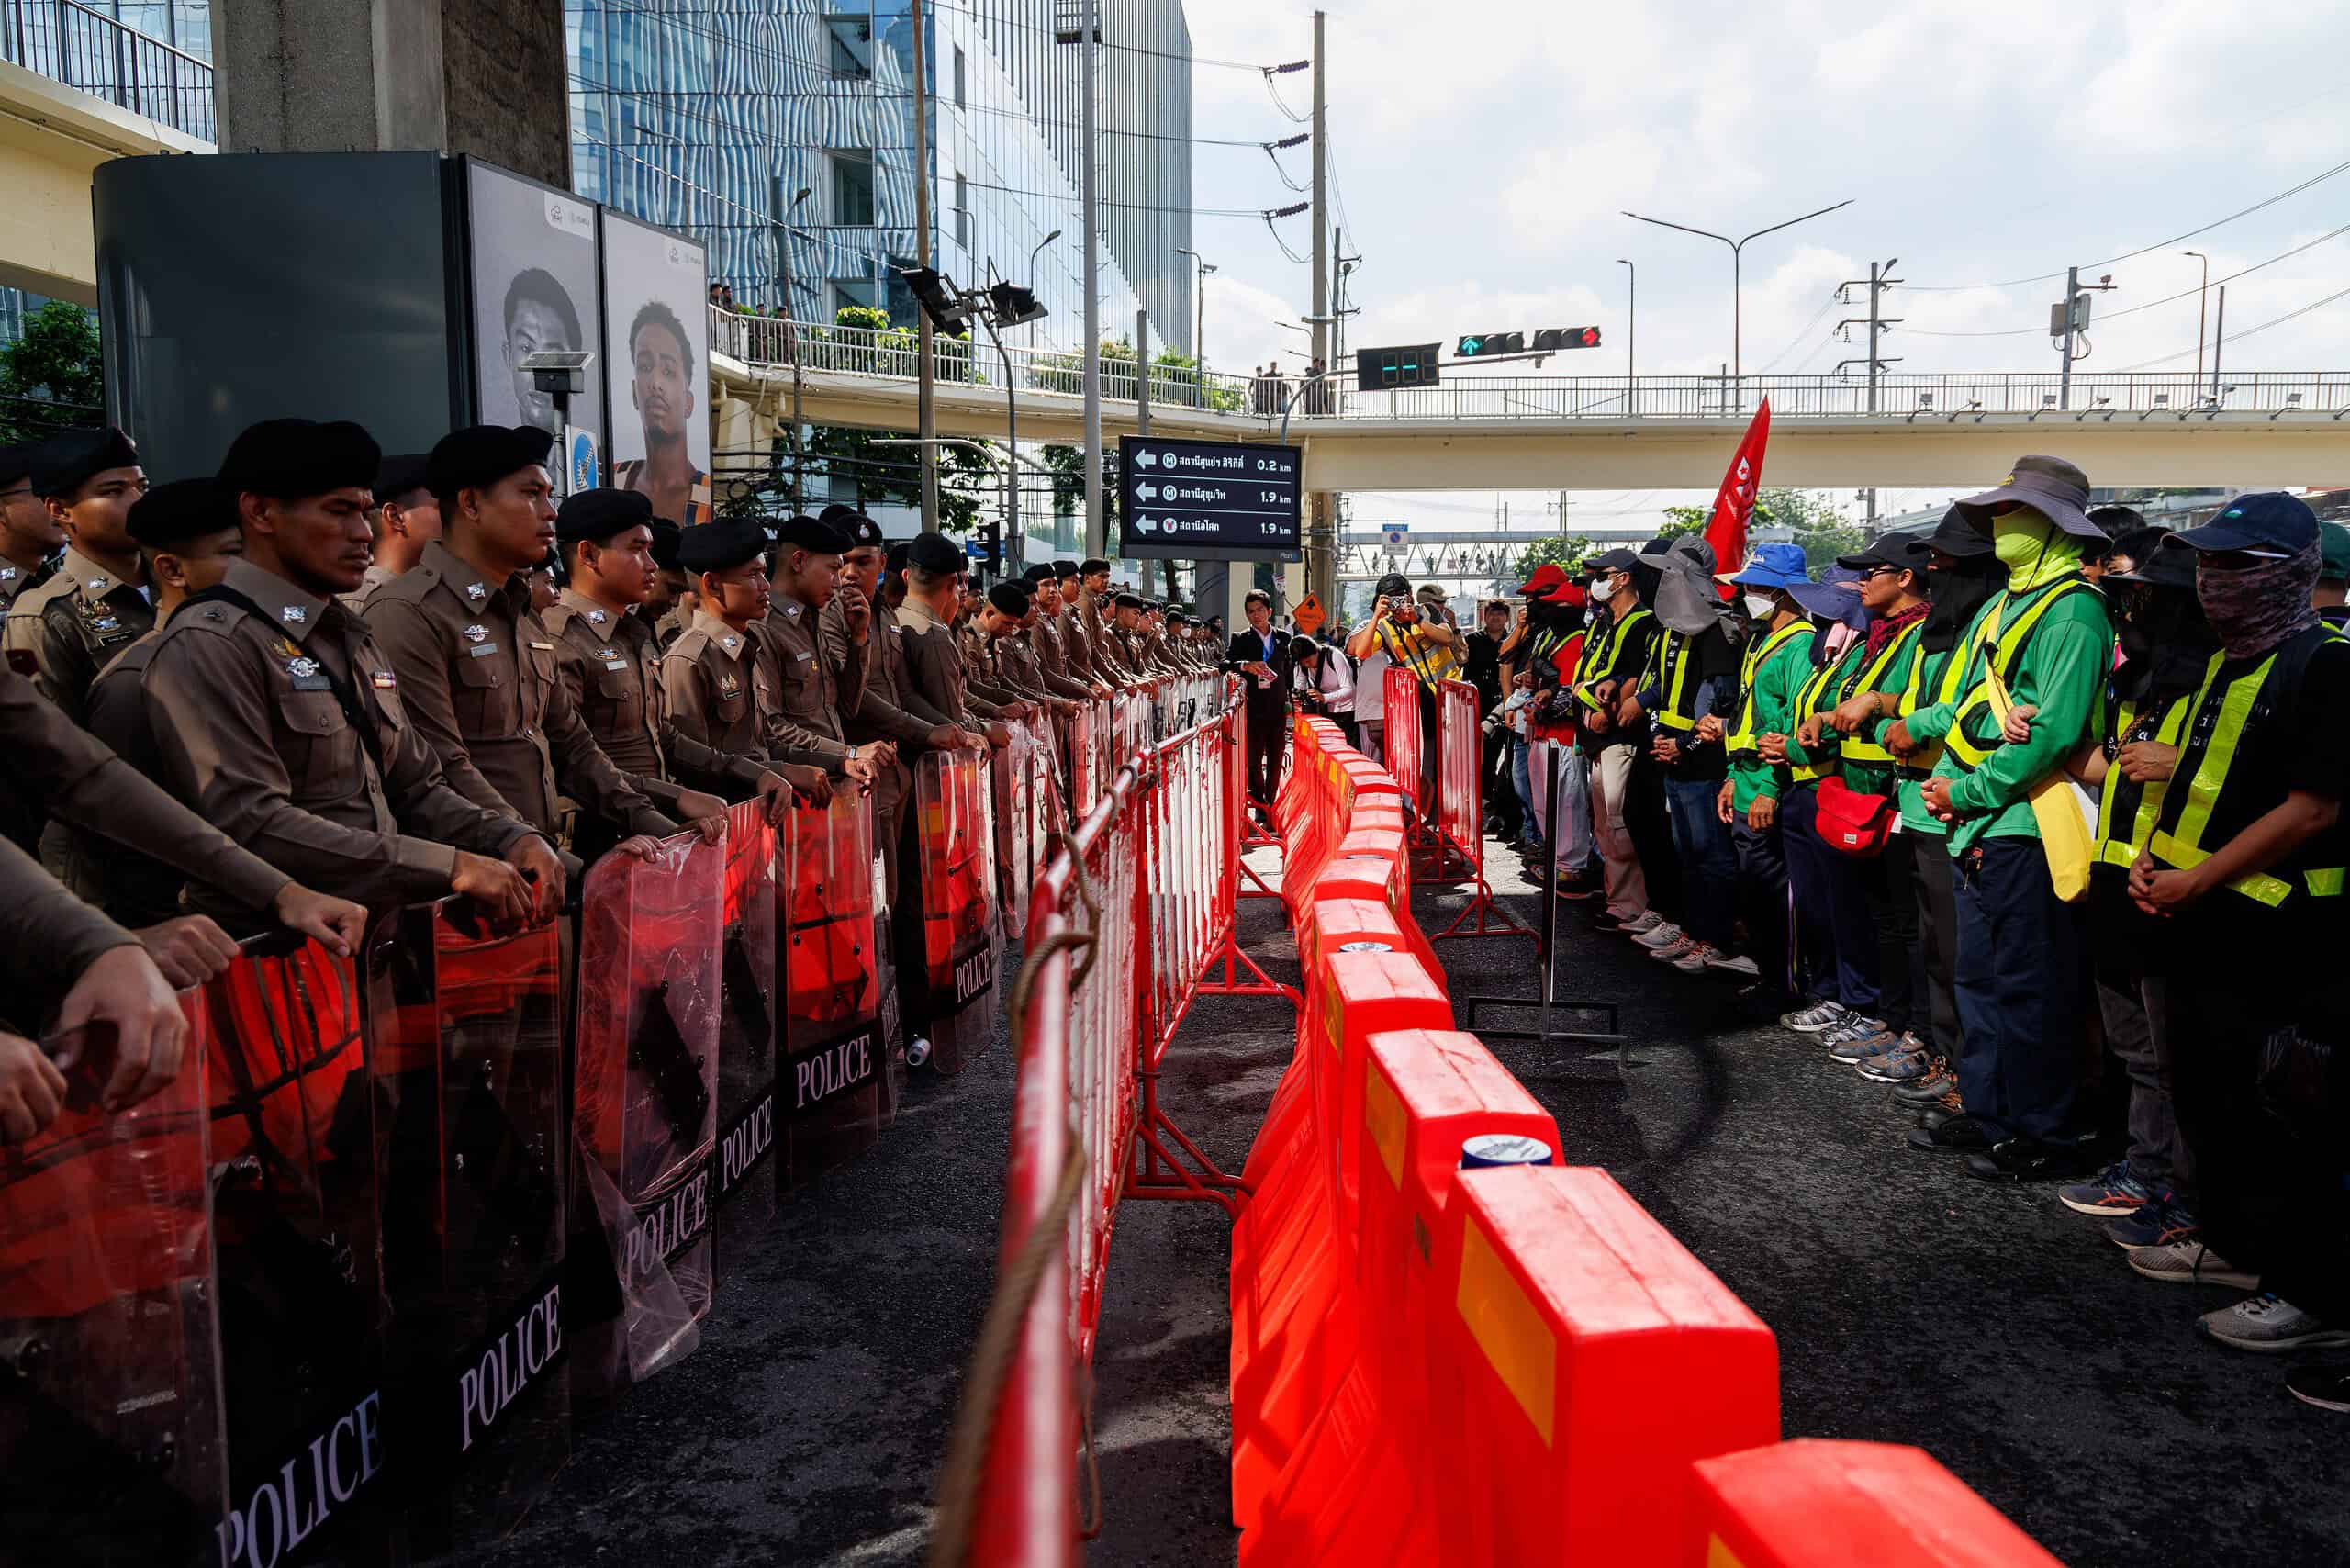
As leaders gathered in Bangkok, discussions highlighted the fractures between economic winners and losers.

The global economy appears to be on a fragile foundation, and the finance ministers of Argentina, Greece, Nigeria, and Thailand agree that all economies should get their houses in order.

“Ideally, when you put your fiscal house in order, it shouldn’t be because of experience,” said Kyriakos Pierrakakis, the Minister of Economy and Finance for Greece and President of the Eurogroup, during a panel discussion that took place at the annual International Monetary Fund (IMF) and World Bank meetings in Bangkok. “It should be because of inspiration.”

Although the IMF projects global economic growth at 3.1% throughout 2026, its composition has changed.

The global economy is increasingly split between a handful of nations with AI-driven economies and those without. The IMF has upgraded AI-driven economies while it downgraded many fuel-importing nations and those affected by war. 

However, AI may be a curse and a blessing.

“The global economy’s dependence on AI investment enthusiasm creates a vulnerability, with risks of disappointment cycles, as per Amara’s Law, and the potential loss of human control over AI systems,” said fellow panelist Kristalina Georgieva, IMF Managing Director.

Exacerbating the situation are growing excessive export-import imbalances. Developing countries struggle to compete with export-oriented countries that have built their manufacturing base over decades. At the same time, developing economies struggle to compete for capital against an economy that takes in capital for productive use but leaves little for the rest of the world.

“The biggest source of imbalance comes from the two largest economies, China and the United States: China not having enough domestic consumption, exporting a lot, and the U.S. the opposite, not saving enough, having a high level of debt and deficit,” she said. 

Achieving Resiliency

It’s best for a country to put its fiscal house in order during periods of economic calm, but human nature tends to act only amid a crisis, said Georgieva. “Nonetheless, we have excellent examples of countries that have brought back fiscal discipline. They have taken the reforms, structural reforms that promote growth.”

The formula for building a resilient economy is discipline, transparency, and consistency, which, according to Olayemi Cardoso, Governor of the Central Bank of Nigeria, build credibility, said Cardoso, who spoke on the panel.

To address a persistent currency crisis and the loss of investor confidence, Nigeria eliminated its fuel subsidy in 2023 and, in June 2024, implemented multiple foreign exchange rates.

“These should have been done a long time ago, but they were not done,” he said.

The central bank also enacted an aggressive 800-basis-point (bp) increase in 2024, including a single 400-bp increase. As a result, the central bank brought inflation down by about 20 percentage points, to about 15%, and raised foreign reserves to their highest level in 18 years.

“Painful though they were, it brought back credibility because we were consistent in saying certain things and doing them,” said Cardoso.

In Argentina, the government eliminated its fiscal deficit, which was 5% of GDP, by cutting spending by 30% and growing the economy for the third consecutive year through increased exports. These measures helped bring inflation down to approximately 30% today from 211% in 2023.

“We have a fiscal surplus, a commercial surplus, and a current account surplus,” said panelist Luis Caputo, Argentina’s Minister of Economy. “The way we will continue in the following years will be by fulfilling our goal of reducing the weight of the state in the economy.”

Thailand aims to maintain macroeconomic stability amid an energy shock and a few years of supply-chain fragmentation. Even as part of the AI value chain, it has kept sovereign bond yields low. 

“Our government 10-year yield is around 2.3%, so much lower than the U.S. and Europe, thanks to fiscal discipline,” said Ekniti Nitithanprapas, Thailand’s Deputy Prime Minister and Finance Minister.

The Thai government has also made structural changes to turn these economic shocks into opportunities for low-income small and mid-sized enterprises by helping them adapt to current shocks and prepare for future ones.

It also expects to work more closely with its ASEAN partners to expand trade and investment opportunities to establish a resilient economy.

“For example, 22% of our trade is with ASEAN countries compared to 60% for the E.U.,” he said. “So, we could do more trade together.”

In Europe, the EU is working to close gaps in its pan-European reforms, which each member state must implement.

“Fragmentation in Europe is a strategic tax,” said Greece’s Pierrakakis. “The IMF has made a calculation that the barriers that exist in services or in manufacturing are equivalent to having a 40%-44% tariff for manufacturing.”

Shocks Happen

Even if countries can build a resilient economy, Argentina’s Caputo was skeptical that it would withstand future shocks.

“It looks like these shocks are going to take longer than anyone of us would have anticipated or hoped,” he said. “If that is the case, resilience by definition will have to last longer. And we don’t want to rely that much on that because resilience is there until it is not anymore.”

Caputo also noted that the whole world wouldn’t need to collapse to create a need for resilience. “Just one important country getting into trouble could probably generate systemic risk and affect us all.”

When questioned about France’s current economic distress, Greece’s Pierrakakis responded, “Well, I would say first we’re mindful, but we’re not alert. And we’re not alert in the sense that we know the fundamentals are there and they’re strong. If there’s one key word about Europe, it’s resilience.”

Rob Daly covers the economy and fintech. He can be reached at rdaly@gfmag.com

Source link

The S&P 500 had its largest ever put volume day on Friday (SP500:)

Oct 19, 2026, 2:40 PM ETS&P 500 Index (SP500), , , , , , , , , , , , By: Monica L. Correa, SA News Editor
stock exchange graph background

primeimages/iStock via Getty Images

The S&P 500 (SP500) recorded its largest-ever single-day put options trading volume by dollar notional value last Friday.

The index reached an estimated $3.3T-$3.4T, according to market data.

The surge represented roughly a 330% increase above the 2024 average, with approximately 4.1M

Source link

FX weekly: Dollar weakens against major peers (DXY:)

The dollar index (DXY), which measures the greenback against a basket of major currencies, was last up 0.10% at $101.93 and remains up over 3.8% for the year to date.

Dollar weekly moves and key drivers:

Over the past week, the

Source link

Standard Bank’s Rajesh Ramsundhar on Africa’s Growth in Payments and Trade

Produced in partnership with Standard Bank, this video features Rajesh Ramsundhar, Head of Investor Services & Financial Institutions, Corporate and Investment Banking at Standard Bank, speaking with Global Finance at Sibos.

Rajesh Ramsundhar, Head of Investor Services & Financial Institutions, Corporate and Investment Banking at Standard Bank, speaks with Global Finance at Sibos. Content produced in partnership with Standard Bank.

Ramsundhar explains why Standard Bank is firmly bullish on Africa’s long-term growth runway; how payments and trade sit as the bank’s core transaction banking priorities; and how its technology agenda — building on the bank’s legacy of innovation, deploying technology to enter new markets, and applying data and AI to sharpen efficiency and client service — is positioning the bank for what comes next.

Source link

East Africa Moves to Create Payments Market

Fast-track settlement is making East African payments easier—and a new strategy emerges.

This article appears in the October 2026 issue of Global Finance Magazine.

East Africa is beginning to transform the national payment systems used by millions of businesses and consumers into infrastructure for a more integrated regional market. Rather than building an entirely new platform, the emerging strategy is to connect existing systems, enabling money to move between countries more quickly and with less friction.

Rwanda and Tanzania are at the forefront of that effort, working to connect Tanzania’s Instant Payment System (TIPS) with Rwanda’s National Payment Switch (RSwitch) to create an instant-payment corridor under the Cross-Border Payment System Masterplan of the East African Community (EAC).

The work is moving beyond policy discussions into the technical, operational, and regulatory arrangements required to make the system function. Its significance, however, extends beyond faster remittances. If national payment systems become interoperable, businesses could pay suppliers, receive payments from customers, and settle commercial transactions across borders more easily than under traditional arrangements.

Small and midsize enterprises, banks, fintech companies, and mobile-money operators could all benefit if regional payments begin to match the speed and convenience of domestic transactions.

This Rwanda-Tanzania initiative offers the most immediate test of the concept, but it is not the only example of East Africa’s emerging payments architecture. Kenya’s Pesalink, the country’s instant-payment network, connected to the Pan-African Payment and Settlement System (PAPSS) in February. The partnership enables instant, round-the-clock payments from PAPSS participants to banks and mobile-money operators on the Pesalink network in Kenya, with transactions settled in local currencies.

Those two developments illustrate different routes toward the same objective. Rwanda and Tanzania are connecting their national instant payment systems directly, while Kenya is linking its domestic infrastructure to a wider continental network. Together, they suggest that African payments integration may depend less on building a single system than on making existing systems work together.

EAC’s Regional Masterplan

A broader regional effort is also moving into implementation. On August 24, the EAC announced the establishment of three technical working groups to support implementation of its Masterplan. The Masterplan is “anchored on four key pillars”: governance and regulation, infrastructure, inclusivity, and capacity building. It includes 20 strategic initiatives to strengthen cross-border payment systems.

Robert Omotunde,
MDU Capital
Robert Omotunde,
MDU Capital

Total trade for members of the EAC in 2025 is reported at $156.6 billion, including $19.3 billion among partner states, underscoring the system’s commercial implications. As goods and services move more freely across the region, the financial infrastructure supporting those transactions will also need to become easier to use.

“East Africa’s push for interoperable payments could fundamentally change the economics of regional trade,” said Robert Omotunde, executive director and chief investment officer of Lagos-based asset management and advisory firm MDU Capital. “The significance goes beyond making cross-border transactions faster or cheaper; it is about creating the financial infrastructure through which African businesses can trade more seamlessly across borders.”

As the African Continental Free Trade Area expands markets for cross-border businesses and increases demand for payment systems that support that commerce, opportunities could eventually extend beyond the EAC. Faster settlement, lower transaction costs, and greater use of local currencies could reduce some of the financial friction that still accompanies regional trade. While East Africa is beginning to connect payment systems already embedded in its banks, mobile-money networks, and the wider financial system, the region faces the challenge of ensuring those connections operate reliably across different regulatory and monetary environments.

Vincent Nwanma is a contributing writer based in Nigeria.

Source link

China GDP growth picks up to 4.5% from 3-year low (FXI:NYSEARCA)

Oct 18, 2026, 11:03 PM ETiShares China Large-Cap ETF (FXI), , , , , , , , , , , , , , , By: Gaurav Batavia, SA News Editor

China’s economy grew 4.5% year-on-year in Q3 2026, up from Q2’s three-year low of 4.3% and above market expectations of 4.4%. Growth was supported by recent policy loosening, strong exports, but domestic consumption and investment remain sluggish amid a prolonged downturn in the property market and

Source link