pile

Chelsea beat Man United as Martinez sent off to pile pressure on Carrick | Football

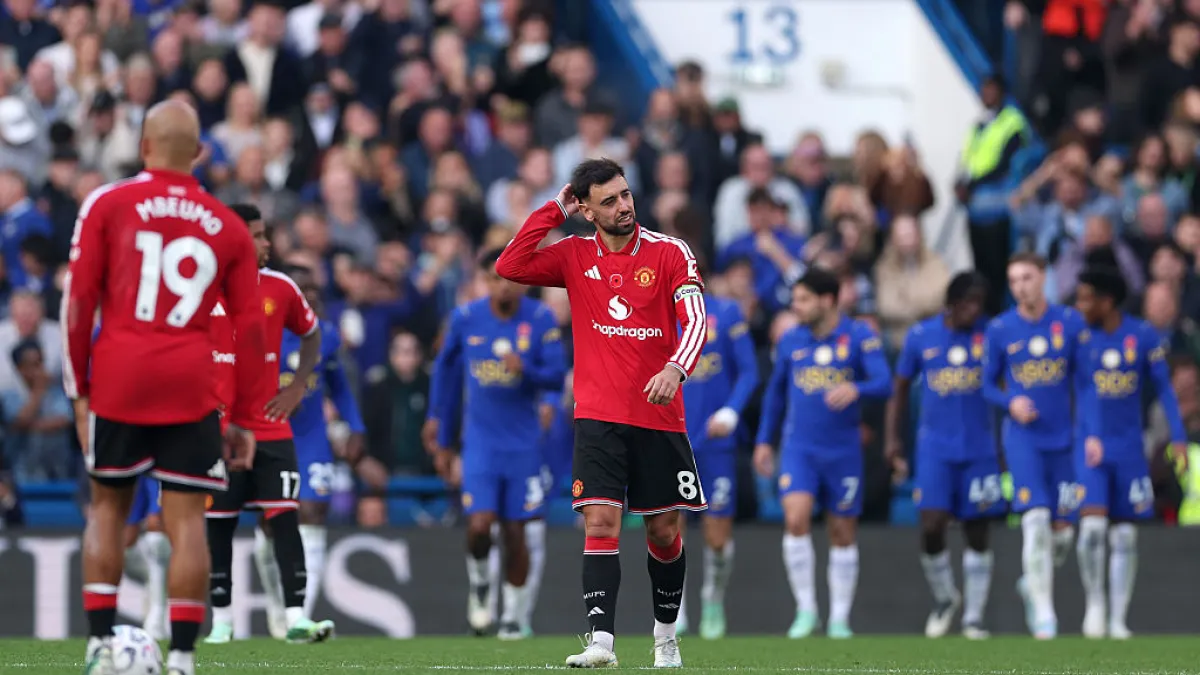
Michael Carrick’s stay of execution as Manchester United boss may not last long after his team imploded in a 2-0 Premier League loss at Chelsea.

The visitors wasted a string of chances to take the lead at Stamford Bridge on Saturday before Morgan Rogers waltzed through the heart of the United defence to open the scoring on 50 minutes.

Recommended Stories

list of 4 itemsend of list

Lisandro Martinez then ruined any chance of a revival from Carrick’s men with two quickfire yellow cards, the second of which also conceded a penalty converted by Cole Palmer.

Winless in nine games, their defeat leaves the 20-time English champions still just one point above the relegation zone and in danger of ending the weekend in the bottom three.

Many expected Carrick to be axed following last weekend’s 3-0 home defeat to Bournemouth.

The former United midfielder was instead given the chance to turn his side’s fortunes around and will lament a lack of ruthlessness during the first half.

Carrick recalled captain Bruno Fernandes after he was left out last weekend in the wake of criticising his manager’s tactics during the 4-1 thrashing at Como in the Champions League.

Fernandes should have marked his return with the opener when he blazed over from Bryan Mbeumo’s inviting cross.

The roles were reversed when Mbeumo could not stretch to meet Fernandes’s delivery at the back post before Amad Diallo was twice denied by Chelsea’s stand-in goalkeeper Mike Penders.

United did finally get the ball in the net when Matheus Cunha turned in Harry Maguire’s header from a corner, but the Brazilian had strayed just offside.

Carrick could not hide his frustration in a half-time interview with broadcasters and his mood soured further with a disastrous start to the second period.

Chelsea’s Rogers credits Carrick for revitalising his career during a spell together at Middlesbrough, but dealt a potentially decisive blow to his former boss.

The England international collected the ball inside the centre circle but was allowed to drive directly towards the United goal before dinking the ball over Senne Lammens.

Martinez also spoke out publicly in recent weeks to criticise United’s lack of spending in the transfer market to bolster Carrick’s squad.

But on this season’s evidence, Martinez is one of those most in need of replacing.

The Argentine international could not cope with Rogers’s strength moments later as he was penalised for hauling back the Chelsea forward.

From the resulting free-kick, Martinez then needlessly crashed into Wesley Fofana with a raised forearm.

After a VAR review, referee Peter Banks awarded a penalty and showed Martinez a second yellow card.

Lammens got hands to Palmer’s spot-kick but still allowed the ball to trickle into the bottom corner.

On a rare start since Xabi Alonso took charge of the Blues, Estevao had a third goal disallowed for offside when he crashed a pass from Palmer into the top corner.

Cries of “sacked in the morning” rained down from the Chelsea fans as their side toyed with United for the final quarter without adding to their lead.

Another big decision awaits the United hierarchy before the massive Champions League clash at home to Roma on Tuesday.

Beaten in two of their three European games so far, United face both the embarrassment and financial shock of an early exit should they fall to another defeat against the Italians at Old Trafford.
Source link

US Bank Failures Pile Up — Is It Just Noise?

Another U.S. bank collapses, and experts wonder whether the failure is a canary in a coal mine or a coincidence.

This article appears in the November issue of Global Finance Magazine.

A sixth U.S. bank failure this year has reignited a familiar question on Wall Street: Is the banking system flashing a 2023-like warning?

California’s Department of Financial Protection and Innovation closed Nano Banc of Irvine, California, on Sept. 25, citing the lender’s deteriorating financial condition, and appointed the Federal Deposit Insurance Corp. as receiver. Sunwest Bank assumed approximately $605 million in Nano Banc’s deposits.

The closure occurred about a month after regulators shut Philadelphia’s Tioga-Franklin Savings Bank. Other failed institutions include Metropolitan Capital Bank & Trust (Chicago), Community Bank and Trust (LaGrange, Georgia), Kentland Federal Savings and Loan Association (Kentland, Indiana), and Small Business Bank (Lenexa, Kansas).

That brings the 2026 tally to six, the most since 2017 and one more than in 2023, when Silicon Valley Bank (SVB), Signature Bank and First Republic Bank collapsed. While most of the experts Global Finance spoke to say the current failures appear small, lingering balance-sheet vulnerabilities mean the underlying risks of 2023 haven’t fully disappeared.

No Rapid Runs Bode Well, but…

“They do share a pattern, but it isn’t the 2023 pattern,” said David Maya, global risk lead at Dublin-based management consultancy Accenture. “No deposit runs. No rate-driven bond losses. Every one of them was a slow failure — weak management, then losses, then the capital ran out.”

According to California’s DFPI, Nano Banc suffered from mismanagement, poor governance and “insider trading risks.” A similar “operational weakness” narrative followed Tioga-Franklin Savings Bank’s closure.

Maya cautioned against alarm. “All six together held about $1.4 billion in assets,” he said. “Silicon Valley Bank alone had $209 billion. This is not that.”

This year’s count is also a far cry from the 507 U.S. bank failures recorded between 2008 and 2014. Still, some industry experts are asking whether the liquidity and interest-rate shocks that toppled larger banks in 2023 are resurfacing.

Stephen Curry, founder and chairman of Endurance Advisory, said the problems exposed in 2023 have been only “partially fixed.”

“Uninsured deposits remain concentrated, and losses on held-to-maturity securities are still substantial,” he said. “To me, the biggest unresolved issue is supervisory follow-through. While the regulators did a good job identifying the problems, they still need to be consistent and timely in enforcing regulatory corrections.”

Lessons From Abroad

Europe offers a sharp contrast. The European Banking Authority said that banks in the European Union and European Economic Area remain resilient, with near-record capital ratios and solid asset quality.

Donald van Deventer, managing director of risk research and quantitative solutions at data and AI company SAS, attributes much of the gap to how mortgages are structured.

“European mortgages are much more likely to be floating rate or fixed rate for fairly short maturities before rate reset,” he said. “The 30-year U.S.-style fixed-rate mortgage is something extremely rare in the European market. So in that sense, there is structurally less interest rate risk embedded in the balance sheets of European banks.”

Most U.S. 30-year mortgages are sold to Fannie Mae and Freddie Mac rather than held by banks. Lenders absorb much of the same rate risk by buying mortgage-backed securities, which were the losses that sank SVB.

Echoes of 1990s Japan

Van Deventer sees a closer parallel in mid-1990s Japan, where he was with Kamakura Corp., which he founded. Real estate prices fell by as much as 80%.

“People in the U.S. at the time said that it could never happen to us,” he said. “Then in 2008-2010, it did.”

The danger, he said, is built into how banks are funded. Deposits can be withdrawn at any time, which he described as a put option no corporation would attach to its own bonds. When a bank’s assets are illiquid and depositors exercise that option, the bank cannot sell assets quickly enough to meet the demand for cash.

That dynamic helped sink Lehman Brothers in 2008. Its real estate-linked securities plunged, and rivals, knowing the firm had to sell, lowered their bids. In 2023, it fueled runs on Silicon Valley Bank and First Republic.

“And I worry we will see it again,” van Deventer said.

Where Maya sees isolated management failures, van Deventer sees the same macro forces at work.

“This year’s bank failures were triggered by the rebound in interest rates to higher levels and price pressure on real estate,” he added. “I have spent my career avoiding making forecasts, but the current environment is remarkably similar to the S&L crisis in the late ’80s and early ’90s. It is very similar to 2008-2010. And similar to Japan in 1996-1997.”

Anthony Noto covers corporate finance and private credit. Contact him at anoto@gfmag.com

Source link