Universal Pictures’ (CMCSA) supernatural horror thriller “Other Mommy” scared up an estimated $27.5 million in domestic ticket sales over the weekend, leading the North American box office as moviegoing revenue for 2026 surpassed $8 billion.
This week, insider transactions were seen across firms like Marvell Technology (MRVL) and Taiwan Semiconductor (TSM). The following is a list of deals that took place during the week.
Procter & Gamble (PG) Chief Financial Officer Andre Schulten sold
Trump Accounts promise children a financial head start. Al Jazeera’s Emma Withrow spoke with one parent asking why he can’t opt out, or choose investments that align with his beliefs. Here’s what the rules actually say.
EU Trade Commissioner Maroš Šefčovič announced a deal with China on Friday to curb imports of Chinese hybrid vehicles into the EU and facilitate access to rare earths.
ADVERTISEMENT
ADVERTISEMENT
While the understanding signals a preference for a diplomatic resolution to the growing trade imbalance, European leaders are pushing for stronger measures to level the playing field. They are expected to review the details at a summit in Brussels next week.
The EU has also floated retaliatory measures if the outcome falls short of expectations.
Šefčovič travelled to Beijing on Wednesday for two days of intensive talks with his Chinese counterpart, Wang Wentao, in a bid to rebalance EU-China trade relations.
The EU is facing a record trade deficit with China of €1 billion a day, as a surge in low-cost Chinese imports threatens entire sectors of European industry.
“We have reached a shared understanding to moderate China’s export of hybrids and plug-in hybrids to the European Union,” Šefčovič said. “This opens up the prospect of cutting China’s exports by more than half.”
The commissioner said the deal would also improve access to the Chinese market for a range of EU products, from “car parts to olive oil and footwear”, representing almost €4 billion in current export value. It should generate at least €225 million in duty savings, he added.
Market access has been at the heart of EU-China discussions since negotiations began last June. Beijing has been reluctant to relinquish access to the EU’s 450-million-consumer market, which provides an outlet for its excess production.
Meanwhile, Brussels has proposed several legislative measures aimed at restricting Chinese companies’ access to the European market, while pressing Beijing to open up its own market to EU businesses.
Šefčovič also said China had agreed to facilitate exports of rare earths, which are essential to Europe’s green technology, defence and automotive industries.
“We have reached a shared understanding to further facilitate China’s export licensing for rare earths and permanent magnets,” he said.
The EU has accused China of “weaponising” its dependence on Chinese rare earths after Beijing restricted exports in 2025 amid a trade war with the US.
Šefčovič described the agreement as the conclusion of a “first phase of negotiations”.
The deal comes ahead of a meeting of EU leaders in Brussels next week, with expectations running high for concrete results from negotiations led by the European Commission on their behalf since last June.
A consensus on China has been emerging across the EU this week.
All EU countries now run trade deficits with China. On Monday, Germany and France urged the European Commission to take strong action against unfair Chinese trade practices that cause severe market distortions.
In a joint document, Paris and Berlin called for measures that could include “an immediate cut-off from the internal market if needed”.
On Wednesday, MEPs overwhelmingly adopted a resolution calling for resolute measures against Beijing.
Meanwhile, 44 EU industries, including chemicals, machinery, metals, solar, glass and cement, issued a joint statement on Friday warning that “Europe cannot maintain and grow its industrial base, quality jobs, and attract investment without the ability to respond effectively to unfair trade practices and distortions”.
Caledonia Mining (CMCL) fell 2.6% in Friday’s trading after reporting Q3 gold production at its Blanket mine in Zimbabwe declined 11% Y/Y to 19,106 oz, citing a shortage of compressed air at certain high-grade, high-volume mining areas and
Strong regulation and dynamic regulators are helping nurture a fintech boom across the region.
This article appears in the October issue of Global Finance Magazine.
The number of fintech startups in Latin America has grown by 340% over the past six years as these companies take a leading position in areas such as financial inclusion, cross-border payments, and instant payments.
Nubank reached a milestone in January, becoming the largest private bank in Brazil with over 112 million users, according to the Central Bank of Brazil. The instant payment system Pix now accounts for more than half of transactions in the country and has some 170 million users, with 80% to 95% of the country using the service.
“Creative laws are not always good laws. So you can have very creative regulation that is not necessarily very good regulation,” said Eduardo de Los Heros, legal manager at Bitso, a Mexican cryptocurrency trading service and fintech. “Brazil has very advanced regulation for digital payments, and El Salvador has made Bitcoin its calling card to position itself as the crypto regional hub.”
Brazil, Colombia, and Mexico account for about 57% of all Latin American fintechs, with remittances, loans, and financial management the main segments. In Mexico, the arrival of Mercado Libre and its subsidiary Mercado Pago, as well as Nubank, has forced traditional banks to offer their own digital alternatives.
“Mexico and Brazil, as the biggest economies, are pushing towards regulation. El Salvador is small but dynamic and has a fantastic regulatory sandbox,” said Daniel Leiva, partner at Torres Legal in El Salvador. “Then there are countries that are also pushing forward, like Colombia and Argentina. Argentina is fighting to integrate fintechs into the economy.”
With a Fintech 2.0 Law due in Mexico, the market is starting to mature as adoption of digital banks and payment schemes increases across the region. Mexico now has over 1,000 fintech companies, second in the region only to Brazil.
“This famous law has the objective to develop open finance as well as public access to user data of Mexican financial projects,” said de Los Heros, “creating clear regulations for virtual actors, tokenization, and stable coins.”
That would not be a minute too soon, as Mexico’s rapid fintech expansion has outstripped the Comisión Nacional Bancaria y de Valores (CNBV)’s ability to regulate, Leiva said.
De Los Heros does not believe the law will be ready this year; there is no publicly available draft of the law, nor is a draft bill before Congress or the Senate. Yet, speaking at the Fintech Festival 2026 in February, CNBV President Ángel Cabrera claimed that Mexico was technologically ready for Fintech 2.0, adding, “The CNBV’s vision is to build an ecosystem of digitally born entities that generate value where cash still predominates today.”
Leiva points to El Salvador as another example of dynamism in the industry.
With one regulator, the National Commission of Digital Assets (CNAD), working in tandem with the Central Bank of El Salvador, the focus has been on neutral laws; CNAD regulates certain types of activities, like crypto, without marrying the law to specific technologies. A broader scope allows for quicker adoption and avoids delays in achieving regulatory consensus on specific blockchain models, for example. This enables distributed technologies and similar models to be regulated more effectively.
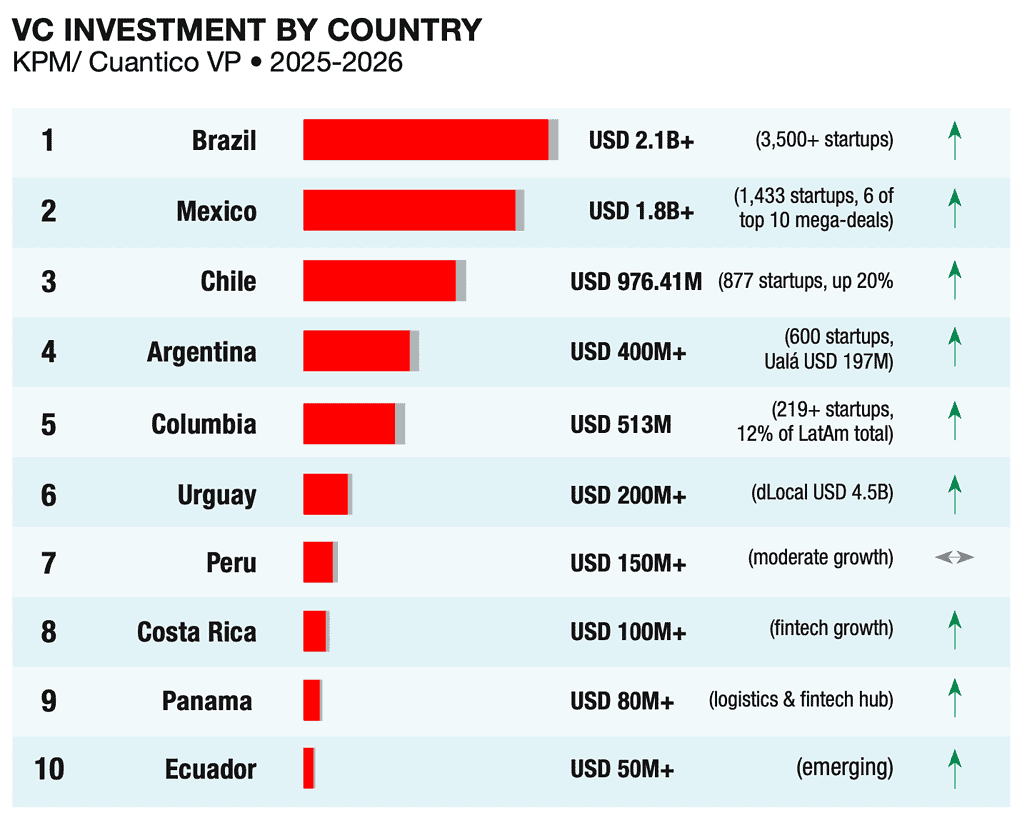
(Brazil and Mexico concentrated 78.5% of all regional VC in 2025. Fintech captures 61% of capital. Source: KPMG, Cuantico VP, StartupBlink • 2025-2026)
From Sandboxes to Standards
Colombia’s instant payment system, Bre-B, was launched by the Banco de la República last October. Bre-B aims to connect traditional banks, fintechs, and digital wallets through a single public digital platform. By August, it had recorded 1.51 billion transactions and more than 35 million users; 171 financial institutions had integrated by then. Those numbers could be even better if the bank had been less passive and restrictive over the past couple of years, according to Leiva.
Eduardo De Los Heros, Bitso
That said, Colombia’s fintech sector is at a crossroads, with rapid uptake butting up against a new regulatory framework. The Banco de la República and the Superintendencia Financiera de Colombia have instituted new regulations to protect consumers, ensure financial stability, and combat money laundering. Fintechs now have to adhere to the same standards as traditional banks, including rigorous know-your-customer protocols.
“I am not convinced that excessive regulation is the ideal mechanism for the financial services users,” says de Los Heros. “But in regions like Latin America, where there’s not always advanced banking options, it can be that regulation brings positive effects, at least because it protects users against possible abusive practices by stock markets, financial entities, or virtual service providers.”
Peru’s attempts to integrate banks, fintechs, and users on a single inter-platform payment system under one legislative umbrella are also attracting attention. The Andean nation has “a high index of unbanked people,” de Los Heros said, and in theory, having a unified system with a single platform could speed mass adoption. “We have to see how an interactive interbanking and inter-platform payment system could be adopted region-wise. It’s more important to have an interbanking system that works than an inter-platform system that is not adopted.”
In the medium term, both de Los Heros and Leiva foresee a maturing market with heightened regulatory scrutiny. More regulation does not necessarily mean a more restrictive environment in a region where institutions have been praised for creativity and dynamism, and where central banks responded to the Covid-19 pandemic in ways that avoided the inflationary pressures other countries endured.
Daniel Leiva, Torres Legal
“Powerhouses like Nubank or Mercado Libre didn’t exist 25 years ago, so creating regulation for them is complex,” Leiva said. “I firmly believe the big actors like Nubank will move into other regions. They will go global. We’re going to have to implement new regulatory mechanisms, like allowing a banking license to be used across Central America.”
Latin America can build on its reputation for forward thinking and dynamic legislation, he added.
“Through new mechanisms of payment, like Pix, [Brazil, Mexico, and El Salvador] are the three regional pillars of legislative development,” he said. “Very interesting things are coming, and you could say Latin America is the lungs of fintech laws globally.”
Not everything is rosy, and de Los Heros is particularly concerned with the implications of AI and how to regulate it.
“AI causes me to lose sleep,” he said. “I really doubt that the industry has all the controls needed. To protect financial systems and society against the unmeasured use of AI and its consequences, we might have to start from zero to establish a lot of norms that we haven’t even thought about yet.”
Nic Wirtz is a contributing writer based in Guatemala.
Lions Bay Capital Inc. (LBI:CA) received a failure-to-file cease trade order from the British Columbia Securities Commission on October 5, 2026.
The order follows the company’s failure to file its audited annual financial statements, management’s discussion and analysis, and CEO/CFO certifications for
J.P. Morgan has initiated coverage of gene therapy developer Neurogene (NGNE) with an Overweight recommendation, highlighting its lead program NGN-401 targeting a rare neurodevelopmental disorder known as Rett syndrome.
Analyst Priyanka Grover’s bullish view came at a time when shares
Webull (BULL) responded to the CNBC report yesterday that drove its share prices lower, saying that the House Select Committee’s report “gets important facts wrong”.
Shares were 2.21% lower at $5.76 around noon trading on Thursday.
The island nation sets out to eliminate high fees and multi-day delays for African cross-border transactions.
This article appears in the October issue of Global Finance Magazine.
In a fragmented landscape, aggregation matters. This philosophy underpins Mauritius’s quest to become the epicenter of cross-border payments in Africa, where layers of friction and an inability to converge have impeded deeper economic integration.
By building frictionless systems anchored in regulation, technology, and market dynamics, Mauritius, a small, upper-middle-income island nation of just 1.26 million people, is redefining payments in Africa and shifting the narrative for a continent long bound to Western capital in international payments.
“Through trust, Mauritius has become a hub for digital finance,” said Shane Mungur, senior associate at Mauritius-based law firm BLC Robert & Associates.
The reality of cross-border payments in Africa is that businesses and entrepreneurs must route transactions through correspondent banks in Europe and the U.S., paying fees as high as 7.1%, compared with a global average of about 2.8%. Worse, transactions can take as long as seven days to complete.
Mauritius’s effort to demonstrate that seamless payments in Africa are feasible is part of the nation’s ambitious transition to what it terms a “future-ready economic” model. This includes shifting the economy from dependence on sugarcane production and textiles and apparel to a new framework with the financial sector as the heartbeat. It has also meant shifting the focus of its search for a competitive edge from regional and bilateral trade treaties, legal and regulatory reforms, tax incentives, and the speedy incorporation of companies to cutting-edge innovation.
“Mauritius remains relevant and attractive as payment ecosystems evolve,” said Sharmilla Bhima, a partner at Mauritius-based law firm Appleby. Expanding its international financial center’s scope to cover cross-border payments is based on a conviction that Africa’s economy can only transform and become truly resilient if money can move across borders efficiently, securely, transparently, and affordably.
In recent years, more than $80 billion in Africa-bound investments have been structured through Mauritius. More than 450 private equity funds are now domiciled there, deploying capital across the continent.
“Mauritius is a jurisdiction that serves as a gateway for businesses seeking to participate in Africa’s growing economic integration,” Bhima said.
Cross-Border Payments Boom
The timing appears to be right.
Africa’s cross-border payments market is ballooning. Valued at $329 billion last year, it is projected to hit the $1 trillion mark in the next decade. Fragmentation nevertheless remains a barrier to unleashing the benefits of cross-border payments, cutting against the growth of trade, investment, entrepreneurship, financial inclusion, and economic integration.
Plans for a common currency to replace more than 40 local currencies remain a pipe dream while multiple regulatory regimes, limited interoperability, weak transparency, and dependence on intermediary currencies make friction a constant.
The continent continues to depend on hard currencies that are in short supply, increase conversion costs, and tie up working capital. Yet, the success of the African Continental Free Trade Area, the continent’s most ambitious effort at market integration, stands or falls largely on the ability of the member states to settle transactions in local currencies. The same applies to e-commerce, which is impeded by strict domestic transfer restrictions and high fees. Only 55% of African governments permit electronic know-your-customer and remittance costs are the highest globally, averaging 8% to 8.5%.
As Africa tries to tackle cross-border payments, some 36 instant payment systems, 33 country systems, and three regional systems are live, enabling some instant payments but also adding complexity. The Pan-African Payment and Settlement System remains the boldest initiative to counter these impediments. So far, 31 countries, 190 commercial banks and fintechs, and 16 payment switches are connected.
Sticking to the Basics
Shane Mungur, BLC Robert & Associates
Mauritius aims to provide its own answer by sticking to the basics of finance. Its regulatory focus is on creating a predictable environment that attracts investment and encourages transparent and secure capital flows: not just a safe haven or conduit for laundering.
Predictability has made Mauritius a hotspot for foreign direct investment. Last year, FDI inflows reached a record $1 billion, up from $705.7 million in 2024. Most of this — $400 million — was in the financial services sector, compared to just $20.8 million in 2024.
The Bank of Mauritius has assembled what it considers to be robust hardware and software infrastructure that can integrate with existing systems across multiple jurisdictions. The Mauritius Automated Clearing and Settlement System and the Mauritius Central Automated Switch (MauCAS), both administered by the central bank, were designed with interoperability in mind. The former settles transactions in major currencies as well as the local rupee.
“This is one of the most effective competitive edges in payments,” Mungur said.
Mauritius is also exploiting its strategic location as a financial bridge between Africa and Asia. A partnership with China enables settlement of transactions with renminbi while linking MauCAS with India’s switch has significantly boosted digital payments.
While regulation and technology are fundamental to Mauritius’s positioning as a payments hub, so is its ability to adapt to changing market dynamics. By removing exchange controls, the rupee is fully convertible, while foreign currency accounts can be held locally and no approval is needed to repatriate profit or capital. This is critical for treasurers moving money across African borders.
The central bank is also cognizant of the payments landscape’s fluidity, from electronic transfers to mobile wallets, QR-based payments, blockchain, tokenization, and many other channels, and has made encouraging financial innovation a priority.
“Encouraging innovation has enabled Mauritius to adopt new technologies that improve speed, reduce costs, and enhance client experience,” said Bhima. Regulators have nevertheless been careful to safeguard financial integrity and prevent inherent risks associated with like money laundering, terrorist financing, fraud, cybercrime, and sanctions evasion.
On this, Mauritius understands that trust is essential to establishing itself as a hub for cross-border payments.
(Source: State of Inclusive Instant Payment Systems in Africa 2025)
John Njiraini is a contributing writer based in Kenya.