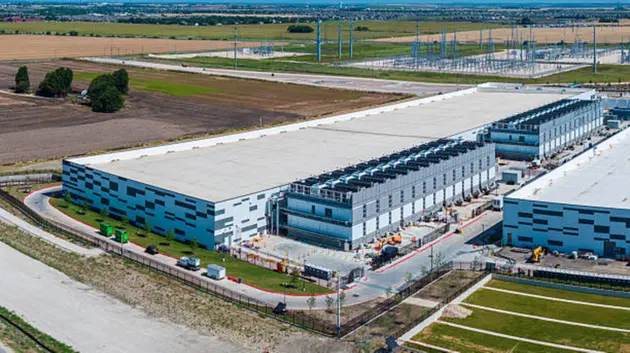
U.K. artificial intelligence cloud computing firm Nscale is looking to raise $3.5B in new financing, with Nvidia (NVDA) and hedge fund Third Point likely participating, Bloomberg reported.
Nscale could sell as much as $1.5B in convertible notes, and Third Point, which is run
Brazil’s EU ambassador, Pedro Miguel da Costa e Silva, told Euronews on Friday that an inspection of Brazilian meat was unnecessary, and threatened to retaliate against the EU ban on imports.
ADVERTISEMENT
ADVERTISEMENT
The European Commission’s decision came into force this week, after Brazil was removed from a list of countries complying with EU food safety rules over its use of antibiotics to stimulate animal growth.
An EU audit of Brazilian poultry and honey is ongoing, but the Commission said that Brasília had not provided guarantees that would allow for an audit of its beef.
The EU ban prompted anger from the Brazilian government on Thursday, which threatened to adopt countermeasures.
“Sufficient guarantees”
“There wasn’t a need for an audit, not for poultry, not for honey, not bovine meat, because no audits were conducted for the other countries,” da Costa e Silva said. “We have provided sufficient guarantees.”
The ambassador added that while Brazil will continue discussing the issue with the Commission, “all options were on the table” if the imports did not resume and that Brazil could be “creative” when it comes to countermeasures.
The Commission pushed back on Friday against Brasília’s accusation of unfair treatment, with the Commission’s deputy Chief spokesperson Olof Gill saying: “Our approach is non-discriminatory, and we’ve given our partners sufficient time and all the information they need to adjust.”
The dispute comes as a free trade deal between Mercosur countries — Brazil, Argentina, Uruguay and Paraguay — and the EU provisionally came into force in May, despite strong opposition from EU farmers, who fear that Latin American products that do not comply with the bloc’s phytosanitary and food safety standards will be dumped in Europe.
“Food safety rules are a matter of the highest priority for EU citizens,” Gill added. “These rules have been well known for a long time, with third countries having been informed going back many years.”
The EU introduced new rules to combat antimicrobial resistance in 2018, which have been applied to EU producers since 2022 and to foreign importers since Thursday.
Crude oil is on track for its largest weekly gain since July as escalating tensions between the U.S. and Iran raise fears of extended supply disruptions through the Strait of Hormuz.
HomeBankingPeople on the Move: EIF, Barclays, Standard Chartered, and Julius Baer
This article appears in the September 2026 issue of Global Finance Magazine.
Jean-Christophe Laloux, EIF
The European Investment Fund (EIF) has appointedJean-Christophe Laloux as its next CEO, effective Jan 1. He will succeed Marjut Falkstedt, who plans to retire.
Laloux currently leads the European Investment Bank’s lending and advisory operations in the EU and has spent more than two decades at the EIB. He has helped develop financing tools for high-growth technology companies, infrastructure, climate projects, and private-sector investment, including venture debt, risk-sharing mechanisms, and project finance.
EIF Chair Nadia Calviño praised Laloux’s track record in developing innovative financing tools to support Europe’s technological competitiveness. Before joining the EIB in 1999, Laloux worked at Boston Consulting Group and PricewaterhouseCoopers. —Anthony Noto
Mike Jool and Adeel Khan, Barclays
Mike Jool and Adeel Khan will take the reins of Barclays’ investment bank business in February as co-CEOs, subject to regulatory approval. Jool will join the bank early next year from Bank of America, where he most recently co-headed global investment banking. Khan currently leads Barclays’ global markets.
Each will have a seat on the bank’s group executive committee. “Since 2023, our investment bank has delivered a strong performance, growing revenues and returns and driving a more integrated service for clients,” said C.S. Venkatakrishnan, Barclays Group chief executive.
“As we enter the next stage of our strategy, and reflecting the ambition we have for our investment bank, Adeel and Mike will form a strong partnership to deliver an even stronger, more integrated service to our clients.”—Rob Daly
Manus Costello, Group CFO
Standard Chartered PLC confirmed the appointment of Manus Costello as Group CFO and executive director. Costello’s appointment, initially announced in May, formalizes his role atop the emerging markets-focused banking group.
The 25-year industry veteran spent 14 years at AllianceBernstein, rising to global head of research, and earlier served as senior director of equity research at Merrill Lynch.
Since joining Standard Chartered in 2024 as global head of Investor Relations, Costello has made “a significant contribution to the group’s strategic positioning and engagement of stakeholders, while also bringing strong rigor and an entrepreneurial mindset to the role,” CEO Bill Winters said in a press release. —Luca Ventura
Peter Burrill, Group CFO
Swiss private bank Julius Baer appointedPeter Burrill as CFO and member of the Executive Board, effective August 17, subject to regulatory approval. He joins from Standard Chartered, where he was interim group CFO for nine years. Before that, Burrill spent nearly four years at Deutsche Bank as group controller and co-head of group finance, He succeeds Evie Kostakis after a top management shake-up.
“We are delighted to welcome Pete to Julius Baer,” Bollinger said in a press release. “He brings profound depth and breadth of financial expertise, having led the full range of finance and regulatory functions. With extensive international experience across our core markets and working at a bank strongly focused on wealth management, he will be an outstanding addition to our team.” —LV
Solana (SOL-USD) has launched Payment Channels, allowing AI agents to authorize a spending limit once and make multiple payments without requiring approval for every transaction.
The feature lets AI agents pay for things like data, computing power, and AI-generated answers
Anthropic (ANTHRO) is set to finalize an expansion of its revolving credit facility to $15B, clearing a key hurdle ahead of its highly anticipated IPO, Bloomberg reported, citing people familiar with the matter.
Shareholders of Dominion Energy (D) and NextEra Energy (NEE) overwhelmingly approved the companies’ proposed $67B merger deal, according to 8-K filings on Thursday (I, II).
The deal, which is pending regulatory approvals, would create one of the world’s largest electric utilities with an
The US FDA on Thursday approved Ionis Pharmaceuticals’ (IONS) Zanvastro (zilganersen) as the first-ever treatment for Alexander disease.
The antisense oligonucleotide won approval based on results of a randomized, controlled study of pediatric and adult patients with the condition two years of age and older, and in
Revolut gets an OCC thumbs up to launch a US bank, but lending ambitions are another issue.
Technically, financial technology company Revolut is already a bank across several regions—it holds licenses in the U.K., France, Mexico and Australia.
Now, in the U.S. market, it is one step closer to bankhood.
The London-based startup announced Thursday that it has received conditional approval from the U.S. Office of the Comptroller of the Currency for a national bank charter. The move would help the company grow its customer base from 80 million to 100 million by mid-2027.
It also exemplifies Revolut’s agility as a fintech compared to traditional banks, which typically take years to pull off similar expansion efforts.
“Legacy banks are working with legacy systems,” David Tirado, Revolut’s VP of Profitability and Global Business, told Global Finance in an interview last year. “Revolut, on the other hand, built our proprietary technology from the ground up with a global mindset. While competitors struggle to scale across different markets and regulatory landscapes, our systems were designed for this from day one.”
What Else Does Revolut Need?
Revolut still needs a green light from the Federal Deposit Insurance Corp. and the Federal Reserve, as well as final sign-off from the OCC, before it can open the proposed bank.
Once fully approved, Revolut said it would offer U.S. customers loans, credit cards, FDIC-insured deposits, and access to stablecoins and cryptocurrencies.
In a prepared statement, Revolut founder and CEO Nik Storonsky said the conditional approval was “an important first step towards establishing the proposed Revolut Bank US,” adding that it gives the company “the foundation to build in the world’s largest financial market.”
The U.S. bid follows Revolut’s expansion across Latin America, where the company recently launched a bank in Mexico and is pursuing licenses in Brazil, Colombia, Peru and Argentina. This year, Revolut has also obtained banking licenses in France, Australia and the U.K., a payments license in the United Arab Emirates, and is seeking a banking license in South Africa.
The company claims to add roughly 1 million customers every 17 days.
What About Lending?
Whether Revolut can become a customer’s primary financial institution without being a major loan underwriter remains to be seen. Revolut’s consumer lending segment remains small relative to its tens of billions in customer deposits. Still, it’s worth noting that the so-called neobank’s loan book, as of March, is up 120% year over year at $2.9 billion.
Felipe Peñacoba Martinez, CEO of Getnet Platforms Payments Hub and former CIO at Revolut Bank (EU), told Global Finance in June: “Revolut is aware this takes time, and they’re going slower than in other areas.”
Ultimately, the central question facing the industry is whether fintechs like Revolut can scale core banking products faster than traditional incumbents can modernize their digital ecosystems.
Anthony Noto covers corporate finance and private credit. Contact him at anoto@gfmag.com
The European Commission suspended imports of meat from Brazil on Thursday over concerns about antibiotic use, after Brasília failed to convince the EU executive that its products comply with European standards.
ADVERTISEMENT
ADVERTISEMENT
The move comes as Brazilian meat imports lie at the heart of opposition to the free trade agreement signed in January 2026 by the Commission with Mercosur countries — Brazil, Argentina, Paraguay and Uruguay.
EU farmers accuse Latin American producers of failing to comply with the bloc’s phytosanitary and food safety standards, arguing that this gives Latin American products an unfair advantage on the EU market.
“We have rules that ban antimicrobials or using antimicrobials for growth,” Commission spokesperson Eva Hrncirova said. “On the 3rd of September, the list of countries that basically comply with our rules on antimicrobials comes into application.”
The spokesperson added that Brazil was not currently on the list, meaning its imports were suspended as of Thursday.
No guarantees for beef
The suspension, which resulted from a vote by national experts in May, covers beef, poultry, eggs and honey.
Imports of some products could resume following an audit of poultry and honey, launched on the basis of written guarantees of compliance provided by Brasília. The audit is expected to run until the end of the week, although the conclusions will take longer.
Hrncirova said no such guarantees had been provided for beef, adding that they must cover the animals’ entire life cycle, which is naturally longer for cattle.
Brazil’s ambassador to the EU, Pedro Miguel da Costa e Silva, told Euronews ahead of the summer that technical discussions with the Commission were ongoing. However, Brazil ultimately failed to prevent the suspension from taking effect.
Trade in agricultural products was the most contentious issue throughout the 25-year negotiations over the Mercosur agreement.
The deal was provisionally applied in May after the European Parliament suspended the ratification process with a legal referral to the European Court of Justice.
Responding to Trump’s tariff barrage, Canada pivots from continental nostalgia to global dealmaking.
This article appears in the September 2026 issue of Global Finance Magazine.
Following President Donald Trump’s reelection in 2024, something extraordinary occurred, not seen since the War of 1812. The president not only took aim at Canada as a potential annexation target, but also breached his own USMCA trade deal by imposing punitive tariffs on the country to the north (among many others).
This prompted Canadians to turn away from their traditional focus on continental trade and pursue deals with other, friendlier markets (and, in protest, take liquor from the U.S. off their shelves).
The Liberal Party’s electoral victory soon after, and Mark Carney’s ascension as prime minister, expedited the process. Responding to the newly hostile environment, the new PM pledged to double Canada’s exports by 2035, diversify foreign trade, and reduce reliance on what was, and still is, Canada’s largest trading partner.
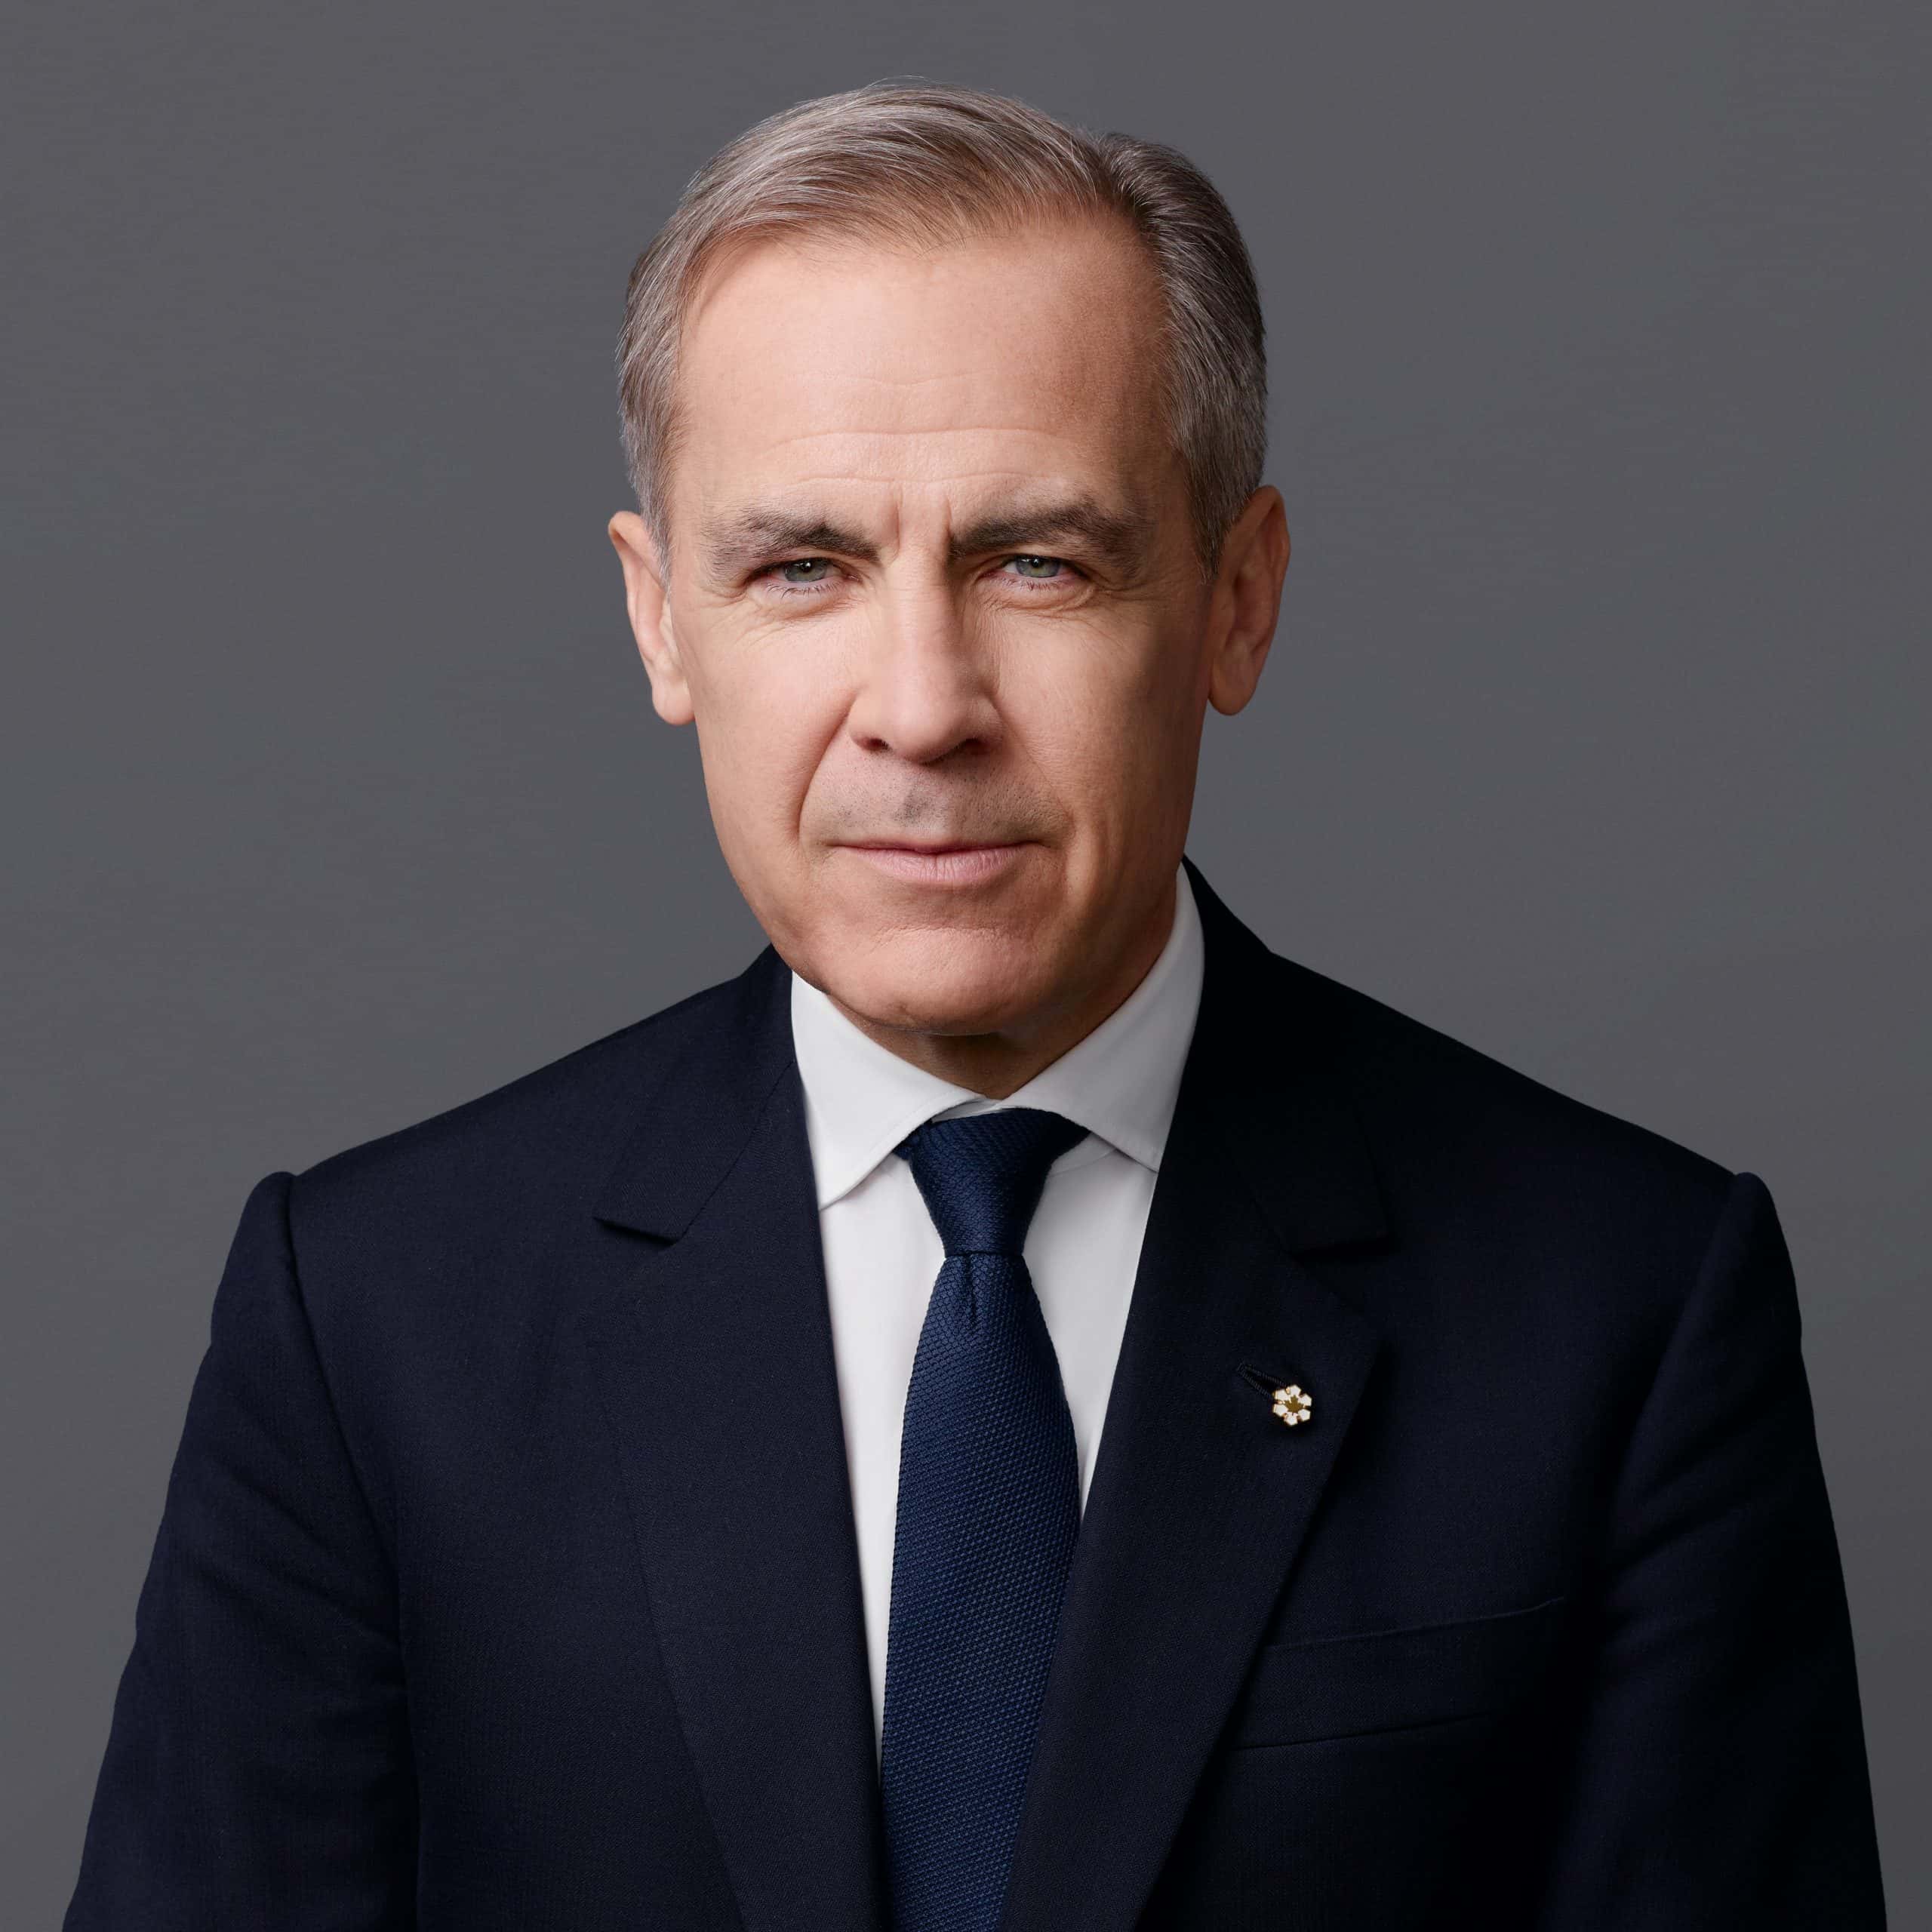
Mark Carney, Canadian Prime Minister
“The old relationship we had with the United States, based on deepening integration of our economies and tight security and military cooperation is over,” he said. On another occasion, he was even more pointed: “Our relationship with the United States will never be the same as it was, even though, in the new protectionist world, we have the best trade deal of any country.”
That was then. Of course, now a war of words has become a full-blown trade war. With Canada backing away from what it considered a bad deal, the U.S. added tariffs to autos, auto parts, and aluminum, beginning January 2027, as a punishment for breaking off recent talks. Canada retaliated with tariffs of its own ranging from 15% to up to 50% on many American goods. As Carney stated at a news conference, “You’re at war when you are attacked. And we were attacked.”
A Strategic Reorientation
But a trade reorientation for Canada made sense on its own, some experts say. About four-fifths of the world’s economic activity occurs outside the U.S., much of it in Asia, according to the Fraser Institute, a nonpartisan Canadian think tank. “These facts suggest Canadian policymakers are right to emphasize the importance of expanding trade with non-U.S. markets,” it concluded.
Carney, accordingly, has been crisscrossing the globe, cutting deals with countries including India, China — where it reduced tariffs on electric vehicles, against U.S. wishes — and the United Arab Emirates, and has engaged with ASEAN members on a possible free trade agreement. All this is occurring, incidentally, as he continues to pursue tariff reduction with the U.S. and salvage as much of the free trade Canada has enjoyed with its neighbor to the south as possible.
This past summer, Maninder Sidhu, Minister of International Trade of Canada, established a new Strategic Exports Office and a Strategic Exports Advisory Council. The aim is to bring together diplomatic, commercial, and financial experts to help break down global trade barriers and open doors for Canadian businesses.
The new bodies “mark a decisive step toward doubling our exports to non-U.S. markets,” he said, “and they give Canadian businesses the whole-of-government support they need to compete and win around the world.” Goods exports to non-U.S. markets are up about 17% from 2024 to 2025, an increase of C$33 billion (US$24 billion), Sidhu’s office said. To some observers, the pivot is not only something to navigate but also an opportunity for the world’s 11th-largest economy, according to the International Monetary Fund.
In the long term, Canada’s economy could expand its manufacturing base and raise its standard of living.
Joel Kranc is a contributing writer based in Canada.
PayPal (PYPL) quickly ticked higher by 0.7% amid some renewed takeover speculation.
There’s some speculation that the fintech company has received takeover interest, according to traders, who cited a Betaville “uncooked” alert that was circulating on Thursday.
China’s service sector activity expanded at a faster pace in August 2026, with the RatingDog China General Services PMI rising to 51.4 from July’s 50.4, which had marked the softest growth since September 2024.
Steve Ballmer has been tattered. Lawrence Frank has been shredded. Their team future has been flattened.
Boom, goes those damn Clippers.
They had transformed themselves from the ridiculed Clip Joint to a top-shelf NBA organization, with the billionaire owner, the beautiful arena, the best coach and the most devoted fans … but they apparently got greedy, seemingly played dirty, and now have been affixed with a scarlet eight letters that will follow them forever.
Ballmer, cheater. Frank, cheater. Even president of business operations Gillian Zucker, cheater.
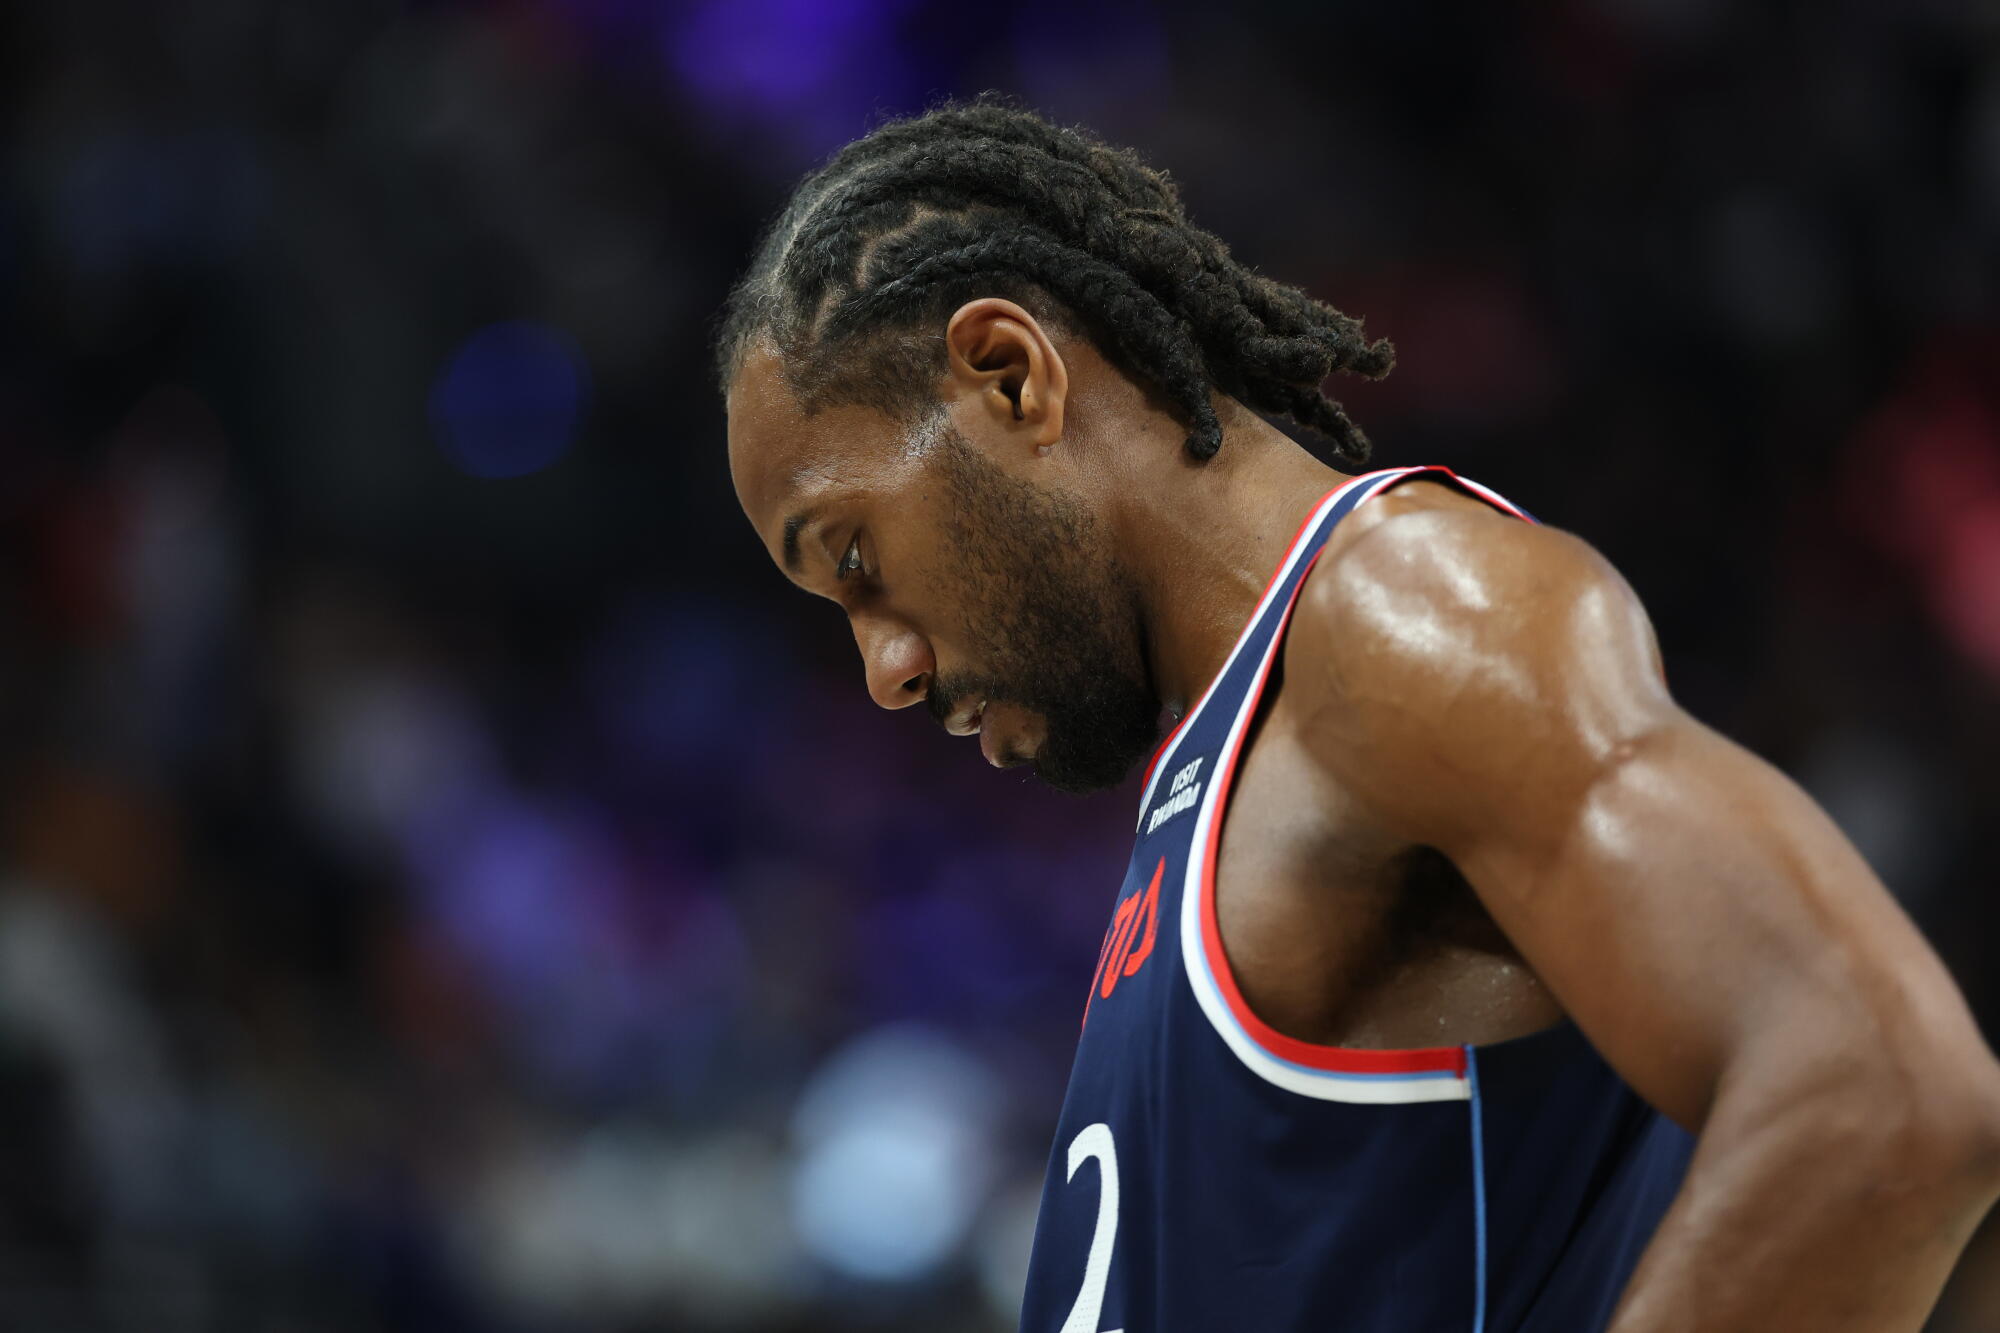
The NBA suspended Ballmer and Zucker for one year and Frank for six months Wednesday for violating salary cap rules when they signed Kawhi Leonard in 2019.
In arguably the harshest punishment in sports since SMU was given college football’s death penalty in 1987 — this is even worse than the USC sucker punch of 2010 — the league added injury to insult by stripping the team of five consecutive draft picks from 2029 to 2033.
The league also fined the team $30 million and Leonard $700,000 but the issue here is not money.
The issue is trust.
How can any of the Clippers partners or sponsors or fans trust this team with their dollars or their time or their affection after they were apparently caught knowingly breaking one of the NBA’s cardinal rules?
You don’t mess with the salary cap. Period. It’s the one thing that keeps these disparate teams and markets competing on a level field. Period.
Yet according to the findings of a lengthy investigation by the NBA, the Clippers’ top three executives — Ballmer, Frank and Zucker — helped arrange rich endorsement deals for Leonard that allowed him to make considerably more money than his contract states. Leonard did little if any endorsing, collected the extra checks, and essentially was paid above and beyond the salary cap.
The circumvention was first revealed a year ago by the podcast “Pablo Torre Finds Out,” which cited a $28-million endorsement deal with the now-bankrupt Aspiration, a sustainability services company. The subsequent NBA investigation discovered three more endorsement deals that amounted to similar salary cap circumvention, a charge which drew the particular ire of the league because the Clippers had been warned about salary cap circumvention with Leonard before.
Kawhi Leonard, above during a game against the Golden State Warriors at Intuit Dome in January, signed with the Clippers in 2019.
(Sean M. Haffey / Getty Images)
Bottom line, the Clippers seemingly flouted the rules, got burned, got punished, and now you have to wonder, how on earth do they move forward from this?
They started the recovery process immediately Wednesday by issuing a statement that accused the NBA of not playing fair.
“We vehemently reject the NBA’s findings, which are the result of a heavily biased investigation seeking to justify a predetermined narrative rather than facts and evidence,” the statement began.
They can let out one of those trademark Ballmer screams and it still won’t matter. There is no arbitration or appeals process available. The NBA’s ruling is final.
All of which leaves the Clippers facing serious questions about their future.
First, will Ballmer still have the local support to own the team? His absence from his traditional seat under the basket will serve as a nightly reminder that he commanded a dirty ship. Their most vocal cheerleader is now their biggest scoundrel, and how do you come back from that?
Although he made great strides in dragging the Clippers back into relevance since buying the team from the shamed Donald Sterling in 2014 — even building that cool arena in Inglewood — Ballmer has lost much credibility with this decision.
He may need to sell to help the organization shed its stink. There’s been so much peddling of billion-dollar franchises around town lately, surely some rich group is in a position to take the Clippers off his hands.
Then there’s the matter of Frank, who was struggling to build sustained success before this scandal. It would be a surprise to see him return, just as it would be a surprise to see Zucker return. For the Clippers to come out of this mess, they’re going to need to retool at the top.
Which brings this story to one Clipper leader who was not indicted in the investigation. How much longer will Ty Lue, one of the league’s very best coaches, want to stick around this mess? He has three years left on his contract. That could be three long years.
Finally, what of Kawhi Leonard? The Clippers thankfully traded him back to Toronto this summer, and hopefully that is where he’ll stay if the trade gets taken off hold with the investigation complete.
In all, just when you thought the Clippers reputation in this town had long since moved past all those years of losing and insults and embarrassments and Sterling scandals, just when you thought it couldn’t get any worse…
Pro Football Hall of Fame running back Emmitt Smith has been accused of taking part in a scheme that allegedly scammed $2.5 million from a Native American investment firm.
In a lawsuit filed Monday in Delaware’s Court of Chancery, a tribal owned and operated economic developmental agency for the North Carolina-based Eastern Band of Cherokee Indians claimed the former Dallas Cowboys superstar, his longtime business partner David Mosley and their real estate development and renewable energy company 4 13 Solutions Inc. borrowed the money, did not use it for its intended purpose and have not paid it back.
According to the lawsuit, Smith and Mosley convinced the tribal agency, Kituwah LLC, to help their company acquire a proposed solar energy farm in Texas.
“By using false projections and data, misrepresenting the level of interest and potential investments from other investors, making promises that they had no intention of fulfilling, and relying on the participation of other coconspirators, Smith and Mosley induced Kituwah to form a joint venture with their company, 4 13 Solutions, and to loan $2.5 million to the joint venture,” the complaint states.
“Smith and Mosley promised to use the funds to acquire an interest in a renewable energy project in Texas (‘Project Exodus’), transfer that interest back to the joint venture, and ultimately repay Kituwah’s money. But instead, they took the money and used it to improperly pay Wilson Holdings, with whom they had partnered on other ventures.”
Smith, Mosley, 4 13 Solutions, Wilson Holdings and its principal owner, Darrel Wilson, and the group’s joint venture firm, Jabez 4 10 LLC, were named as co-defendants. Representatives for Smith, Mosley and 4 13 Solutions did not immediately respond to requests for comment.
The loan came due on Feb. 1, 2024, according to the complaint, and remains unpaid despite numerous efforts to collect. Smith is accused of fraudulent inducement and breach of fiduciary duty. Seeking the return of its investment as well as interest and other costs and expenses, Kituwah says it is owed more than $3 million.
“Moreover, despite 4 13 Solutions’ representation that Project Exodus would be up and running by the end of 2024, Kituwah has not seen any evidence that Project Exodus has made any meaningful progress towards completion,” the lawsuit states.
“Kituwah commenced an investigation. It has determined that 4 13 Solutions’ representations were part of Smith’s and Mosley’s scheme to cheat Kituwah out of $2.5 million dollars. Instead of using the loan proceeds to acquire Project Exodus as promised, 4 13 Solutions used the $2.5 million to pay Wilson Holdings, apparently for money that Wilson Holdings had previously invested. Essentially, like a Ponzi scheme.”
We strive to provide essential intelligence to our international audience of senior financial executives. As part of this mission, we have launched the new Private Credit newsletter and have expanded our coverage of Private Credit sector in our print and digital editions.
The Hidden Risks of Payment-in-Kind
BlackRock’s CEO Exit Signals Private Credit Shift
Private Credit Stress Test: What Breaks And What Holds
The US dollar broke above 2.1 million Iranian rials on Tehran’s free market on Wednesday, setting a new record as the rial lost around 60% of its value against the dollar since the start of the Iranian calendar year in March — when the dollar traded at approximately 1.35 million rials.
ADVERTISEMENT
ADVERTISEMENT
The rial’s slide has accelerated since the US reimposed a naval blockade on Iranian ports in July, following the collapse of a short-lived ceasefire.
The euro hit an unprecedented 2.55 million rials, and the UK pound reached 2,976,000 rials.
The UAE dirham, which serves as the benchmark for pricing the rial on regional markets, reached 600,000 rials for the first time.
One gram of 18-carat gold climbed above 225.7 million rials, and the Imami gold coin — a standard unit of value in Iran — changed hands at 2.26 billion rials.
Iran operates a dual exchange rate system. The official rate, set by the Central Bank and used for state transactions and subsidised imports of essential goods, is significantly stronger than the free market rate available to ordinary Iranians and businesses.
The gap between the two has widened sharply since the war began, with the free market rate now more than double the official rate.
The rial has been in freefall since the US-Israeli strikes against Iran on 28 February launched the ongoing war, now in its seventh month, and has accelerated as Washington has tightened its economic pressure campaign.
The US Treasury has cut off Iran’s access to regional banks, severing one of the Islamic Republic’s main channels for accessing foreign currency and clearing import payments.
The naval blockade of Iranian ports has compounded the pressure by restricting trade routes and reducing Iran’s oil export revenues.
Abdolnaser Hemmati, governor of the Central Bank of Iran, said the bank was ready to inject $2 billion into the foreign exchange market to stabilise the rial. He attributed the latest slide primarily to psychological factors rather than fundamental economic ones.
“The dust created in the foreign exchange market will settle, and the recent increase in exchange rates is driven more by psychological factors than by real economic factors,” he said.
Hemmati acknowledged that inflation had placed heavy pressure on households.
“Although inflation and rising prices have placed heavy pressure on people’s livelihoods and daily lives, and these difficulties are tangible, the Central Bank has been able to control the accelerating pace of inflation by using monetary, supervisory and prudential tools,” he said.
He rejected US claims that Tehran lacked access to financial reserves.
“These claims are completely baseless. The reserves have not been frozen, and the Central Bank has access to stable resources as well as multiple oil and non-oil revenues,” he said, claiming that more than $18 billion in foreign currency had been provided for imports of essential goods, medicines, animal feed and raw materials since March.
He provided no further details to support the figure.
The rial’s collapse is feeding directly into consumer prices. Iran was already experiencing high inflation before the war, while the currency’s further depreciation has raised the cost of all imported goods, raw materials and energy inputs.
Iranians who hold savings in rials have seen their purchasing power roughly halved in less than six months. Gold and hard currency have become the primary store of value for those who can access them.
Iran’s official currency is the rial, although most Iranians conduct everyday transactions in tomans — a colloquial unit equal to 10 rials that is so deeply embedded in daily use that shops, restaurants and property listings quote prices almost exclusively in tomans.
At Wednesday’s free-market rate, the US dollar traded at about 220,000 tomans. The government announced plans in 2020 to formally replace the rial with the toman and remove four zeros from the currency, a redenomination that has not yet been fully implemented.
In an exclusive interview, European Union Trade Commissioner Maroš Šefčovič told Euronews that the EU is not in a position to mediate in the trade war between Canada and the United States following the collapse of their trade talks.
ADVERTISEMENT
ADVERTISEMENT
Ten days ago, Canadian Prime Minister Mark Carney walked away from the negotiations with the Trump administration, blaming them for pressuring Canada over the use of the French language.
In the following days, US President Donald Trump announced 50% US tariffs on Canadian cars and trucks, to which Ottawa retaliated with tariffs on more than 700 US imports, worth about $20 billion (€17.2 billion).
“I don’t think that we are in a position to mediate,” Šefčovič said. “At the same time I know that they [Canada and the US] have such a close economic relationship that, despite the current tension, sooner or later there will be attempts to resolve it.”
The Commissioner added that “tariffs are taxes which are paid in the end by the economic operators or by the citizens”, a message he has reiterated several times over the last year during the EU’s own trade dispute with Washington.
“We clearly support free and fair trade with the lower or no tariffs at all,” he told Euronews.
Ready to cooperate
Since the trade talks stopped, Carney has called for a closer relationship between Ottawa and Brussels and announced he will attend European Commission President Ursula von der Leyen’s State of the Union in Strasbourg in mid-September, one of the main events in Brussels’ political calendar.
An EU-Canada summit is also scheduled for later this autumn.
Šefčovič said the Commission is ready to explore “all possibilities” to increase cooperation with Canada, but he added that any new arrangements “would very much also depend on how comfortable the Canadian side would feel and what is its level of ambition”.
He pointed out that after Brussels clinched a trade deal with Ottawa in 2016, trade between the EU and Canada grew by 75% – but he also suggested that the deal could be pushed further.
“On both sides, we have certain elements which we can improve, still certain barriers, certain sensitivities for the products. I really think that we can explore much more that.”
Šefčovič said that a digital agreement might be signed with Canada before the end of the year, and he also cited coming cooperation in critical raw materials with potential joint investments.
Ottawa is seen by Brussels as a like-minded partner sharing its vision of the new global trade order, and Šefčovič hopes to have its backing to get closer to members of the Comprehensive and Progressive Agreement for Trans-Pacific Partnership (CPTPP), which has liberalised trade between 12 countries in the Asia-Pacific region and the Americas, including Canada – but not the US. The UK became the pact’s first and to date only European member in 2024, with Canada ratifying its full accession as of 1 September.
“Canadians are very important partners for forging a new level of cooperation with the CTPPP,” Šefčovič said, “which represents together 40 percent of global trade.”
As Head of Group Transaction Banking at Raiffeisen Bank International (RBI), I have witnessed how European exporters navigate an increasingly complex global trade environment. With over 30 years of experience in cash management and transaction banking, I have come to view success in international business as a function of resilience, digital readiness, and the right network of partners.
Supporting Exporters Across Borders
At RBI, we support European exporters by combining robust transaction banking capabilities with deep local knowledge across Central and Eastern Europe (CEE) and other markets. Our international network connects clients with markets far beyond their home base. This global reach allows us to offer comprehensive solutions such as cash and liquidity management, letters of credit, guarantees, and other trade finance solutions through a single banking relationship. This integrated approach is vital for companies managing cross-border business in multiple currencies and jurisdictions.
Embracing Digital Innovation in Trade Finance and Cash Management
The landscape of trade finance and cash management is evolving rapidly, driven in part by the accelerating pace of trade finance digitalization. Centralization, real-time visibility, and digital connectivity are no longer optional, but essential. Exporters increasingly require treasury structures that operate seamlessly across countries and currencies, with direct ERP integration and enhanced reporting capabilities. Solutions such as CMIplus and multi-bank connectivity are designed to reduce manual work and increase efficiency. Investment in AI-supported digital documentary workflows and improved data handling is beginning to show results by accelerating trade processes, enhancing transparency, and strengthening risk control.
Navigating Market Challenges with Local Expertise
European exporters face significant challenges in today’s market environment. Geopolitical tensions, sanctions, foreign exchange volatility, and divergent legal and regulatory frameworks complicate international trade, particularly across the diverse CEE region. Some markets are part of the EU or the euro area, while others operate under different currencies and legal systems. This complexity demands careful local assessment and practical risk management, including stronger compliance checks, diversified market exposure, and closer monitoring of counterparties. In this context, a banking partner that combines local expertise with international reach is crucial.
Responding to Exporters’ Growing Demands
Client needs are evolving alongside these market dynamics. Exporters expect fast, secure, and transparent payment solutions, reliable financing, and support that operates effectively across multiple markets, currencies, and systems. They value banks that can efficiently connect headquarters and subsidiaries, balancing local presence with centralized control. At RBI, we tailor our services by integrating local account coverage, trade finance, supply chain finance, and treasury connectivity, enabling clients to manage liquidity and trade flows more efficiently across CEE and beyond.
The Future of Transaction Banking
Looking ahead, the outlook for international business and transaction banking remains constructive. Significant opportunities remain, but success will increasingly depend on digital readiness, resilience, and strong networks. Centralization and better visibility will shape the future of banking services, with partners such as RBI supporting growth across Austria, CEE, and global markets.
Ultimately, our mission at RBI is clear: Make international business happen.
Discover practical insights and solutions for navigating international trade with confidence here.