Mining

Trump announces $15bn steel mill project in Iowa before US midterms | Manufacturing News

Amid tight Iowa midterm races, President Trump emphasises steel industry revival with project announcement.
Just weeks before the midterm elections, United States President Donald Trump has announced that a Minnesota-based steel manufacturer intends to build a $15bn steel mill project in Iowa, as the White House tries to highlight its focus on domestic manufacturing.

On Monday, joined by executives from Mesabi Metallics, which recently opened Minnesota’s first new iron ore mine in 50 years, Trump announced the project. It is expected to begin production in 2030 and could bring more than 1,700 jobs to the region, with an initial production capacity of 7.5 million tonnes per year.

Recommended Stories

list of 4 itemsend of list

The first phase of construction for the project will generate 5,000–6,000 construction jobs, a White House official told Al Jazeera.

The plant in Iowa will use iron ore from the Mesabi Iron Range in nearby Minnesota. Mesabi, which is owned by Indian conglomerate Essar Group, invested more than $2.5bn to build the mine in Minnesota.

“President Trump is delivering on his promise to rebuild American industry, re-shore manufacturing, and create new jobs. Today’s announcement underscores the president’s historic efforts to revitalize the US steel industry—supporting local communities, strengthening supply chains, and protecting our national security,” White House Spokeswoman Taylor Rogers said in a statement to Al Jazeera.

The steel industry has loomed over the first half of Trump’s second term in office. The president imposed 50 percent tariffs on steel and aluminium imports last year in an effort to boost domestic production, but also threatened to increase prices of products that use those materials, from soda cans to washing machines to cars.

“These are your 232 tariffs, the steel tariffs at work. Without those tariffs, this mine does not get built, and this steel plant does not get built”, US Commerce Secretary Howard Lutnick said in the Oval Office on Monday.

Trump also solidified the US government’s stake in US Steel, which was acquired by Japan’s Nippon Steel in June 2025. As part of the deal, the US government received a so-called “golden share”, which gives the president the authority to appoint a board member to weigh in on decisions that would impact domestic steel production.

Midterm stakes

The announcement comes a little more than a month ahead of the US midterm elections, and the economy is top of mind for US voters.

Among Republicans, Trump is losing steam on his handling of economic issues, with a new September 21 Ipsos poll finding that 56 percent approve of his handling of the economy, down from 80 percent.

Iowa is in play as a seat Democrats could flip in the midterm elections, with Republican Ashley Hinson facing Democrat Josh Turek in November and with polls suggesting a tight race.

Hinson joined the president in the Oval Office for the announcement.

A poll conducted by the Republican-aligned pollster the Trafalgar Group showed Hinson with a two-point lead, while an InsiderAdvantage poll, which is considered more nonpartisan, found Turek leading by two points.
Source link

‘Deadly hazards’: Behind Sudan gold mine collapse, a wartime desperation | Sudan war News

A gold mine collapse in northern Sudan has killed at least 10 people and injured 21, according to survivors, bringing renewed attention to the dangers facing workers in one of the country’s most important and least regulated industries.

The collapse took place on Sunday at the Awny mining area near Sudan’s border with Egypt. Miners told the AFP news agency they had recovered 10 bodies and pulled 21 injured workers from the site, while the search continued for people believed to be trapped beneath the rubble. It is unclear how many people are trapped in the collapsed mine.

The disaster comes just days after another deadly accident at a gold mine in West Kordofan State. A collapse at the al-Zaraa mine near en-Nahud, a town in central Sudan, left at least 82 people dead.

Sudan is one of Africa’s top gold producers, recording 70 tonnes of production last year, according to the Sudanese government.

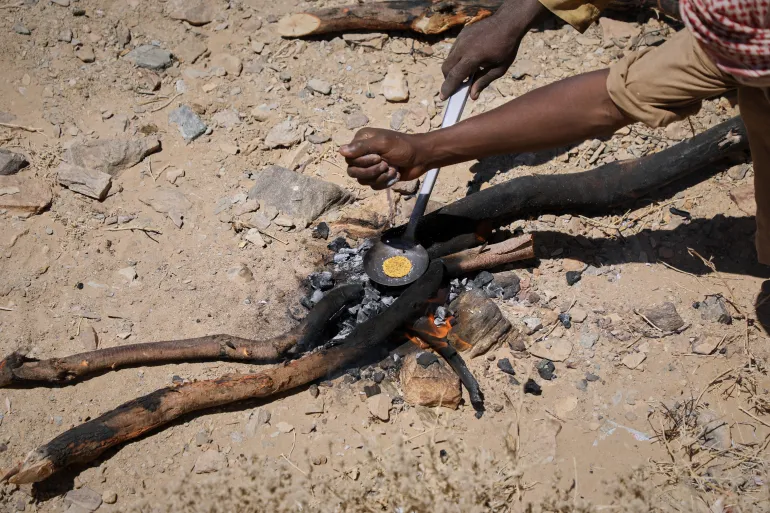
Miners heat processed gold concentrate over an open fire at an artisanal mining site in Dalago Mahas, Sudan's Northern State, Friday, May 8, 2026.(AP Photo/Mohnd Blal)
Miners heat processed gold concentrate over an open fire at an artisanal mining site in Dalago Mahas, Sudan’s Northern State, Friday, May 8, 2026 [Mohaned Bilal/AP Photo]

Since fighting broke out in April 2023 between Sudan’s army and the paramilitary Rapid Support Forces (RSF), businesses have been devastated, agriculture has been disrupted, millions of people have been displaced, and Sudan’s formal economy has weakened. In that environment, gold has remained one of the country’s most valuable sources of income.

In July 2025, it was reported by local agencies that Sudan’s gold production rose sharply despite the ongoing conflict, reaching 64 tonnes in 2024, 53 percent higher than the 41.8 tonnes recorded in 2022, and generating $1.57bn in legal export revenues.

However, the gold trade has also become a point of international scrutiny. Most of the gold exports end up in the UAE. In March 2025, Sudan went to the International Court of Justice (ICJ), accusing the UAE of supporting and funding the RSF using gold. The UAE has denied accusations that it supplies weapons to the RSF.

INTERACTIVE - Where is Sudan’s gold - NOV12, 2025-1763449902

Sudan’s gold deposits are spread across the country, with the majority in the northeast. Port Sudan, the country’s main port, is home to most of the deposits and has been largely controlled by the Sudanese Army since the war began. However, areas controlled by the RSF are also populated by gold deposits.

At the moment, “much of Sudan’s gold is taken out of the country through smuggling or illicit networks instead of passing through government channels that could directly contribute to public revenue,” said Joseph Tucker, senior analyst on the Horn of Africa at the International Crisis Group.

But amid that diplomatic battle and the accusations surrounding gold, the mining deaths in northern Sudan have also raised larger questions over how the country manages the sector, analysts say.

“This disaster is yet another example of the deadly hazards facing those working in Sudan’s gold mines,” Tucker told Al Jazeera. “Most of these (gold mines) are informal, artisanal mines in remote areas that are unregulated and lack modern mining technology, adequate infrastructure, and specialised safety equipment.”

This year, Sudanese Prime Minister Kamil Idris met with the minister of minerals and spoke on the policies for regulating traditional mining and the management and control of various mineral markets. According to French-based Sudanese media, Sudanese authorities called for swift action to address the environmental damage and public health hazards caused by mining activities across the country.

Yet, despite the dangers, Tucker said the state of the Sudanese economy made gold mining appear lucrative to many Sudanese.

During the war, the Sudanese currency’s value has crashed. Before the outbreak of fighting in 2023, about 570 Sudanese pounds could buy a US dollar. By April 2026, the currency had slid to a sixth of that value: It cost 3,500 pounds or more to afford a dollar. That has led to sharp food inflation and a surge in the costs of transport and fuel.

According to estimates by the United Nations Development Programme, Sudan lost $6.4bn of its gross domestic product (GDP) in 2023 alone: That’s a quarter of the country’s $26bn GDP that year. In August, the UN agency reported that 90 percent of the agrarian nation’s farmers had seen yields drop over the previous year.

That economic crisis, Tucker said, “fuels the demand for gold and willingness of miners to work in poor conditions” – even if it proves deadly.

Source link

US, China open high-level talks ahead of Trump-Xi summit | Donald Trump News

Scott Bessent and He Lifeng meet in New York for US-China talks ahead of the Trump-Xi meeting later this week.

Top economic officials from China and the United States have begun talks in New York City aimed at clearing the way for possible agreements on trade, artificial intelligence and critical minerals ahead of a meeting between US President Donald Trump and Chinese President Xi Jinping later this week.

US Treasury Secretary Scott Bessent and Chinese Vice Premier He Lifeng began talks at JPMorgan Chase’s Manhattan headquarters on Sunday morning, with US Trade Representative Jamieson Greer also taking part.

Recommended Stories

list of 4 itemsend of list

The talks come four days before Trump is due to host Xi at the White House, with both sides looking to ease tensions between the world’s two largest economies.

“I’m looking forward to having focused, fulsome and constructive talks today that will set the stage for our leaders’ meeting,” Bessent told reporters as he arrived.

At the top of the agenda is a fragile US-China trade truce due to expire on November 10.

The agreement, reached in Busan, South Korea, last November, capped US tariffs on Chinese goods at about 20 percent after a tit-for-tat trade fight briefly pushed tariffs into the triple digits.

Washington is also pressuring Beijing over its supply of rare-earth magnets and other critical minerals, crucial to industries ranging from cars to advanced semiconductors.

China promised to restore the flow of critical minerals under last year’s truce, but a senior US official said on Friday that Beijing’s performance had “not been up to par”.

AI enters the talks

Artificial intelligence (AI) is also expected to feature prominently, adding a relatively new issue to negotiations long dominated by trade.

Bessent has said the countries could discuss AI “guardrails” aimed at addressing shared risks, including preventing powerful models from falling into the hands of malign non-state actors.

The talks are expected to cover both open- and closed-weight AI models. Chinese open-weight models have increasingly attracted US companies, in part because they can be cheaper than closed systems developed by US firms such as OpenAI and Anthropic.

“The United States remains the leader in AI,” Bessent said. “And we are open to discussions on avoiding shared risks and avoiding bifurcation of our two systems.”

Another potential point of friction is Iran. China remains one of Tehran’s most important economic partners and buys much of its oil, making Beijing an important target of Washington’s efforts to increase economic pressure on Iran as the US-Israel war on Iran enters its seventh month.

Expectations remain low

Despite the packed agenda, analysts are not expecting a sweeping breakthrough.

“I think there will be some show of deliverables because of the fact that it’s a presidential summit coming, but I don’t feel like we’re on the verge of some sort of breakthrough,” Anna Ashton, a China trade analyst and founder of Ashton Intelligence, told Reuters.

“I think status quo is probably both sides’ general best expectation.”

Former US Deputy Secretary of State Kurt Campbell similarly said the immediate goal may simply be keeping tensions contained.

“One of the only things we can hope for in the short term is a truce, and that this will likely continue through the remainder of this year,” Campbell said.

Sunday’s negotiations are part of a series of meetings between Bessent, He and Greer over the past 16 months aimed at hammering out areas of agreement before Trump and Xi meet face to face.

Source link

Trump Allies Secure Venezuela Resource Concessions as ExxonMobil Eyes Return

Venezuela has opened its energy and mining sectors to US interests. (PDVSA)

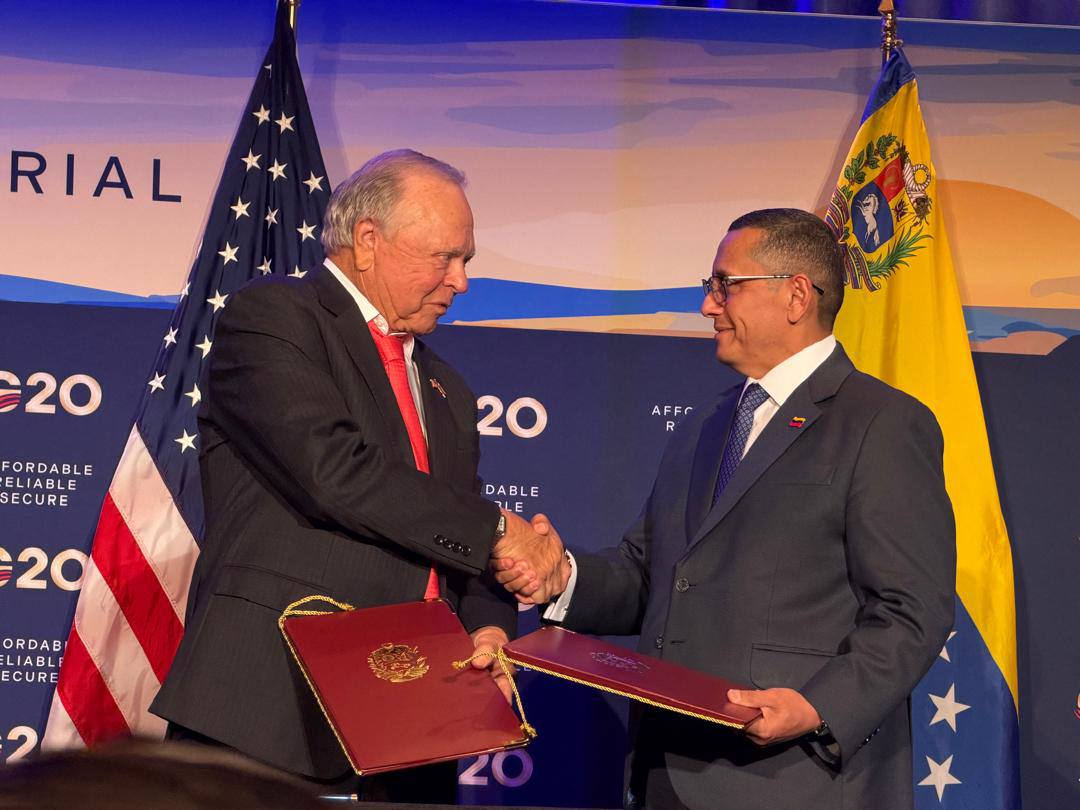
Lisbon, Portugal, September 17, 2026 (venezuelanalysis.com) – Continental Resources, a firm owned by billionaire and Trump donor Harold Hamm, struck a deal on Wednesday to exploit one of Venezuela’s largest oilfields.

Under the agreement with Venezuelan state oil company PDVSA, Continental will receive a long-term concession with “100 percent working interest” for the 500 square-kilometer Ayacucho 2 block in Venezuela’s Orinoco Oil Belt. The block contains an estimated 30 billion barrels of extra-heavy crude.

“Continental was built to recognize great resource opportunities and have the conviction to pursue them,” Hamm told Fox News, vowing that the deal would take his company to an “entirely new level.”

For her part, Venezuelan Acting President Delcy Rodríguez claimed that the agreement would “strengthen [Venezuelan] oil production” and “create opportunities for economic growth.”

Hamm and PDVSA Vice President Jovanny Martinez signed the contract in Houston on the sidelines of the G20 energy summit. Martínez and Oil Minister Paula Henao attended the conference to pitch investment opportunities in Venezuela’s oil and gas sector.

PDVSA had previously assigned the Ayacucho 2 block to Chinese private firm Anhui Guangda in 2025. However, no information on investments or output were publicly disclosed, while Venezuelan authorities have not justified rescinding the contract with Anhui.

US government-controlled corporation NABEP, which recently received long-term concessions to 17 major Venezuelan oilfields containing 65 billion barrels in reserves, will also take over projects formerly run by Chinese enterprises, including state-owned CNPC. Beijing has called for its investments and interests in Venezuela to be respected.

Hamm was one of the corporate executives present at the White House on January 9, when Trump announced that Washington would control Venezuela’s oil industry and called on Western majors to invest. Since the January 3 US attacks and kidnapping of President Nicolás Maduro, the White House has managed the South American country’s crude export revenues.

The White House has also backed Venezuelan authorities’ pro-business overhaul of the energy sector while issuing sanctions exemptions to select US-aligned corporations. Chevron, Shell, and Eni are among the companies that have signed new contracts or renegotiated existing ones in recent months.

According to Bloomberg, ExxonMobil is in advanced talks to return to the Caribbean country after a litigious past. The energy giant is negotiating rights to four major oilfields in the Orinoco Oil Belt, two of which it previously owned before they were nationalized by former President Hugo Chávez.

In the 2000s, the Texas-based corporation refused to comply with reforms implemented to assert state sovereignty over the oil industry. ExxonMobil refused compensation offers and pursued international arbitration after its assets were nationalized. The company received an arbitration award significantly below its demands. 

ExxonMobil was additionally denounced repeatedly by Caracas after it spearheaded offshore drilling projects in the territorial waters of the disputed Essequibo Strip.

On Wednesday, Venezuelan authorities likewise inked a 20-year agreement with Florida-based Denarius Holding Group, controlled by Turkish energy group Çan2 Termik. Denarius is taking over the Petrokariña project in Anzoátegui state, which contains 10 oilfields producing a variety of crude types.

Heeney Capital receives gold mine concession

In parallel to its oil opening, Venezuelan authorities have also fast-tracked reforms opening the country’s mining sector to multinational corporations.

On Wednesday, New York-based Heeney Capital and commodities trader Mercuria Energy received a 30-year concession to operate the Chocó 10 mine in Bolívar State. The project holds considerable gold deposits and was run by Rusoro Mining in the 2000s before being nationalized by the Chávez government.

Heeney and Mercuria pledged US $1 billion in initial investment in the Chocó project. The two firms had struck a previous agreement with Caracas to purchase and trade Venezuelan minerals and other commodities.

One of Heeney’s co-founders, Sean Pi, signed the deal at the presidential palace in May and praised Trump’s “leadership” in defending US access to mining resources abroad. Pi has endorsed legislative initiatives deregulating and streamlining mining projects to bolster the US supply of critical minerals.

Under the trading agreement, Heeney and Mercuria are reportedly preparing to ship 15,000 metric tons of Venezuelan aluminum to the US. The corporate partners are likewise seeking to take over VENALUM, Venezuela’s biggest aluminum smelter. Glencore, an Anglo-Swiss mining and trading multinational, is also interested in VENALUM, according to reports.

Venezuelan authorities have not commented on the negotiations for the aluminum smelter. In April, Rodríguez appointed a commission to evaluate privatization of “non-strategic” state assets.

The Trump administration has identified securing access to Venezuelan mineral riches as a key national interest and is reportedly preparing an executive order to boost US corporate participation in Venezuelan mining projects.

Edited by Lucas Koerner in Philadelphia, USA.

Source link