expansion

College Football Playoff expansion to 24 teams could benefit USC, UCLA

Neither USC nor UCLA has made the College Football Playoff since its inception in 2014. Yet the Trojans finished six of those 12 seasons ranked in the Associated Press top 25, while UCLA finished in the top 25 twice and is currently ranked No. 12.

Reports that the CFP is nearing a deal to expand the field from 12 to 24 teams in 2027 should be tremendous news for both schools. UCLA (5-0) is surging after its rousing upset over Oregon, and USC (6-1) is ranked No. 19 after beating Washington and Penn State.

Arduous tests loom during the second half of the season, however, making the chances of getting the nod from the CFP selection committee a coin flip at best.

Next season, however, all it would take is being among the top 24 teams as deemed by the 13-member committee, which considers on-field performance, head-to-head results and strength of schedule the primary criteria.

The Big Ten was the primary driving force behind the expansion, which gained momentum recently when the Southeastern Conference gave its blessing. The CFP management committee, made up of 10 FBS conference commissioners and Notre Dame’s athletic director, met Thursday to discuss the negotiations with ESPN, according to the Athletic and ESPN.

“When you get a room of 50 coaches or whatever we have in this conference together, it’s hard to get everybody to be unanimous on something,” USC coach Lincoln Riley said earlier this season. “This is something where our room has been unanimous.”

ESPN reported that the network would acquire the additional games and continue to be the exclusive home of the CFP through the length of its current six-year contract.

“Constructive discussions with ESPN continued this week,” the CFP said in a statement Thursday night. “We have enjoyed a strong partnership with ESPN since our inception and are appreciative of the productive dialogue we have had throughout the negotiating period and continuing over the last several days. We will provide additional updates on the matters of future format and media rights when appropriate.”

Expanding the CFP would not be without concessions. The lengthier postseason would force the regular season to begin one week earlier and likely eliminate Power 4 conference championship games, which while lucrative, can be redundant and potentially problematic in impacting the CFP slate. Lower and mid-tier bowl games might become extinct, although the six prominent bowls on and around New Year’s Day — Rose, Fiesta, Sugar, Orange, Cotton and Peach — should continue to host the CFP quarterfinals and semifinals.

The format has not been formally approved, but one scenario would give the top eight seeded teams a first-round bye and a home game in the second round. The other 16 teams would play first-round games hosted by the higher seed. It would take five games for a team seeded from nine to 24 to win the championship and four games for one of the top eight.

That’s a lot of football beyond the regular season. The wildly popular NCAA men’s basketball tournament will expand from 68 to 76 teams next spring, but the physical demands of the two sports are markedly different, making the expansion there less onerous on players. Still, if the expansion is approved, the CFP will have its own version of the NCAA’s trademarked titles Sweet Sixteen, Elite Eight and Final Four.

March Madness is another trademarked term, although the NCAA would need to come up with something new for the CFP: December Delirium, anyone?

USC and UCLA presumably would be happy with any name as long as they are invited to the festivities.

Source link

‘Creative’ Laws Underpin LatAm’s Fintech Expansion

Strong regulation and dynamic regulators are helping nurture a fintech boom across the region.

This article appears in the October issue of Global Finance Magazine.

The number of fintech startups in Latin America has grown by 340% over the past six years as these companies take a leading position in areas such as financial inclusion, cross-border payments, and instant payments. 

Nubank reached a milestone in January, becoming the largest private bank in Brazil with over 112 million users, according to the Central Bank of Brazil. The instant payment system Pix now accounts for more than half of transactions in the country and has some 170 million users, with 80% to 95% of the country using the service.

“Creative laws are not always good laws. So you can have very creative regulation that is not necessarily very good regulation,” said Eduardo de Los Heros, legal manager at Bitso, a Mexican cryptocurrency trading service and fintech. “Brazil has very advanced regulation for digital payments, and El Salvador has made Bitcoin its calling card to position itself as the crypto regional hub.”

Brazil, Colombia, and Mexico account for about 57% of all Latin American fintechs, with remittances, loans, and financial management the main segments. In Mexico, the arrival of Mercado Libre and its subsidiary Mercado Pago, as well as Nubank, has forced traditional banks to offer their own digital alternatives.

“Mexico and Brazil, as the biggest economies, are pushing towards regulation. El Salvador is small but dynamic and has a fantastic regulatory sandbox,” said Daniel Leiva, partner at Torres Legal in El Salvador. “Then there are countries that are also pushing forward, like Colombia and Argentina. Argentina is fighting to integrate fintechs into the economy.” 

With a Fintech 2.0 Law due in Mexico, the market is starting to mature as adoption of digital banks and payment schemes increases across the region. Mexico now has over 1,000 fintech companies, second in the region only to Brazil. 

“This famous law has the objective to develop open finance as well as public access to user data of Mexican financial projects,” said de Los Heros, “creating clear regulations for virtual actors, tokenization, and stable coins.”

That would not be a minute too soon, as Mexico’s rapid fintech expansion has outstripped the Comisión Nacional Bancaria y de Valores (CNBV)’s ability to regulate, Leiva said.

De Los Heros does not believe the law will be ready this year; there is no publicly available draft of the law, nor is a draft bill before Congress or the Senate. Yet, speaking at the Fintech Festival 2026 in February, CNBV President Ángel Cabrera claimed that Mexico was technologically ready for Fintech 2.0, adding, “The CNBV’s vision is to build an ecosystem of digitally born entities that generate value where cash still predominates today.” 

Leiva points to El Salvador as another example of dynamism in the industry. 

With one regulator, the National Commission of Digital Assets (CNAD), working in tandem with the Central Bank of El Salvador, the focus has been on neutral laws; CNAD regulates certain types of activities, like crypto, without marrying the law to specific technologies. A broader scope allows for quicker adoption and avoids delays in achieving regulatory consensus on specific blockchain models, for example. This enables distributed technologies and similar models to be regulated more effectively. 


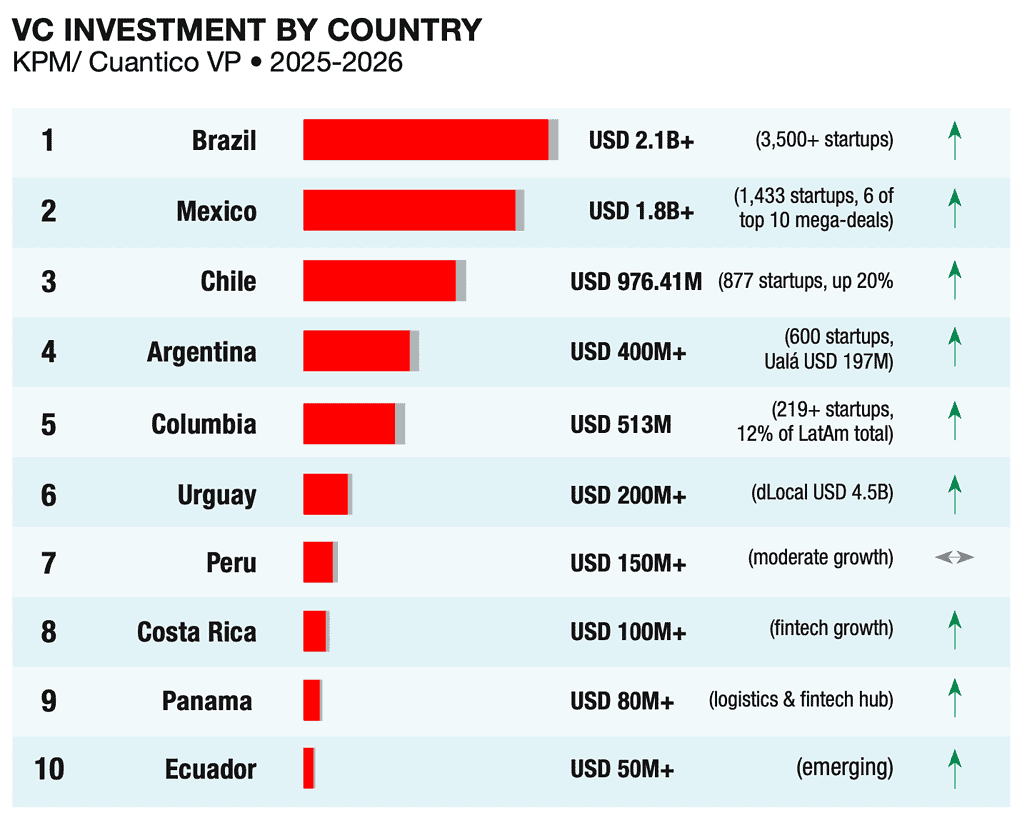
Brazil and Mexico concentrated 78.5% of all regional VC in 2025. Fintech captures 61% of capital. 
Source: KPMG, Cuantico VP, StartupBlink • 2025-2026
(Brazil and Mexico concentrated 78.5% of all regional VC in 2025. Fintech captures 61% of capital.
Source: KPMG, Cuantico VP, StartupBlink • 2025-2026)

From Sandboxes to Standards

Colombia’s instant payment system, Bre-B, was launched by the Banco de la República last October. Bre-B aims to connect traditional banks, fintechs, and digital wallets through a single public digital platform. By August, it had recorded 1.51 billion transactions and more than 35 million users; 171 financial institutions had integrated by then. Those numbers could be even better if the bank had been less passive and restrictive over the past couple of years, according to Leiva. 

Eduardo De Los Heros,
Bitso
Eduardo De Los Heros,
Bitso

That said, Colombia’s fintech sector is at a crossroads, with rapid uptake butting up against a new regulatory framework. The Banco de la República and the Superintendencia Financiera de Colombia have instituted new regulations to protect consumers, ensure financial stability, and combat money laundering. Fintechs now have to adhere to the same standards as traditional banks, including rigorous know-your-customer protocols.

“I am not convinced that excessive regulation is the ideal mechanism for the financial services users,” says de Los Heros. “But in regions like Latin America, where there’s not always advanced banking options, it can be that regulation brings positive effects, at least because it protects users against possible abusive practices by stock markets, financial entities, or virtual service providers.”

Peru’s attempts to integrate banks, fintechs, and users on a single inter-platform payment system under one legislative umbrella are also attracting attention. The Andean nation has “a high index of unbanked people,” de Los Heros said, and in theory, having a unified system with a single platform could speed mass adoption. “We have to see how an interactive interbanking and inter-platform payment system could be adopted region-wise. It’s more important to have an interbanking system that works than an inter-platform system that is not adopted.”

In the medium term, both de Los Heros and Leiva foresee a maturing market with heightened regulatory scrutiny. More regulation does not necessarily mean a more restrictive environment in a region where institutions have been praised for creativity and dynamism, and where central banks responded to the Covid-19 pandemic in ways that avoided the inflationary pressures other countries endured.

Daniel Leiva,
Torres Legal
Daniel Leiva,
Torres Legal

“Powerhouses like Nubank or Mercado Libre didn’t exist 25 years ago, so creating regulation for them is complex,” Leiva said. “I firmly believe the big actors like Nubank will move into other regions. They will go global. We’re going to have to implement new regulatory mechanisms, like allowing a banking license to be used across Central America.”

Latin America can build on its reputation for forward thinking and dynamic legislation, he added.

“Through new mechanisms of payment, like Pix, [Brazil, Mexico, and El Salvador] are the three regional pillars of legislative development,” he said. “Very interesting things are coming, and you could say Latin America is the lungs of fintech laws globally.”

Not everything is rosy, and de Los Heros is particularly concerned with the implications of AI and how to regulate it.

“AI causes me to lose sleep,” he said. “I really doubt that the industry has all the controls needed. To protect financial systems and society against the unmeasured use of AI and its consequences, we might have to start from zero to establish a lot of norms that we haven’t even thought about yet.”

Nic Wirtz is a contributing writer based in Guatemala.

Source link

Medicaid reckoning awaits next California governor after program’s rapid expansion

In March 2025, when California ran out of Medicaid funds to pay doctors and hospitals, the state borrowed $3.4 billion to keep the program afloat. It was, as a spokesperson for Gov. Gavin Newsom insisted, nothing new. Indeed, a handful of times over the years, the state had taken out internal, short-term loans to sustain its healthcare program for poor and disabled people.

The unprecedented move came a few months later, when Newsom and Democratic state lawmakers agreed to pay down the loan — which grew to $4.4 billion — over 10 years instead of later in the year. California’s healthcare safety net, it seemed, was buckling.

Rising healthcare costs systemwide were partly to blame. But so were several state-led expansions that made California’s Medicaid program, known as Medi-Cal, one of the nation’s most generous.

Now, with congressional Republicans’ One Big Beautiful Bill Act expected to reduce federal Medicaid spending by more than $900 billion over 10 years, California and dozens of other states must contemplate the limits of their generosity. The problem is particularly acute in the nation’s most populous state, which spends more on Medicaid than New York and Texas combined.

“We know we can’t afford to serve everybody we want to serve in the model that we have today,” said Mark Ghaly, the former top Newsom health official who now co-chairs the Future of Medi-Cal Commission, a 29-person panel with the goal of modernizing and sustaining California’s Medicaid program for those who need it. “What can we do differently? What can we do smarter?”

The 2025 law that Newsom, a Democrat, has dubbed President Trump’s “Big Ugly Bill” is expected to leave millions more Americans without health insurance, mostly because of new work requirements. It also curbs the use of healthcare provider taxes and other strategies states have deployed to maximize federal funds. Some state lawmakers and consumer advocates have argued the federal cuts, along with rising costs, present an opportunity for the next governor to overhaul a program plagued by long appointment wait times, low reimbursement rates for healthcare providers, and volatile financing.

“If we continue to just give millions and millions into the same system and expect something different — I’m sick and tired of that,” said Caroline Menjivar, a Democratic state senator representing a Los Angeles-area district where roughly half of constituents rely on Medi-Cal.

Democratic lawmakers, who have often clashed with Newsom on Medi-Cal rollbacks, succeeded in getting him to delay a number of painful cuts until 2027 in hope that a new governor might reverse them.

So far, neither of the gubernatorial candidates running in the November election to replace Newsom has offered substantive proposals for a program that covers 1 in 3 Californians — roughly 13.6 million people.

Republican Steve Hilton, a former Fox News commentator, wants to pare back Medi-Cal eligibility and has promised to end coverage for immigrants without legal status, citing that benefit as an example of “wildly unsustainable” state spending. Democrat Xavier Becerra, who has spent decades trying to expand government-funded healthcare, has promised to protect Californians from the massive federal cuts and find and cut billions in administrative waste.

Expanding coverage

President Johnson signed the law that established Medicaid and Medicare in 1965 to cover certain low-income groups, such as families with children, older people and those with disabilities. Over the last six decades, states have substantially widened that pool, most notably under the Affordable Care Act’s Medicaid expansion to childless adults.

Starting in 2024, California offered healthcare coverage to all low-income residents, regardless of age or immigration status, although lawmakers scaled that back this year. At the same time, the state opted to cover a slew of non-mandated benefits such as physical therapy, hospice care and housing assistance.

“California has always struggled with wanting to have as broad a program as possible but then having to figure out a way to pay,” said Jennifer Kent, who oversaw Medi-Cal under Gov. Jerry Brown, a Democrat. “There is no population that we have met that we don’t want to offer coverage to, and we’ve never met a benefit that we don’t like.”

Since 2010, California’s Medi-Cal enrollment has nearly doubled while spending has ballooned from $50 billion a year to $222 billion. It now makes up more than 40% of overall state spending, according to the nonpartisan Legislative Analyst’s Office.

Conservatives argue the program is bloated and rife with fraud. They say the federal changes will force states to refocus resources on the neediest.

“The role of the safety net programs was just that — to be a safety net,” Hilton said in an interview. “I don’t think it’s a particularly positive boast to say 40% of Californians should be on a program that was designed for people living in poverty.”

Becerra declined an interview request.

Nelly, a 59-year-old from Los Angeles County, was one of millions who have benefited from the state’s Medi-Cal expansion, but she was initially reluctant to sign up.

For years after she left her corporate job to care for her ailing mother, Nelly said, she didn’t consider applying. She remained uninsured until three years ago, when she woke up and couldn’t see out of her left eye.

She enrolled in Medi-Cal in the emergency room. It now covers her appointments with specialists and transportation to and from. While her condition may exempt her from the new Medicaid work requirements, Nelly said, she’s still worried about losing coverage after experiencing numerous paperwork hiccups simply trying to renew.

Nelly, who asked that her full name not be used because she hasn’t told her family about her condition, said she understands not everyone on the program may need it. But, she added, “it should be there for someone like me.”

Tough choices ahead

When Republican state lawmakers got wind of Newsom’s plan to stretch the debt repayment over a decade, they accused Democrats of trying to “paper over” the state’s structural deficit.

“This leaves future governors and legislatures to clean up the mess,” stated a July 2025 memo from GOP senators. The Legislative Analyst’s Office later called the maneuver “unusual.” That could leave Becerra, the favorite to succeed Newsom in the overwhelmingly liberal state, as the face of staggering changes to a program he spent his career defending.

More than 2 million Californians under age 65 could lose health coverage over the next four years as a result of the state and federal policy changes, according to recent estimates by the UC Berkeley Labor Center and the UCLA Center for Health Policy Research. At least 730,000 residents have already disenrolled since June 2025.

State agencies are scrambling to implement new federal work requirement rules for adult Medicaid enrollees under 65, hoping to automate as much verification as possible to blunt coverage losses. And in 2028, states will be required to charge some enrollees fees for many services, making it harder for them to maintain coverage.

Disability rights activists say new asset limits will prevent Californians from getting needed home care, which they say is more cost-effective and humane than nursing homes. Counties, deemed by state law to be healthcare providers of last resort, say they need immediate funding for the millions of uninsured patients they anticipate in the new year.

Hospital administrators have urged policymakers to help them keep their facilities stable, and the state’s most recent budget included some $390 million to assist public and distressed hospitals.

Martin Luther King Jr. Community Hospital in Los Angeles treats five times the patients it was designed to serve, and 80% of patients are uninsured or on Medi-Cal. Demand is so high in the chronically underserved area, MLK Community Healthcare CEO Elaine Batchlor said, that the hospital has erected tents in the parking lot. Most emergency room patients are now treated there.

“We already have an extremely overcrowded, overburdened emergency department,” MLK Community Healthcare CEO Elaine Batchlor said. “Insured care will turn into uncompensated care, and the financial burden for that will fall on providers.”

Becerra has said he opposes the state’s recent freeze on enrollment for adult immigrants without legal status, as well as new monthly premiums set to take effect next year, saying such moves will only saddle taxpayers with higher bills for ER care.

If elected, Becerra will probably need to wade into the politically toxic debate over whether to raise more revenue, cut benefits further, or do both.

Aside from promising to find and eliminate billions in administrative waste from the industry, the nation’s former top health official has not explained how he would cobble together the tens of billions of dollars the state is likely to need just to maintain status quo.

The next governor must tread carefully, Kent warned. “When people come and say, ‘Well, you should just do this because it’s the right thing,’ ” she said, “all of those right things have fiscal consequences.”

Mai-Duc writes for KFF Health News, a national newsroom that produces in-depth journalism about health issues and is one of the core operating programs at KFF — an independent source of health policy research, polling and journalism.
Source link

Revolut’s CEO Says US Banks Are ‘Out of Step’ With Global Consumers | Global Finance Magazine Revolut US Bank Expansion: CEO Cetin Duransoy Interview

Home Banking Revolut’s CEO Says US Banks Are ‘Out of Step’ With Global Consumers

Revolut US CEO Cetin Duransoy reveals plans to target globally minded and “underbanked” Americans as it builds toward becoming a primary bank.

After receiving conditional approval from the U.S. Office of the Comptroller of the Currency for a national bank charter, Revolut Technologies Inc. appears ready to launch a full-scale challenge to traditional banks and fintechs in the United States.

After relatively quick growth in France, Spain, and Italy, Revolut aims to bring its superapp model to the U.S., where it doesn’t exist in quite the same form.

Revolut’s U.S. CEO, Cetin Duransoy, who has held senior roles at Raisin, Fundbox, Visa, and Capital One, spoke with Global Finance about Revolut’s plans for the American market. 

Global Finance: In the US, banks, fintechs, brokerages, travel products and payment apps are mostly separate. Does that surprise you? Do you see a genuine hole in the U.S. market for a company that combines all those relationships in one place?

Duransoy: It’s not surprising, given how complex these products are and how crowded and fragmented the U.S. market is. Layer on the regulatory process, and combining all these product suites—banking, brokerage, FX, crypto, travel, and more—into a single company or app becomes genuinely difficult and, for most companies, not worth the effort.

We believe you need a genuinely differentiated product to succeed in this market, and we have identified an opportunity here. By bringing all these products into one platform, we can remove the friction customers typically experience when cobbling together services from multiple providers.

GF: People often say, “The U.S. banking market is different.” Different how, exactly? And how might those differences affect Revolut?

Duransoy: The US’s fragmented, charter-based regulation can be more cumbersome than the EU’s passporting model, and U.S. customers tend to rely more on credit than their European counterparts. But the U.S. provides certain advantages, including the U.S. card network and interchange system, which subsidize rewards; FDIC insurance; and consumer-protection laws, which create a trust threshold.

Our broad product offering, 80-million-user global network, and strong global brand allow U.S. to cater to the distinct challenges of the U.S. market and understand the challenges of U.S. distribution costs. By obtaining a national bank charter, we will be on par with traditional banks, with direct Fedwire/ACH access and lending capability.

GF: When Revolut enters the U.S. market more aggressively, should Americans expect something close to the European Revolut experience—or will the U.S. product necessarily look much more like a traditional American bank competing on deposits, credit cards and lending?

Duransoy: We are always focused on product-market fit for our customers, and the U.S. will be no different. We’ve publicly shared that we will bring the best of what Revolut offers and provide the products U.S. customers want most, including checking accounts, credit cards, installment loans, FX, and stablecoins. We’ll continue innovating to deliver a distinct, more productive experience for U.S. customers.

GF: One of the things that makes Revolut unusual in Europe is that it sits at the intersection of finance, travel and lifestyle. Is that model central to how you think about the US, or is America more of a banking opportunity?

Duransoy: Yes. Combining our lifestyle products with the financial services that have made Revolut so popular remains central to our thinking. And they’re a key differentiator in many of our markets. We expect these offerings to help make us a top-of-wallet card and strengthen customer retention.

GF: Why should someone with Chase, Amex, Venmo, Robinhood, and a good travel card move meaningful parts of their financial life to Revolut? What can you offer that those companies, individually or collectively, do not?

Duransoy: We recognize that inertia is a strong force when it comes to financial services and that a customer’s bank holds critical parts of their financial life, such as their mortgage or direct deposit.

What we offer is the ability to consolidate multiple products and services into a single interface and remove the friction our customers find frustrating with other services. Revolut’s broad-based platform allows customers to seamlessly access multi-currency spending without foreign transaction fees, instant global P2P, a combined debit/credit product, budgeting, digital assets, and investing, all without transferring funds between platforms or managing multiple accounts. That’s especially valuable for people who travel internationally, have cross-border family ties, or are underserved by traditional credit underwriting.

GF: Which types of lending will Revolut prioritize in the US?

Duransoy: We intend to initially prioritize unsecured and secured credit cards and installment loans.

GF: What does Revolut understand about the consumer relationship that you think many American banks and fintechs still lack?

Duransoy: We treat our global app as the product. We iterate quickly, aim for gamified engagement, and offer frequent feature releases, in contrast to most U.S. bank apps, which have slower release cycles.

We also build for financial lives that span borders and currencies, rather than assuming a single-currency, single-country customer. American banks were largely built for a domestic customer, and that assumption is increasingly out of step with a more mobile, globally connected population.

GF: Do you think Revolut is underestimated in the US? If so, why? Among those who are aware, what do people in the U.S. most commonly misunderstand about Revolut right now?

Duransoy: “Underestimated” is probably right now, largely because our independent U.S. bank doesn’t exist yet. So we’re still seen as a “European neobank” by most Americans. That undersells what we’ll be once we have a full national charter, FDIC insurance, and our full lending capabilities live.

The most common misunderstanding among those who do know the brand is that we’re simply a fintech or a travel debit card, rather than a company with an 80-million-user global base—including 1.4M in the US—and banking licenses now spanning the UK, France, Australia, Mexico, and more.

GF: Are you coming to the U.S. to compete for a small slice of the market, or do you ultimately believe Revolut can change what Americans expect from a bank?

Duransoy: In the US, our near-term goal is to compete for market share. No new entrant can reshape what an entire country expects from a bank on day one. That takes years of trust-building, especially post-charter, when FDIC insurance and regulatory scrutiny are new territory for us.

What we’re looking to do is win the demographics best suited to us, namely the internationally minded, underbanked-by-incumbents, and digitally native users.

GF: On the corporate side, what are Revolut’s corporate banking plans?

Duransoy: Revolut Business exists—and is a core focus for us—in the U.S. We expect this to continue and are excited to launch merchant acquiring within the first years of becoming a bank.

GF: If we revisit this in three years, what would need to be true for you to say that Revolut has successfully become a major U.S. bank?

Duransoy: Within three years, we expect to be a fully operating bank with real momentum. We won’t share specific customer or product numbers today, but we’re building for scale and a sizable U.S. customer base that treats us as their primary bank, not a secondary account. That’s the bar we’re setting for ourselves.

Source link

Major expansion planned for Sea Ranch Lodge along the Sonoma Coast

The Sea Ranch Lodge, a focal point of a Northern California getaway destination that blends minimalist design with the rocky shores and meadows of the Sonoma County coastline, might have a growth spurt in its future.

Owners of the Lodge at Sea Ranch, which includes 17 hotel rooms, on Sept. 3 presented neighbors in the closely restricted community with plans that include 23 added guest rooms, a dining courtyard, a new dining space, a library and a “space for relaxation and movement.”

The Danish architecture firm BIG: Bjarke Ingels Group and San Francisco-based landscape architects Lutsko Associates are part of these plans. To become reality, however, those plans need to win design approval and permits from the Sea Ranch Assn. (which includes the lodge and surrounding homes) and Sonoma County.

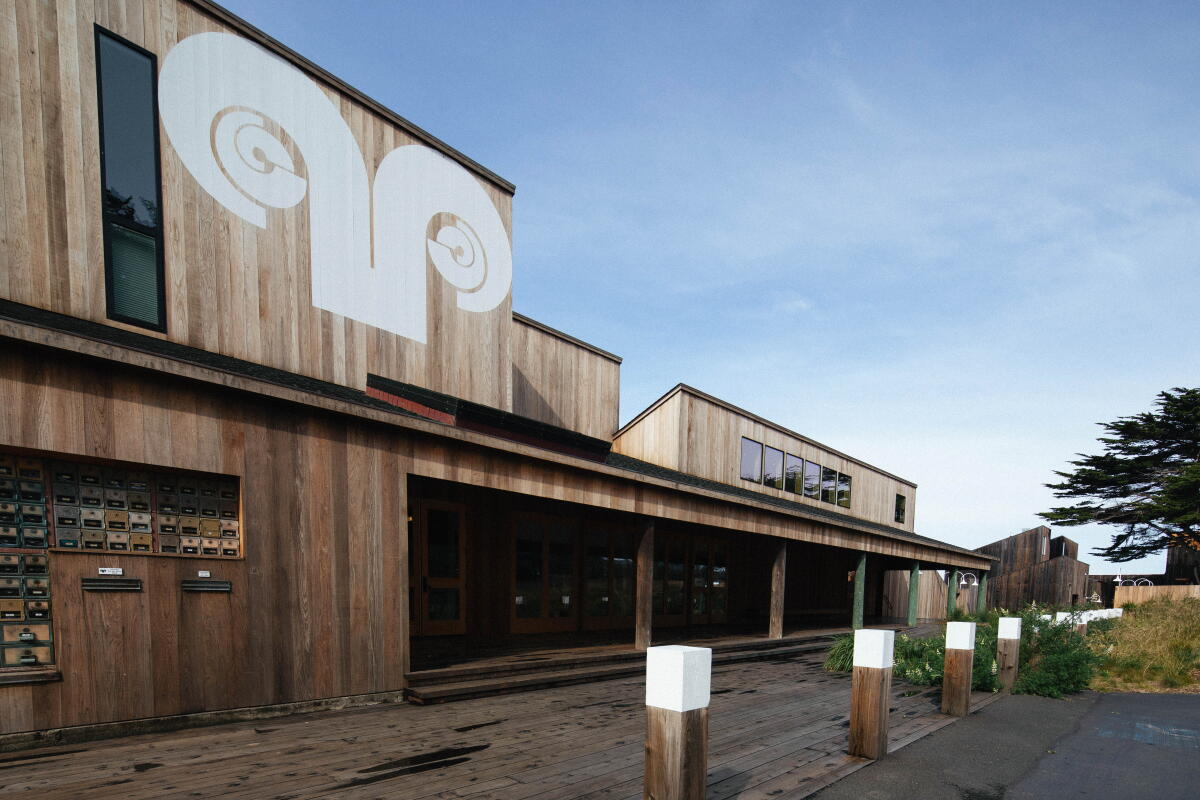
The ram's horns at the Sea Ranch Lodge.

The ram’s horns at the Sea Ranch Lodge were designed by artist Barbara Stauffacher Solomon.

(Myung J. Chun / Los Angeles Times)

The current owners of the lodge took over in 2018, completed a major renovation in 2023 and wish “to remain private,” a representative said. The Wall Street Journal has reported that the investors’ group includes San Francisco-based brothers Patrick and John Collison, who founded the tech company Stripe; venture capitalist Robin Chan; and Twitch co-founder Justin Kan.

The 53-acre lodge property is only one piece of the Sea Ranch puzzle. The surrounding development, which broke ground in 1964, includes about 2,200 homes and lots on roughly 7,000 acres, all subject to strict design standards enforced by the Sea Ranch Assn.

The homes, mostly clad in wooden exteriors, none more than two stories high, are scattered along 10 miles of coastline about 100 miles north of San Francisco. The nearest town is Gualala, about six miles north.

Rooms at the Sea Ranch Lodge often rent for $600 nightly or more. Many visitors rent neighboring Sea Ranch homes from Airbnb, Vrbo or local companies including Gualala-based Sea Ranch Rentals and Sea Ranch Escape. In fall, rental rates for homes often start around $400 nightly.

Widely praised as an model for environmentally sensitive building, the development sparked a years-long legal battle over public access to the coast. The result is a combination of private and public access: Six public-access trails cross Sea Ranch to on their way to the shoreline, while Sea Ranch residents retain access to several private beaches.

An ocean view along the trails at The Sea Ranch Lodge.

An ocean view along the trails at the Sea Ranch Lodge.

(Myung J. Chun / Los Angeles Times)

Source link