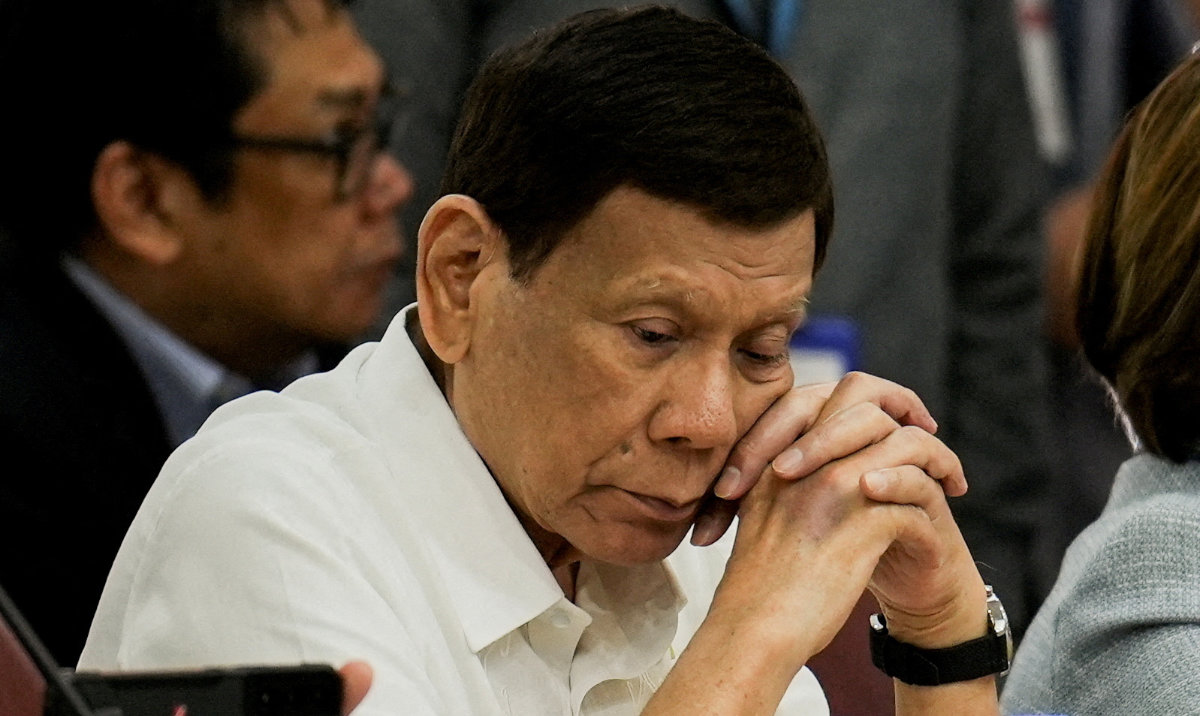
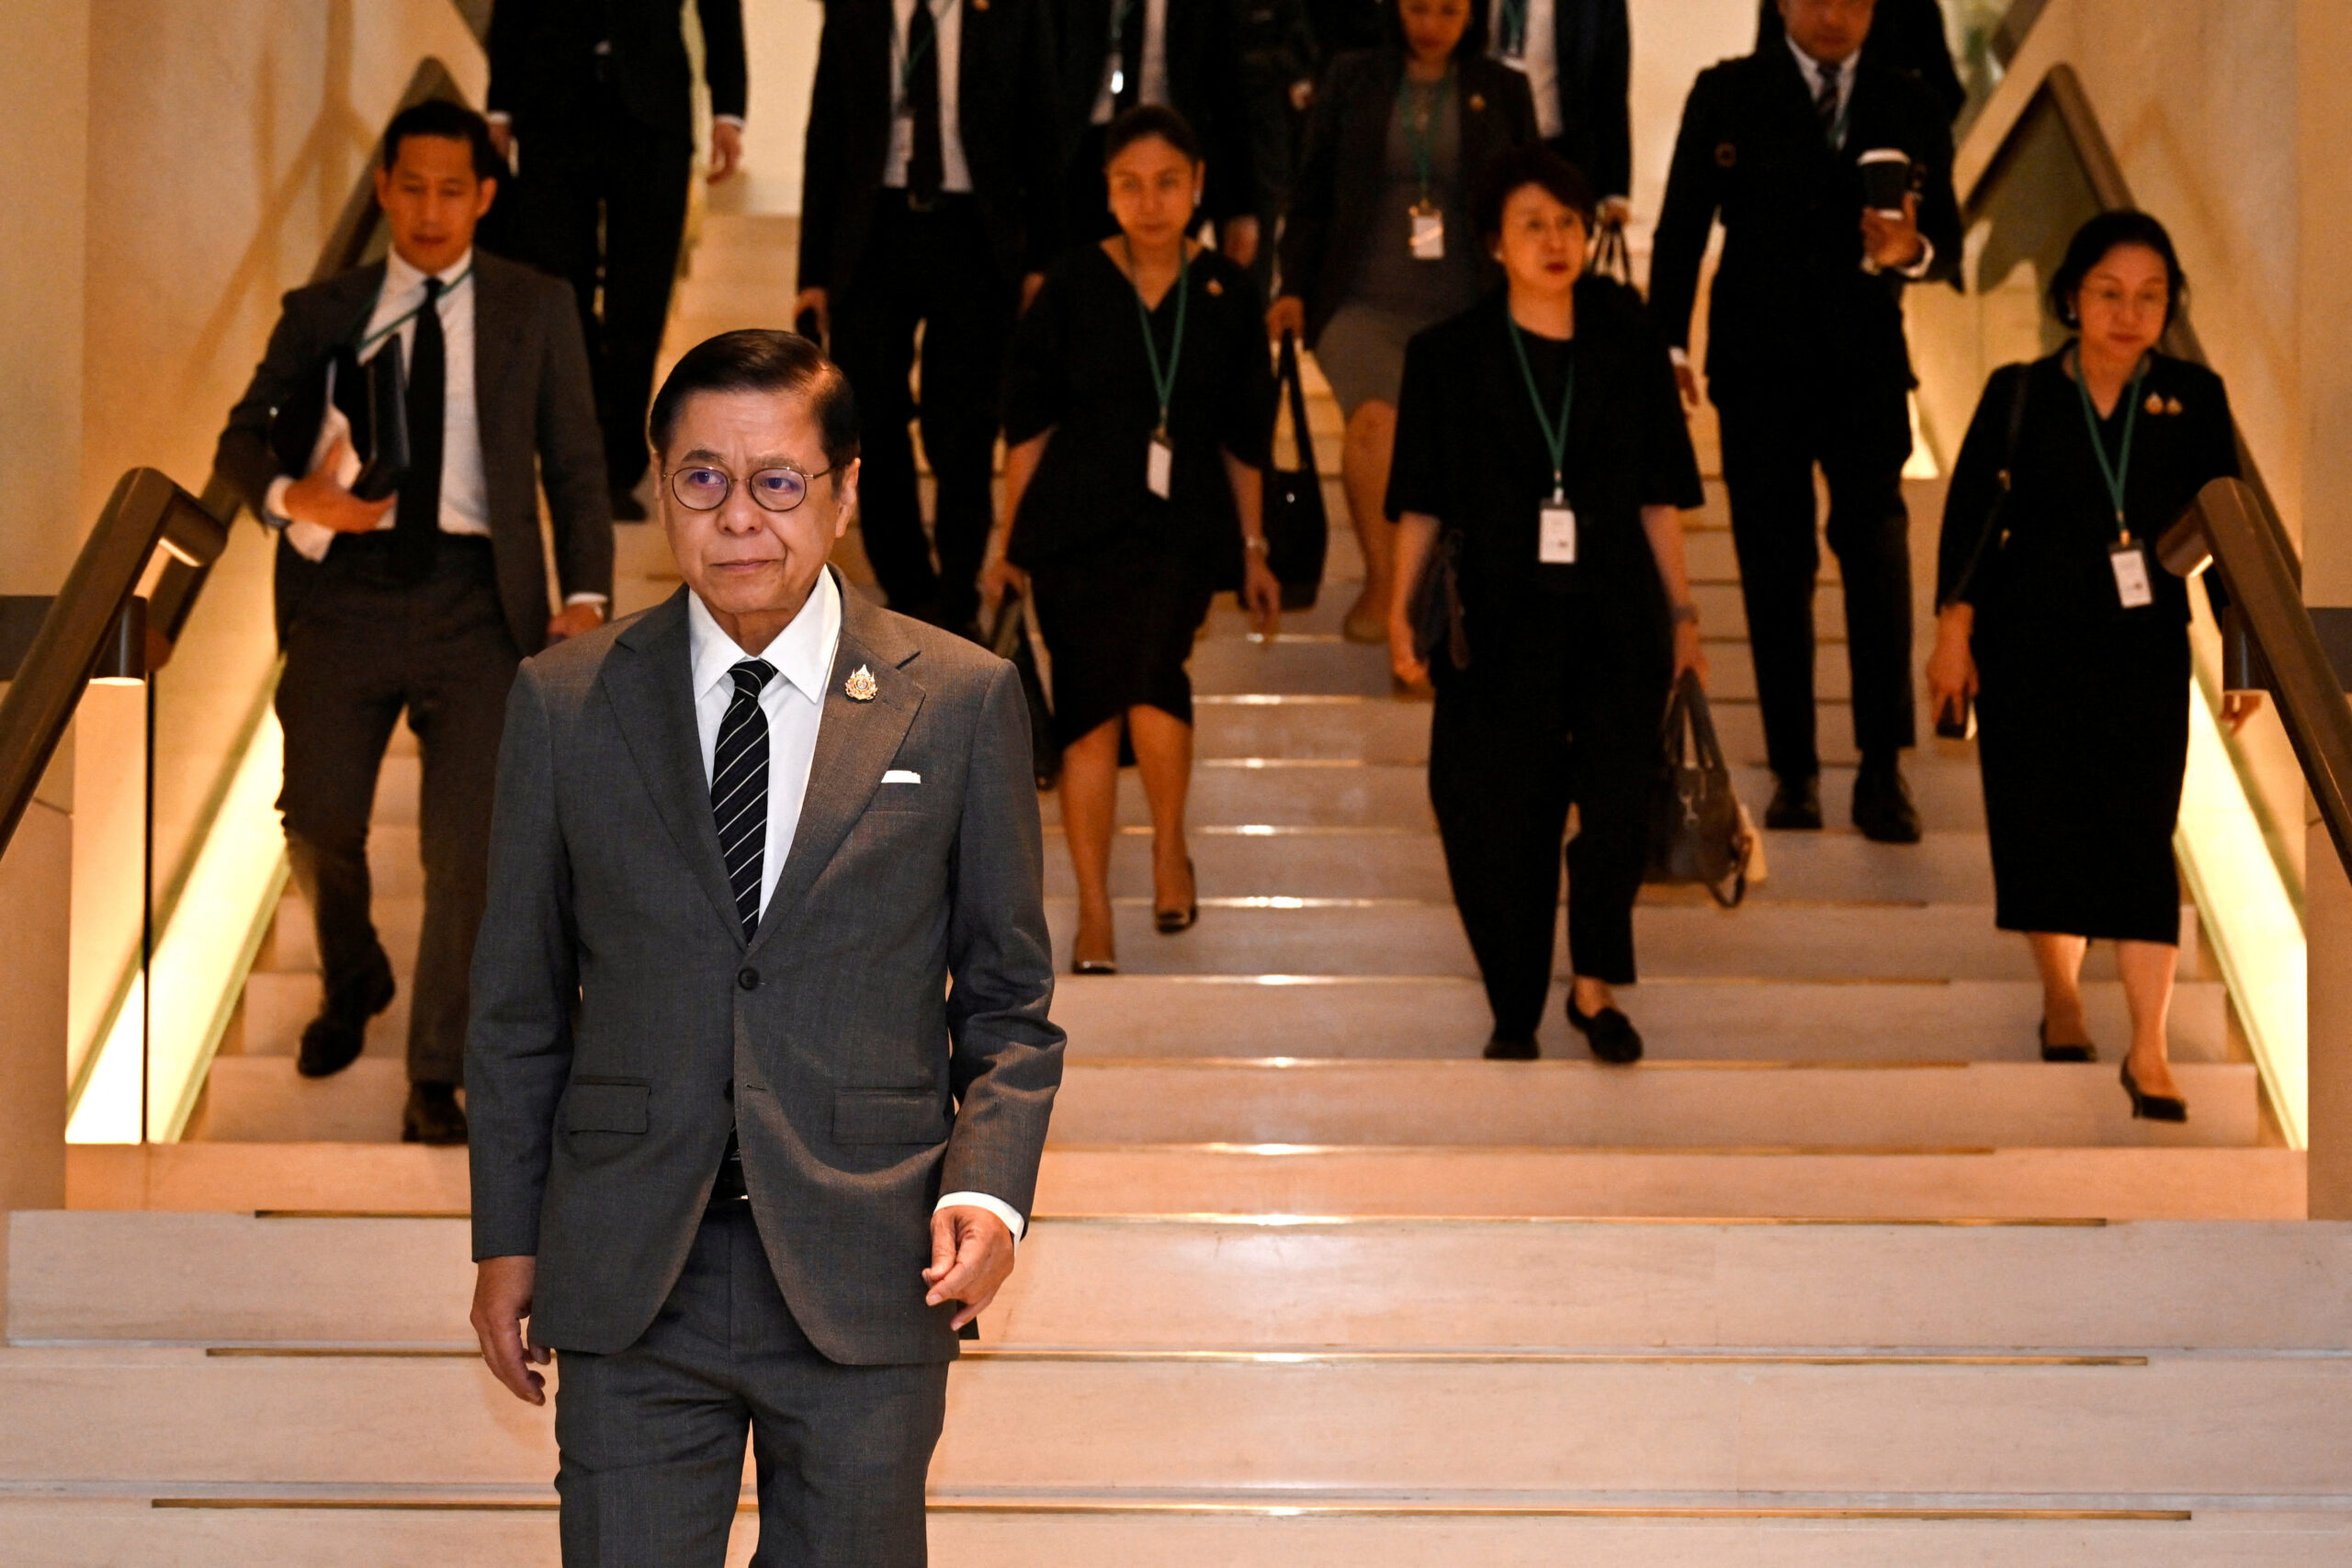
THE HAGUE, Netherlands: Former Philippines president Rodrigo Duterte is expected to appear in public for the first time on Wednesday since being transferred to the International Criminal Court 18 months ago to face murder charges related to his war on drugs.
Duterte, 81, served as president from 2016 to 2022, before being charged with crimes against humanity for creating, funding and arming death squads that targeted narcotics peddlers and users. He was arrested and taken to The Hague in March 2025.
On Wednesday, judges will hear arguments about his health and ability to stand trial, which is scheduled to begin in November. His lawyers have argued that he suffers from cognitive decline and is not well enough.
Duterte’s lawyer and family did not respond to requests for comment.
ICC judges said in January that Duterte’s health was good enough for him to follow proceedings and requested his presence in court, rather than by video link from the detention unit.
Duterte’s warrant says he was responsible for a widespread and systematic campaign that led to thousands of killings between 2011 and 2019, including when he served as mayor of the southern Davao city.
ICC prosecutors have said as many as 30,000 people may have been killed in the crackdown, the details of which were reported in a Reuters investigation.
According to police, 6,200 suspects were killed during anti-drug operations. Duterte said he instructed police to act in self-defense and told supporters he was ready to “rot in jail” if it meant ridding the Philippines of illicit drugs.
Currency reforms, liquidity pressures, and new payment rails are forcing African CFOs to rethink corporate strategy.
This article appears in the September 2026 issue of Global Finance Magazine.
When Nigeria liberalized the naira in June 2023, something of a chain reaction began across Africa. Egypt sharply devalued the pound in March 2024 under a reform program supported by the International Monetary Fund, and Ethiopia dismantled decades of foreign-exchange controls four months later. Headlines focused on inflation, exchange-rate volatility, and political fallout.
Inside multinational boardrooms, however, another conversation was quietly taking shape.
Where should liquidity be held? CFOs and corporate treasurers asked. Can capital still be repatriated efficiently? Is local-currency borrowing now preferable to offshore funding? And should Africa continue to be managed as dozens of fragmented financial markets, or, increasingly, as one integrated treasury landscape?
The answers are reshaping one of the least visible—but most strategically important—functions within multinational companies.
“Treasury efficiency has shifted from a secondary consideration to a first-order determinant: often the binding constraint, even when infrastructure and trade fundamentals appear sound,” said Phumlani Majozi, executive director of the African Markets Institute (AMI). “The logic is straightforward; multinationals prefer an environment where it’s easy to extract their capital when they need it.”
His observation reflects a profound shift in corporate thinking.
For decades, multinational companies evaluated Africa through a familiar lens: market size, consumer demand, infrastructure, labor costs, and political stability. More often nowadays, the decisive consideration is whether capital itself can move efficiently across the continent.
Treasury as Investment Influencer
Phumlani Majozi, African Markets Institute
The timing is significant.
Lending to Africa by China’s two principal policy banks has fallen dramatically, from US$28.8 billion in 2016 to US$2.1 billion in 2024, according to the Boston University Global Development Policy Center. As governments rely more on commercial finance and private capital to fund development, multinational companies have assumed greater responsibility for financing projects and managing liquidity across multiple jurisdictions.
The African Development Bank estimates that the continent requires some US$170 billion annually to finance infrastructure, but currently attracts only US$80 billion to US$90 billion, leaving a financing gap approaching US$80 billion each year. Against that backdrop, treasury has moved from supporting investment decisions to influencing them.
“The biggest change is that the treasurer is now expected to do far more than manage cash, funding, banking, and risk,” said Mike Richards, founder and CEO of The Treasury Recruitment Company. “Those things remain essential, but today’s treasurer is expected to help the CFO and the board understand what is happening, what the risks are, and what decisions need to be made.”
That evolution is especially evident across Africa.
Unlike Europe or North America, treasury teams operating on the continent must simultaneously navigate 54 sovereign jurisdictions, more than 40 actively used currencies, multiple exchange-rate regimes, and a complex web of banking regulations and capital controls. A finance executive overseeing operations stretching from Lagos to Nairobi and Johannesburg to Cairo may confront four entirely different monetary environments before the workday begins.
One subsidiary may hold surplus cash that cannot easily be repatriated because of foreign-exchange restrictions. Another may require emergency liquidity but operates in a market where access to hard currency remains constrained. Exchange-rate swings can rapidly inflate import costs or reduce earnings when profits are translated into dollars or euros.
“A company may appear to have plenty of cash across the group,” Richards said, “but that does not mean the cash is in the right place, in the right currency, or can be moved when the business needs it.”
That vexatious reality has become one of the defining operational challenges facing multinational companies in Africa. Because more companies are operating across the continent, treasury departments increasingly see fragmented pools of capital, each governed by different regulations, currency regimes, and banking systems.
These inefficiencies impose what amounts to a hidden investment tax, Majozi argues.
“When currency convertibility is uncertain,” he said, “intra-African capital movement is fragmented across more than 40 regulatory regimes, and hedging instruments for smaller African currencies are thin or nonexistent. Treasurers price in a liquidity-trapped capital discount before operational returns even enter the model. That discount frequently outweighs what improvements in infrastructure or regulation can offset.”
Mike Richards, Treasury Recruitment
Technology is helping treasury teams respond.
“We have seen treasury teams become more data-driven in their analysis and execution of currency risk-management programs,” said Bob Stark, global head of market strategy at Kyriba. Greater visibility into balance-sheet and cash-flow exposures, he added, has enabled companies to strengthen natural hedging while making more efficient use of forward contracts and options.
AI is the logical next step.
“There is no AI strategy without a data strategy,” Stark said, noting that multinational companies are investing more in API-enabled treasury platforms that provide real-time tracking of liquidity, foreign-exchange exposure, and banking relationships across multiple African markets.
“The primary benefit of treasury management systems for African treasury teams remains improved visibility and forecasting that unlock and mobilize trapped cash,” he said.
Toward Regional Financial Integration
Regional treasury hubs are also becoming more important. Rather than allowing every subsidiary to manage liquidity independently, multinational companies are consolidating treasury oversight in centers such as Johannesburg, Dubai, and Casablanca, where funding, foreign-exchange management, and banking relationships can be coordinated across multiple jurisdictions while maintaining local execution teams.
Richards recently recruited a senior treasury executive who helped establish a regional treasury center covering 16 African countries, centralizing foreign-exchange management, implementing cash-pooling arrangements, and negotiating local funding facilities across markets including Nigeria and Zambia.
“It is no longer enough to understand treasury technically,” he said. “You also need to understand the markets, the business, and the people operating locally.”
The next stage of evolution may be driven by regional financial integration.
“PAPSS solves a concrete, costly problem,” said Majozi. “Settling directly in local currencies cuts both cost and delay.”
Implementation remains uneven, he cautioned: “Multinationals will likely treat Africa-as-one-market as an aspiration for another five to 10 years, not a current operating reality.”
The direction of travel, however, is unmistakable. Africa’s abundant natural resources, favorable demographics, and expanding consumer markets will continue attracting global investors. Still, sustaining those investments will increasingly depend on modern financial infrastructure.
“Natural resources and favorable demographics may attract initial boardroom attention,” said Majozi. “But sustained, large-scale operational commitments depend on institutionalized monetary predictability, transparent capital flows, and efficient regional financial infrastructure.”
In Africa’s next chapter of economic integration, the competitive advantage may belong not simply to companies that understand the continent’s consumers, but to those that master the sophisticated movement of capital across its markets.
Charles Wachira is a contributing writer based in Kenya.
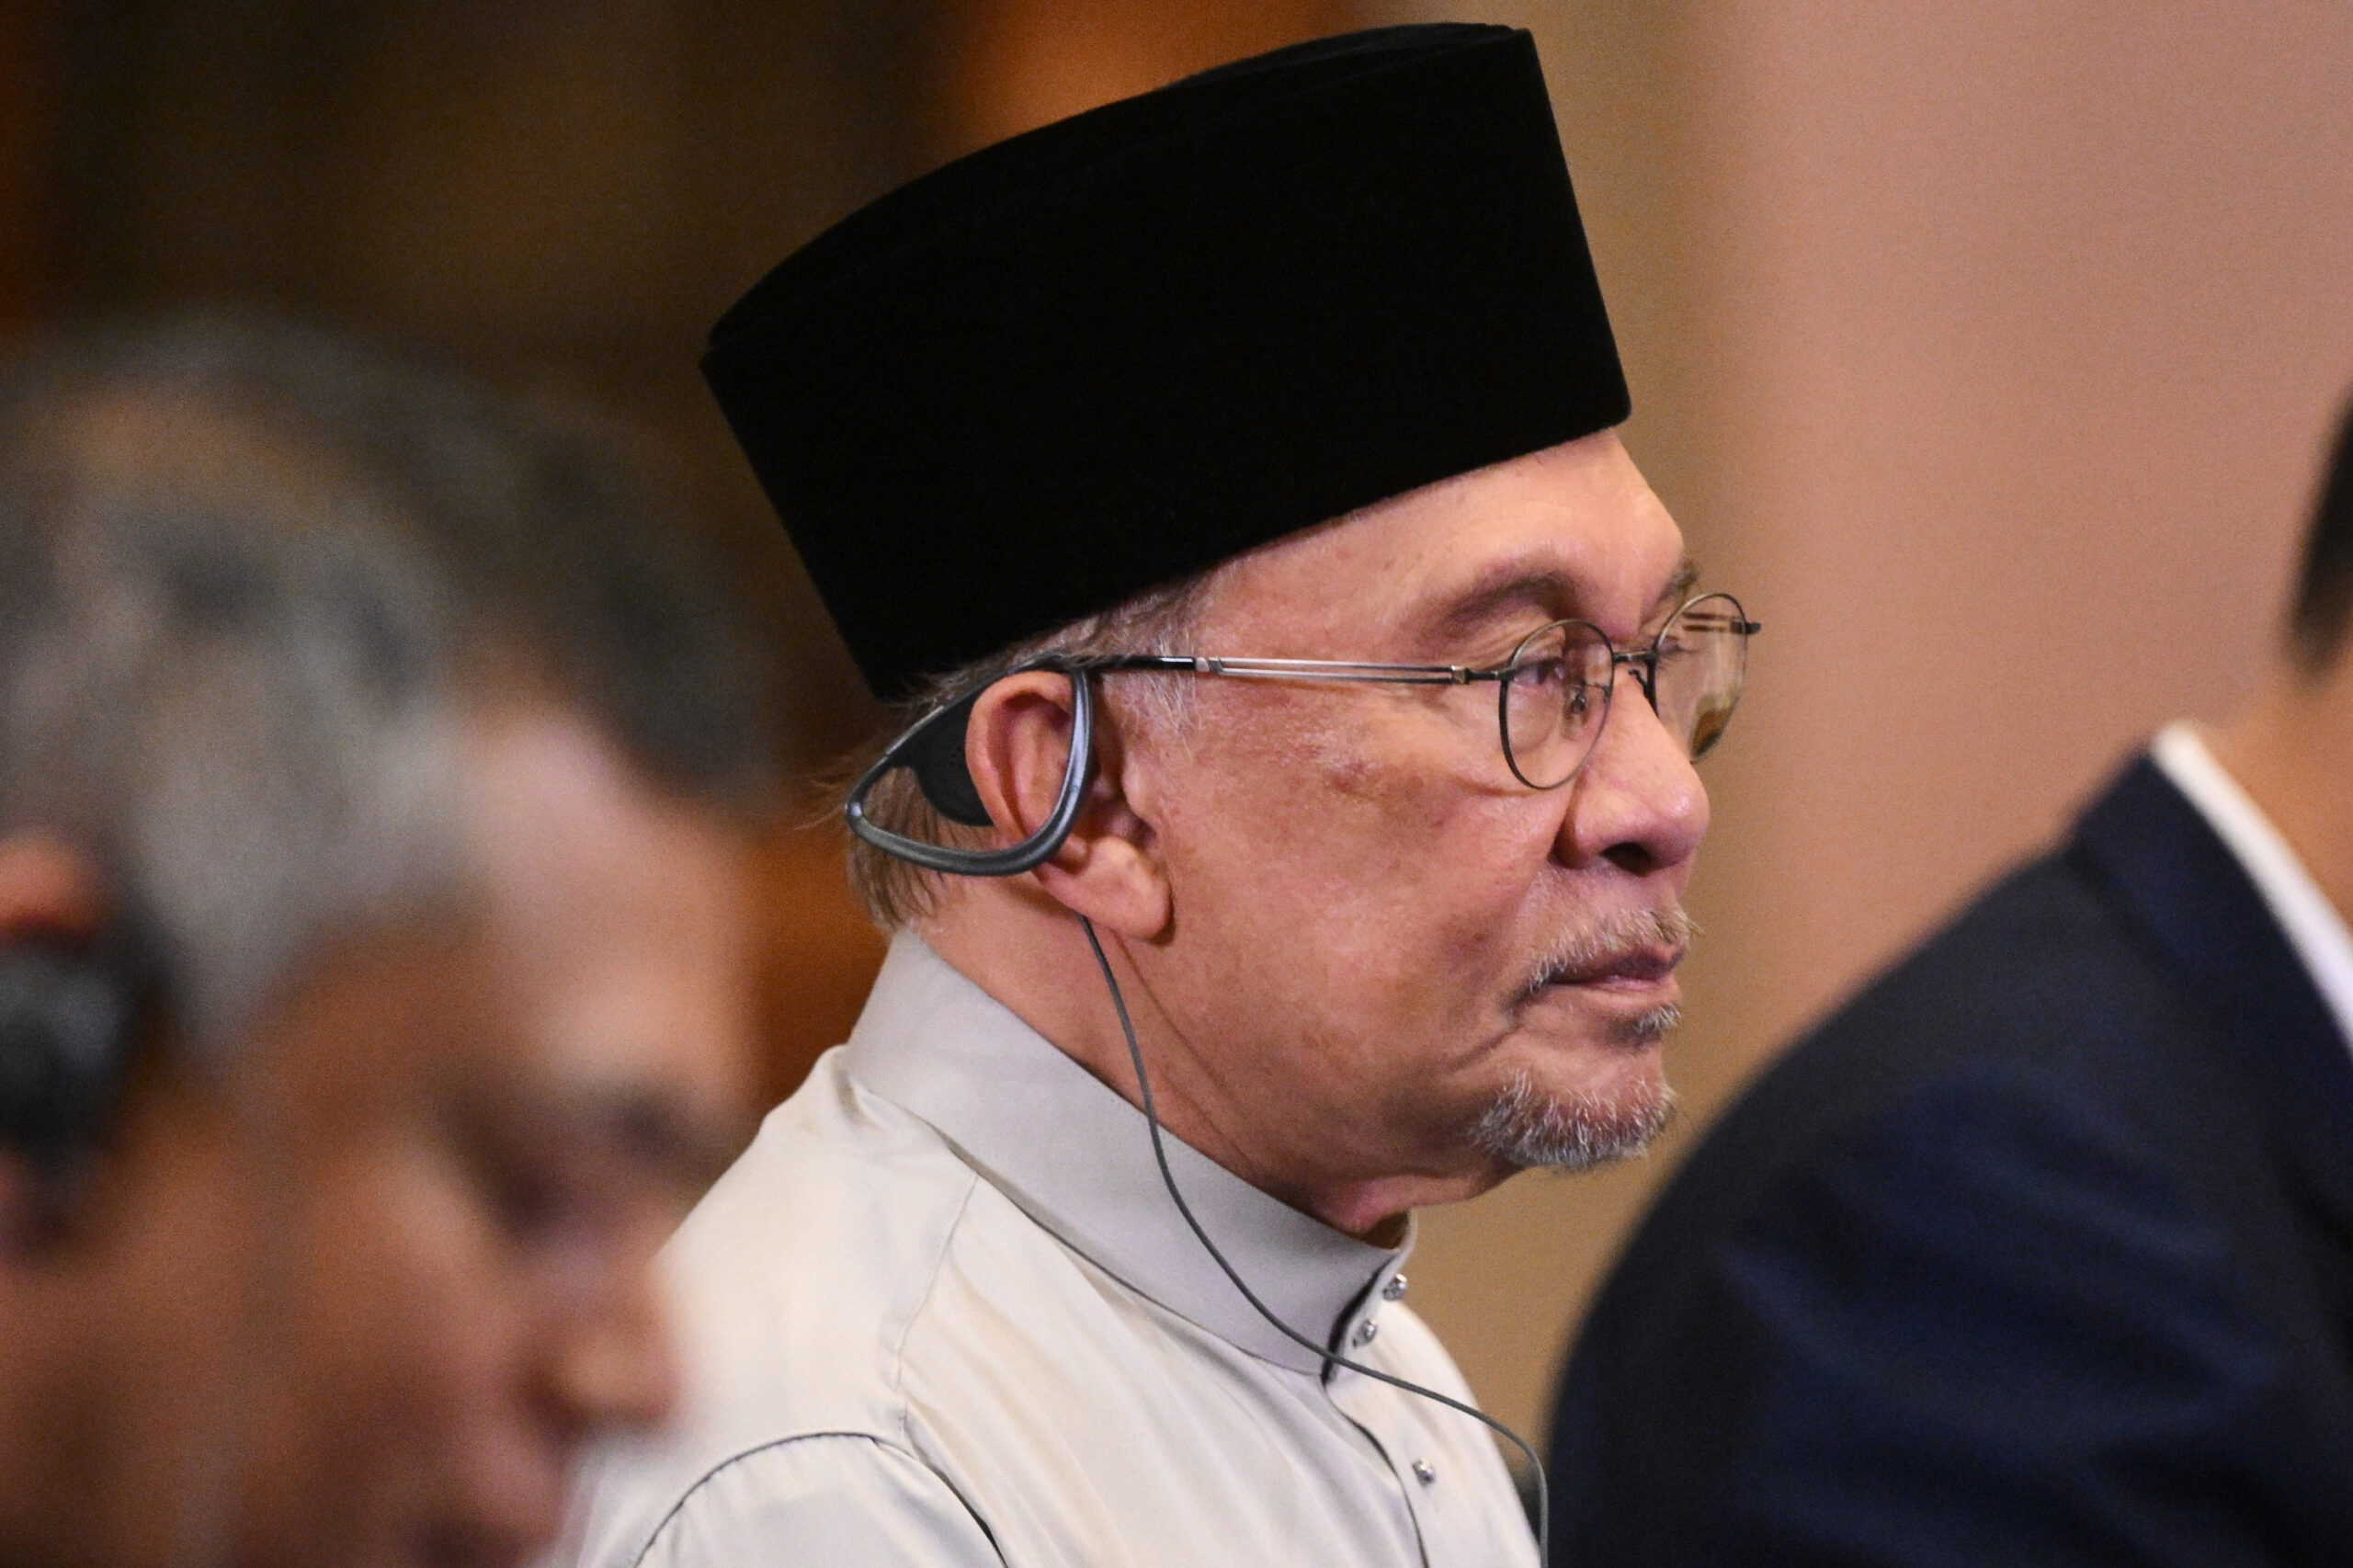
LONDON: Prime Minister Anwar Ibrahim vowed on Tuesday that shipments to Israel’s military would not be allowed to pass through Malaysia after cargo containers heading there were seized.
His comments came after Bloomberg reported that Malaysian authorities had halted all shipments heading to Israel from one of the country’s largest ports after three containers were stopped by authorities last month.
“We will not allow our country to be used as a conduit for any shipment that supports or contributes to Israel’s military capabilities and its atrocities against Palestinians and other innocent lives,” Ibrahim wrote on X.
“Any suspicious shipment will be subject to inspection and investigation in accordance with Malaysian law. Where a violation is established, decisive action will be taken.”
The three containers were stopped at Tanjung Pelepas Port on Aug. 19 and have been held ever since, the report said.
They were destined for Israel’s Ashdod port and contained products from China.
Malaysia has no diplomatic or trade relations with Israel, but cargo is allowed to transit through the country’s ports from one country to another.
Bloomberg reported that the seizure could be a shift in Malaysia’s approach to handling Israel-bound cargo.
Malaysia is a major shipping hub, located along some of the world’s busiest maritime routes through Asia.
The Malaysian Border Control Agency said the matter remains under investigation.
The seizure came just two weeks after a container destined for Israeli military technology company Elbit Systems from the Philippines was also stopped in Malaysia.
Malaysia has been one of the most prominent international critics of Israel and, in particular, the war on Gaza.
At the BRICS Summit in New Delhi at the weekend, Ibrahim condemned what he described as Israel’s “settler terrorism” in the occupied West Bank.
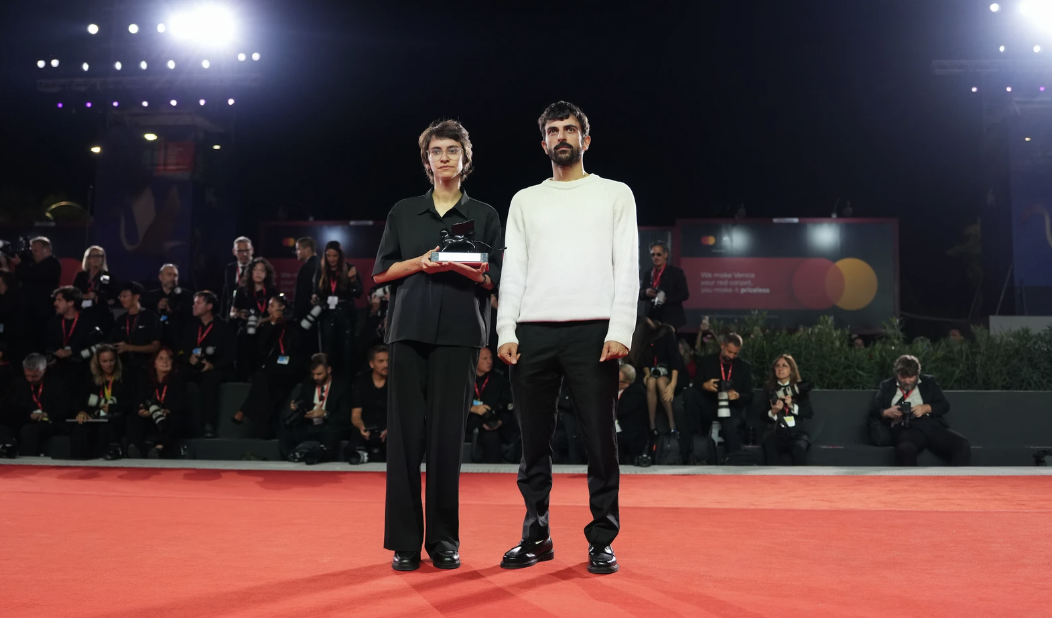
LONDON: Film festivals and filmmakers around the world have rallied around the directors of the Gaza documentary “NAZA,” after an Israeli minister accused them of treason and threatened to revoke their citizenship.
Israeli filmmakers Yuval Abraham and Rachel Szor have faced mounting criticism from officials in Israel since their documentary, which documents Israeli military operations in Gaza, and in particular the killing of civilians, won the Special Jury Prize at the Venice Film Festival at the weekend.
Israel’s minister of culture and sports, Miki Zohar, said he would “act immediately” to revoke the citizenship of the filmmakers, accusing them of “treason against the state.”
The film, produced by The Guardian newspaper, features testimonies from 24 Israeli military and intelligence personnel about the use of AI-powered targeting systems in Gaza. It builds on investigations published by Israeli media outlets +972 Magazine and Local Call, as well as Guardian news reports.
The threats against the directors prompted a broad response from the international film community, with the directors of the Telluride, Locarno, Berlin and San Sebastian film festivals among those expressing support.
Julie Huntsinger, artistic director of the Telluride Film Festival, said that threatening the filmmakers’ citizenship was “unacceptable” and that the issue “should be condemned by any thinking human.”
The Berlin International Film Festival’s director, Tricia Tuttle, said artists must be free to examine events critically, and argued that in a democratic society the response to films should be “dialogue and scrutiny, not intimidation or punishment by the state.”
More than 1,500 Israeli filmmakers signed a petition backing Abraham and Szor, and rejecting the accusation that they sought to damage Israel’s international reputation. The petition warned that the campaign against them was moving toward rhetoric that could effectively sanction violence and pose a threat to their lives.
Abraham and Szor won an Oscar last year for their documentary “No Other Land”, made in partnership with Palestinian filmmakers Basel Adra and Hamdan Ballal, which examined Israeli settler violence against Palestinian communities in the occupied West Bank.
The Israeli military has rejected claims “NAZA” makes about its operations, saying they were based on anonymous sources that could not be independently verified.
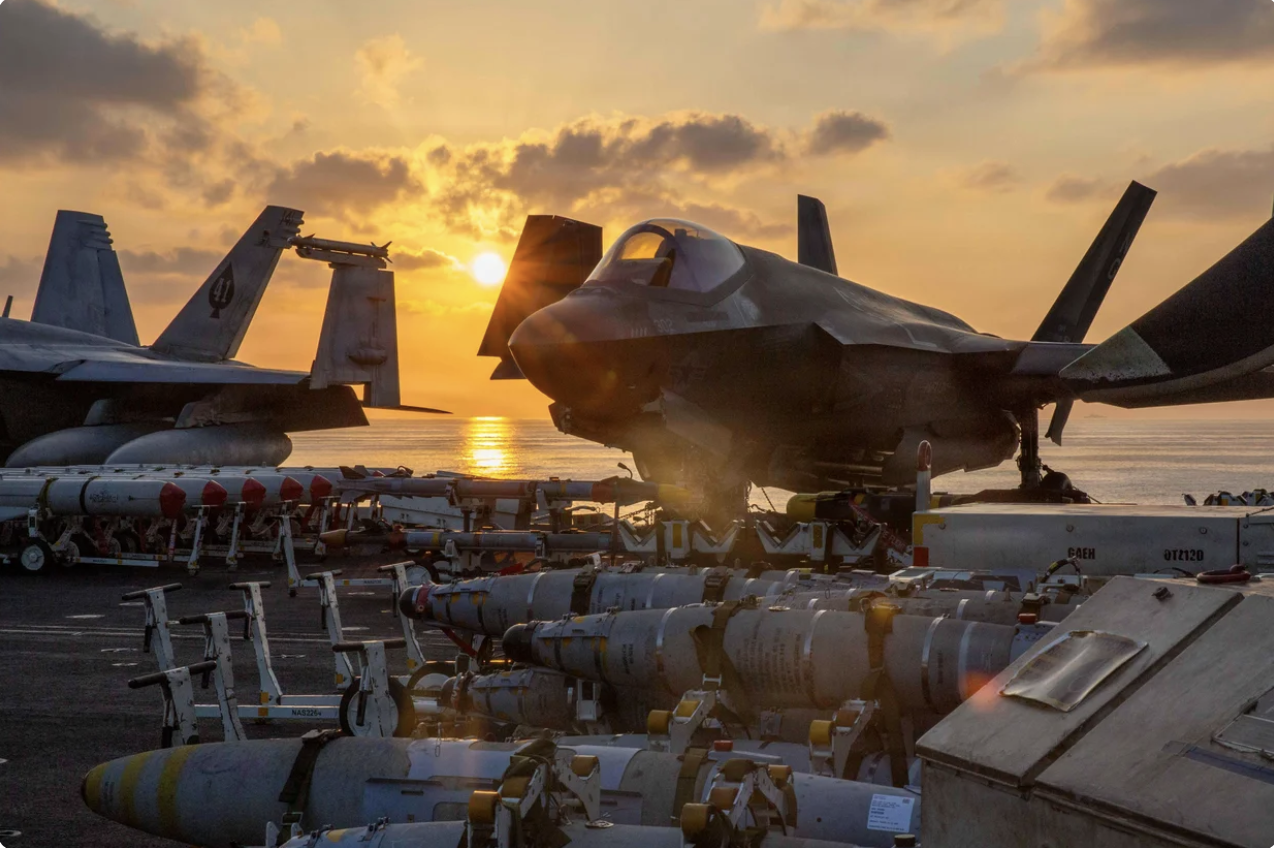
WASHINGTON: President Donald Trump’s administration is planning to sell to Israel a munitions package worth $2.8 billion, which will include tens of thousands of highly destructive 2,000-pound bombs, according to a US official familiar with the sale.
The planned sale, which has been informally communicated to relevant congressional committees who weigh in on large arms sales, includes 20,000 MK 84s and 20,000 BLU-117s, the official, speaking on the condition of anonymity, said.
News of the package was first reported by the Washington Post.
The State Department and the Israeli embassy did not immediately respond to a request for comment.
US public support for Israel has fallen since the Gaza war began in 2023, particularly among Democrats. A June Quinnipiac University poll found 48 percent of voters and 66 percent of Democrats believe the United States is too supportive of Israel, up from 16 percent and 20 percent when the question was first asked in 2017.
The 2,000-pound bombs have been regularly used by Israel in Gaza as well as in Lebanon, drawing scrutiny from rights experts. More than 73,000 Palestinians have been killed in Israel’s military campaign, according to Gaza health authorities. A UN inquiry determined that Israel had committed genocide in Gaza, a charge Isarel rejects.
Israel calls its actions self-defense, after Hamas-led militants killed 1,200 people and took more than 250 hostages in an October 2023 attack.
The US and Israel attacked Iran on February 28. Iran responded with its own strikes on Israel and Gulf states that host US bases. US-Israeli strikes on Iran and Israeli attacks in Lebanon have killed thousands and displaced millions.
In a document sent to EU legislators and seen by Euronews, the US has threatened the EU with retaliation if it does not scrap European preference provisions in its multiannual budget.
ADVERTISEMENT
ADVERTISEMENT
EU member states are currently discussing the EU’s long-term budget (2028-2034), which includes a €402 billion fund dedicated to competitiveness that favours the production of key goods within the EU, including in defence.
The measure would potentially exclude foreign firms from EU financing to protect strategic and economic security interests.
“With further expansion of European preference measures in EU defence funds, the United States will review all potential response measures, including a rollback of the existing ‘Buy American’ blanket waivers and exceptions associated with the RDPAs [Reciprocal Defence Procurement Agreements] with 19 of the 27 member states,” the non-paper reads.
The Buy American Act requires the US government, including the US Department of Defence, to give preference to products manufactured in the US for certain public procurements, with some exceptions being granted in defence for some EU countries.
The non-paper adds that the European preference would impede “partnership” and “collaboration” with the US, and calls on the EU to introduce a “made with Europe” system – or, in the specific area of defence, a “made in NATO”.
Trade tensions
The US’s latest warning comes after the creation of the Security Action for Europe programme in 2025, already sparked trade tensions between Washington and Brussels over a European preference for joint purchases of arms and military equipment.
The “made in Europe” approach is also pushed by France and the European Commission in several pieces of legislation over the last year designed to boost EU industry, with foreign countries lobbying hard against being excluded from the EU market.
The US and EU have been at loggerheads over trade since the start of the second Trump administration, amid repeated tariff threats and disputes over environmental and digital regulations which the White House deems to be non-tariff barriers.
The Commission hoped that the conclusion of a trade agreement in July 2025 would be a step towards a more stable transatlantic relationship.
RIYADH: Saudi Arabia has surpassed its goal of training 1 million people in AI through a new initiative that embeds ethical use and safety standards into national skilling programs
Speaking at the 4th UNESCO Global Forum on the Ethics of AI in Riyadh, Ahmed Al-Ghamdi, CEO of the Saudi Data and AI Authority’s capacity building sector, said: “We launched SAMAI (One Million Saudis in AI initiative) last year to train 1 million in AI, raise awareness and provide them with the knowledge and skills to use AI in life and in their work.
“We trained more than that number and an important part of the training focused on ethical AI, responsible use and data preservation,” he told Arab News.
The UNESCO forum is co-hosted by Saudi Arabia, represented by the SDAIA and the International Centre for AI Research and Ethics.
Al-Ghamdi said that the forum had brought together more than 25 ministers from around the world, as well as global leaders and tech companies under the umbrella of UNESCO to shape the future of AI safety and responsible use.
SAMAI was part of a broader push to invest in capability building across national sectors and entities, enabling them to develop the skills needed to adopt AI safely and effectively, he said.
“In SAMAI we provided training with knowledge on what data to show and what tools to use safely.”
Al-Ghamdi said that ethical AI was positioned as a core element across the SDAIA’s training programs and frameworks, rather than a standalone topic.
The authority announced national frameworks and curricula for AI in January as part of efforts to align education pathways with national needs.
Additional capacity building frameworks were also announced at the International Conference on Data and AI Capacity Building, aimed at professionals, educators and training programs to support wider adoption across the economy, Al-Ghamdi said.
“For example, for the developers it includes training the right model on the right data, avoiding bias, and not using AI for fraud or any violence,” he said.
“It includes respecting the data privacy of people and organizations and complying with data laws within the country and within the world.”
The pace of AI advancement had raised the stakes globally, making governance and ethics central to discussions about safe deployment and public trust, he said.
“The ethics of AI comes in the heart of all activities of capability building in SDAIA. We believe the ethical use and the safety of AI are a priority for us.”
Fund managers have shifted their primary market worry. Bank of America’s September Global Fund Manager Survey, which polled 170 investors overseeing $470B in assets now ranks a disorderly rise in bond yields as the top tail risk.
Government bond markets remain under pressure as rising energy prices revive inflation concerns and increase expectations that major central banks will keep interest rates higher for longer.
ADVERTISEMENT
ADVERTISEMENT
The benchmark 10-year US Treasury yield briefly touched 5.011% on Monday, according to Dow Jones Market Data, before falling back below 5%. The level was the highest since October 2023.
The yield crossed the psychologically important 5% threshold as higher government borrowing, resilient economic growth and heavy corporate debt issuance linked to artificial intelligence investment compounded pressure on US bonds. Yields move inversely to bond prices.
Rising Treasury yields can feed through to mortgages, corporate loans and other forms of credit, potentially slowing economic growth. They can also make bonds more attractive relative to highly valued equities.
The latest rise followed the US Treasury’s previously announced expansion of its bond-buyback programme. Last week, it offered to purchase up to $6 billion of debt maturing in 10 to 20 years – three times the previous operation’s size.
The yield on the 30-year US Treasury bond, meanwhile, remained close to its highest level since 2007.
The sell-off has also spread across Europe. France’s 10-year government bond yield rose to 4.50% on Monday, while the equivalent Italian yield reached around 4.40%.
Germany’s benchmark 10-year Bund yield climbed as high as 3.538%, according to Dow Jones Market Data, its highest level in 15 years.
Energy prices are a major source of pressure. Brent crude rose to around $107 a barrel on Tuesday morning, while US West Texas Intermediate traded close to $103, as attacks on Saudi energy infrastructure and shipping in the Gulf intensified concerns about supplies through the Strait of Hormuz.
The European Central Bank raised its deposit rate by 25 basis points to 2.5% last week and warned that inflation could remain above its target for an extended period. Markets are pricing in at least one further ECB increase this year.
Attention now turns to three major central-bank decisions. The US Federal Reserve announces its decision on Wednesday, followed by the Bank of England on Thursday and the Bank of Japan on Friday.
A Reuters poll found that 85% of economists expected the Fed to raise rates by 25 basis points, while money markets placed the probability of an increase at around 93%.
The BoE is widely expected to leave rates unchanged. Economists surveyed by Reuters unanimously forecast no change, although some analysts have warned that a surprise increase cannot be ruled out. The BoJ is widely expected to raise borrowing costs.
RIYADH: David Livingstone, chief client officer at Citigroup, believes investor appetite for Saudi debt issuances reflects confidence in the Kingdom’s long-term story, while Gulf countries remain capable of maintaining their positive performance in debt markets despite higher yields and increased global supply.
Livingstone said in an interview with Nour Amache on the “East-West” program on Asharq Business with Bloomberg that the performance of Saudi sovereign issuances, as well as those of the Public Investment Fund, demonstrated the resilience of Saudi Arabia’s market and continued demand from international investors, despite the obstacles created by the Iran war this year.
Livingstone’s comments came after the Kingdom raised $3.25 billion through international sukuk in early September, attracting orders of around $16.5 billion, or more than five times the issuance size. Saudi Arabia tightened the pricing spread by about 30 basis points from the initial guidance.
The Citigroup head added that the pricing adjustment “demonstrates confidence in this long-term story,” placing it within the context of the transformations underway in the Kingdom under Vision 2030.
The comments came after Citigroup helped its clients in Saudi Arabia raise more than $40 billion since the beginning of the year. The bank also decided to increase its direct exposure limits to the Kingdom after it demonstrated “strong economic and financial resilience,” according to CEO Fahad Al-Deweesh.
Debt-market pressures
Higher global yields and increased government borrowing will give investors a wider range of choices in the bond market, Livingstone said, noting upward pressure on yields amid abundant debt supply in emerging markets, Europe, the UK and the US.
Despite this, he said that “Saudi Arabia, and Gulf countries as a whole, can continue this positive performance compared with the recent past.”
Yasir Al-Salman, chief financial officer at the Public Investment Fund, told Asharq Business with Bloomberg that international debt markets would remain the fund’s largest source of financing. The fund had around SR3.4 trillion ($906.1 billion) in assets under management after injecting about SR750 billion into the Saudi economy over five years.
Debt instrument pricing in the Kingdom is linked to US bond yields, which have recently been elevated. The yield on the 10-year US Treasury continued to rise for a fifth consecutive session on Sept. 14, exceeding 5 percent, its highest level since 2023.
Are investors affected by project reviews?
Asked about the effect of media reports concerning the postponement or reassessment of some projects in Saudi Arabia on foreign investor appetite, Livingstone said this did not change the fundamental basis of investor interest in the Kingdom. He said economic diversification remained “the attractive factor for investors,” as infrastructure development and projects connected to the economic transformation continued.
He added that the review was “justified” in light of the economic circumstances surrounding the projects being financed, with attention focused on their feasibility and sustainability.
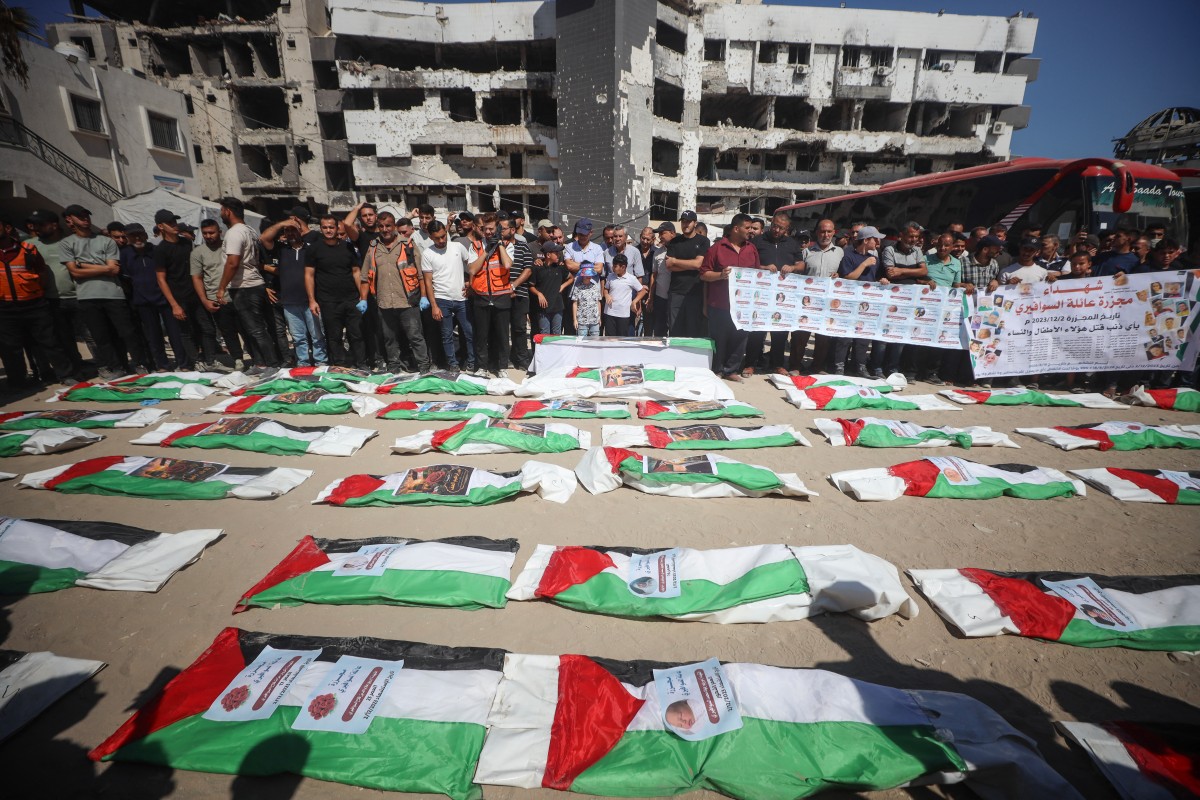
Geneva: The United Nations called Tuesday for international investigators to be granted to access to all of Gaza “to assist with evidence-gathering” as hundreds of bodies are pulled from the rubble.
“The discovery of extensive remains under the rubble in Gaza City resurfaces these concerns of war crimes and other atrocity crimes,” UN rights chief Volker Turk said in a statement.
SINGAPORE: Thailand accused Cambodia on Tuesday of “playing the role of a victim” in a dispute over maritime resources, as the Southeast Asian neighbours brought their long-standing feud before international mediators.
The hearing at the Singapore outpost of the Permanent Court of Arbitration (PCA) comes after the countries fought two rounds of deadly border clashes last year.
In May this year, Thailand unilaterally pulled out of a framework agreement with Cambodia that aimed to resolve overlapping maritime border claims, but denied any link to their land dispute.
Cambodia subsequently initiated a UN-backed conciliation process at the PCA, saying it hoped to return to constructive negotiations.
Opening Bangkok’s case before a five-member panel of international legal experts, Foreign Minister Sihasak Phuangketkeow said Cambodia sought to “vilify Thailand through false narratives, distortion of facts, and unfounded accusations… including at international forums”.
“It does this by playing the role of a victim with a sense of self-righteousness aimed at claiming the moral high ground,” he said.
Last year’s clashes left dozens of people dead and displaced more than a million before a truce was agreed.
Thailand has said it withdrew from the framework agreement, called “MoU 44”, because “no progress had been made” in implementing it. Prime Minister Anutin Charnvirakul denied the move was linked to the fighting.
The 2001 memorandum of understanding covers a resource-rich maritime territory of around 27,000 square kilometres (10,500 square miles) to which both Cambodia and Thailand lay claim.
Cambodia said last week that it had resorted to conciliation “after Thailand unilaterally terminated the agreed bilateral framework” through which the two nations had “negotiated their overlapping maritime claims for more than two decades”.
Prime Minister Hun Manet said in June that the move was also to “protect Cambodia’s sovereignty and maritime rights in accordance with international law”.
Foreign Minister Prak Sokhonn told the PCA panel on Tuesday that Phnom Penh saw the process “as a means to rebuild trust, not as a form of escalation”.
Cambodia’s goal was to agree with Thailand on a “single, all-purpose maritime boundary”, or alternatively agree to jointly develop and equitably share resources until a boundary is drawn, he said.
“Cambodia sincerely hopes that Thailand will engage constructively in this process.”
Sihasak said Thailand was also seeking maritime delimitation and to rebuild trust.
Set up in 1899, the PCA is the world’s oldest intergovernmental dispute-resolution body and resolves disputes between countries and private parties by referring to contracts, special agreements and various treaties, such as the UN Convention on the Law of the Sea.
The PCA office in Singapore is the Hague-based court’s first in Asia.
The commission’s recommendations are not binding and will take about a year to be decided.
The U.S. Environmental Protection Agency said Monday it will repeal some carbon dioxide emission rules for power plants, the latest step in the Trump administration’s broader effort to curb the agency’s role in regulating climate change.
RIYADH: Thirteen civilians were injured after attacks on several Saudi cities by Yemen’s Houthi militia, authorities said early on Tuesday.
The Iran-backed group targeted civilian areas in
Khamis Mushait, Abha and Taif with ballistic missiles and drones on Monday.
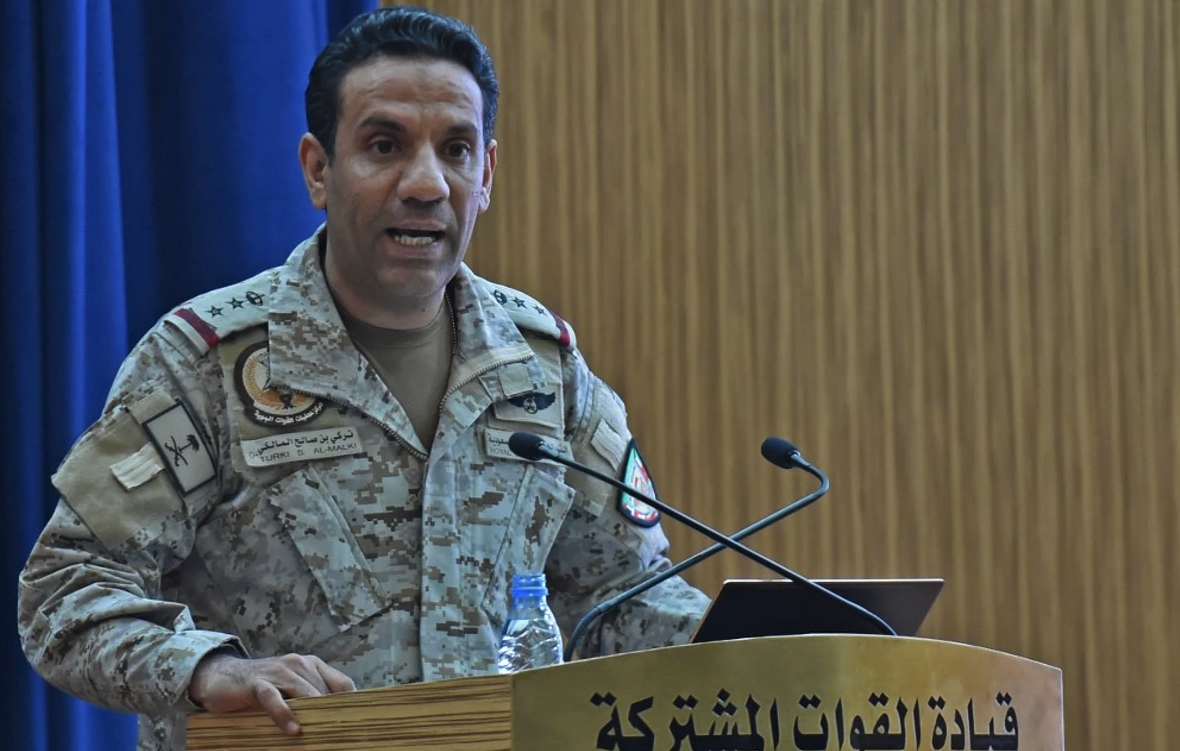
The strikes resulted in “minor to moderate injuries to 13 civilians and damage to 7 houses and two vehicles,” said Major General Turki Al-Malki, spokesperson for the Coalition to Restore Legitimacy in Yemen, in a statement issued on social media early on Tuesday.
“The Terrorist Houthi Militia continues its heinous and deliberate attacks on civilian objects and civilians in the Kingdom,” the statement read.
“The continuation of these deliberate and repeated attacks proves the Terrorist Houthi Militia’s approach and extremist ideology of escalation and targeting civilian objects and civilians.”
The Coalition said its joint forces will deal with the attacks
“responsibly and firmly to protect the sovereignty of the Kingdom, civilian objects, and civilians.”
Last week an attack by the militia left more than 70 people injured, including women and children, in various towns and cities across Saudi Arabia.
The Kingdom on Friday temporarily shut down its East-West Pipeline after it was targeted in several drone attacks in the Riyadh and Madinah regions.
Gulf and Muslim organizations condemned the attack on the pipeline, expressing solidarity with the Kingdom.
Folks confuse the medicine with the symptoms when they ask for dollarization or argue against it, as if the magic wand of switching to the dollar would cure the deep debt and the fiscal imbalances of the broken State-led model that crippled Venezuela.
Marcos Planchart wrote on this site last week that “it is certainly not the paper where the bolívar is printed the element that corrupts people or destroys the economy: it is the system behind it.” I agree with that sentence entirely. However, dollarization is not the first decision. There is a sequence that comes before it, and it is the sequence, not the currency, that determines whether any of this holds.
Antonio Ecarri and Steve Hanke want to change the unit of account. Planchart wants to keep it and repair the institutions standing behind it. Both are arguing about the currency. The currency is the second question, and it answers itself once you have answered how to fix the fiscal imbalance.
Those imbalances have four fixes: a legitimate and credible government, a closed deficit, restored conditions for private investment, and an open and transparent market for trading bolívares and dollars. Or you can dollarize. Notice that the first four require no change in the unit of account at all.
Here is the simplified mechanism: A government running a deficit it cannot finance has the Central Bank issue bolívares to cover it. The new money goes looking for dollars and for hard assets, and the rate moves. Running an official rate alongside the market one does not stop that. It only decides who captures the difference.
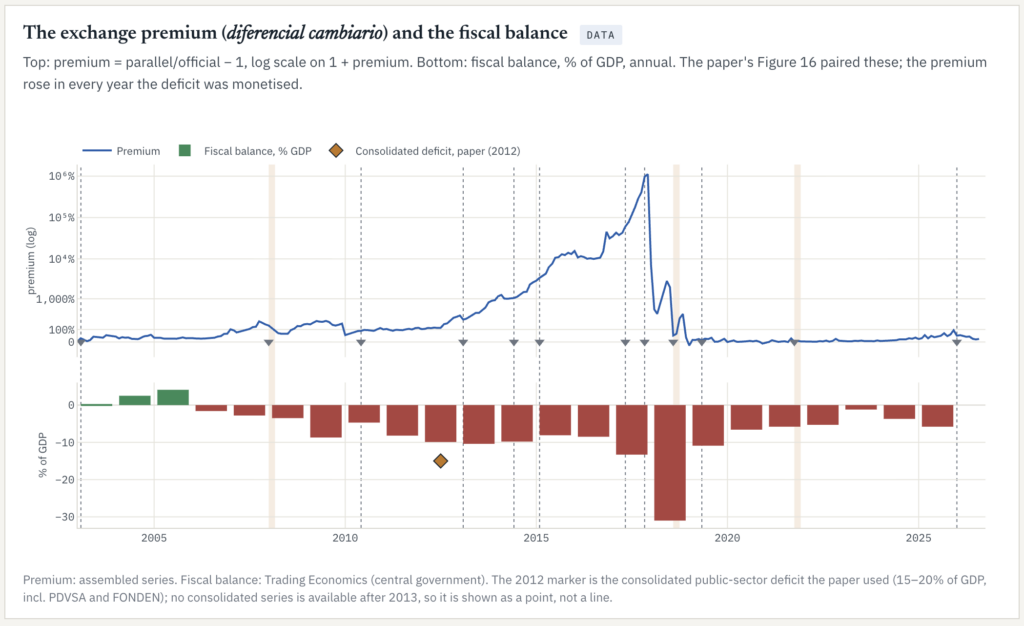
Top: Venezuela’s exchange premium, the parallel rate over the official rate, on a log scale, rising from near zero to over a million percent in 2017 and back down. Bottom: the fiscal balance as a share of GDP, in deficit every year from 2006. The exchange premium and the fiscal balance. The premium rose every year the deficit was monetized. Premium from the assembled official and parallel series. Fiscal balance from Trading Economics, central government. The 2012 diamond is the consolidated public sector deficit used in the 2013 paper, which included PDVSA and FONDEN; no consolidated series is published after 2013.
Dollarization is a reasonable destination after the fiscal work and a ruinous substitute for it. Do the work and you may not need it, because the inflation it was sold to cure will already be gone. Skip the work and it will cost you more than the bolívar does. Redundant or ruinous. There is no third case.
The three consequences, one at a time
Planchart lists what the case for dollarization claims: eliminating inflation, forcing fiscal discipline, eradicating corruption. Take them in that order.
First: it does eliminate inflation. This is Hanke’s most popular claim, and it is true. Ecuador dollarized in January 2000. Inflation averaged 39% a year through the 1990s and 2.9% from 2003 to 2024. The policy does achieve inflation reduction, and it does so quite fast.
Top: Venezuela’s exchange premium, the parallel rate over the official rate, on a log scale, rising from near zero to over a million percent in 2017 and back down. Bottom: the fiscal balance as a share of GDP, in deficit every year from 2006. The exchange premium and the fiscal balance. The premium rose every year the deficit was monetized. Premium from the assembled official and parallel series. Fiscal balance from Trading Economics, central government. The 2012 diamond is the consolidated public sector deficit used in the 2013 paper, which included PDVSA and FONDEN; no consolidated series is published after 2013.
Now notice what that concession costs the other side. Inflation is the entire platform. It is why the argument is popular in Caracas, and why anyone is listening to Ecarri in 2026. The harder thing to see is this: if we stabilize the fiscal accounts and jump-start private investment, inflation can be tamed and the case for dollarization goes with it. You cannot sell a cure for a disease the patient no longer has.
Second, it does not force fiscal discipline. Ecuador ran deficits in twelve of the thirteen years from 2013. The one exception was 2022, by four hundredths of a percentage point. Public debt went from 19% of GDP in 2011 to 64% in 2020, and Ecuador defaulted that year. It is 54% now. Growth averaged 6.4% a year from 2011 to 2014 and 1.4% from 2015 to 2019.
The mechanism is the one Planchart names himself. He warns that dollarization leaves a country “even more vulnerable to external shocks, such as a sudden plunge in oil prices.” That is precisely what happened to Ecuador after 2014. Oil fell, Ecuador could not devalue, and the shock had nowhere to go except the budget, and from the budget into debt and into lost growth. He states the fear and never uses the country it happened to. It is the best evidence in his own case and he leaves it on the table.
The deficit does not disappear when the currency changes. It simply has to be paid in a currency you cannot print.
Dollarization took away the printing machine, not the deficit, so the adjustment fell on debt instead of on prices. Ecuador does not show that dollarization is harmful. It shows that it is not enough. Of its two defaults, 2008 is the weaker example: it fell in a surplus year and was a choice rather than a financing crisis.
Third, regarding corruption, Planchart has already answered it, and I will not repeat a good argument badly. The exchange differential was never an oversight. It was an instrument. Change the currency and the people who built it still hold the pen.
What getting the sequence wrong costs
Planchart says a failed dollarization would force the government into more debt and severe cash shortages. He is right. Here is the size of it.
We ran the model with the same economy twice from the same starting position, $13.4 billion of reserves in 2026, changing one thing. Dollarize now on today’s deficit, alter nothing else, and the state’s dollar position will fall through zero in the third year and reach minus $24 billion by 2034. Dollarize after fiscal consolidation, with private investment recovering, and the same position accumulates to plus $127 billion. Same reserves, same model, one difference.
The deficit does not disappear when the currency changes. It simply has to be paid in a currency you cannot print.
Two lines from the same starting point of $13.4 billion in 2026. The green line, dollarization after the deficit is closed, rises steadily to about $80 billion by 2031. The red line, dollarization alone with the deficit unchanged, falls steadily and crosses zero in 2029, marked “dollars run out, 2029”. Dollarizing without fiscal reform is a recipe for disaster. Shown to 2031; the simulation runs to 2034, by which point the red path is minus $24 billion and the green one plus $127 billion. Every assumption behind it is a control the reader can move at https://www.bolivarjesus.com/KangarooPegRevisited2026/
Why 576% inflation sits on a deficit near 6%
Planchart gives the number: inflation reached 576% year on year in July. The mechanism above explains the direction. It does not explain the size, and the size is the interesting part.
The bolívar base has collapsed; measured at the parallel rate, it was around $15 billion in 2011 and 2012. In July 2026, it was $1.7 billion. The base that can be monetised is a ninth of what it was.
In 2013, Gino Bettocchi and I wrote about a State running a consolidated deficit of 15% to 20% of GDP, including PDVSA and FONDEN. On the narrower central government measure that is still published, the deficit has roughly halved since then, from 9.9% in 2012 to 5.8% last year. A far smaller deficit now carries the inflationary force that an enormous one carried then, because there is so little left to dilute. That cuts against both camps. It is not evidence that the bolívar is cursed, and it is not evidence that only the dollar can fix it. It is arithmetic about a very small base.
Where I actually disagree
Planchart wants to keep the bolívar permanently, in part to preserve room for industrial policy. The unit of account does not carry that weight, in either direction.
What breaks or holds a monetary regime is the deficit, private investment, and the institutions behind them. Those three decide the outcome, whether prices are quoted in bolívares or in dollars.
The argument about maintaining the unit of account in bolívares is about the State’s capacity to protect and nurture strategic industries. But industrial policy is paid for by a State with fiscal room, and Venezuela has neither. It becomes possible after stabilization, not instead of it.
Without credible rules, there is no private investment. Without investment, there is no oil and no tax base. Without revenue, there is a deficit. And a deficit breaks any exchange rate regime, whether it is denominated in bolívares or in dollars.
Planchart may well be right. His is a claim about what Venezuela becomes over the medium and long term; mine is about what stops the bleeding now. Our hope is that between the two visions, readers get the order of operations.
His best line is that starting dollarization under chavista rule is like handing the reconstruction of the oil sector to a man who helped destroy the electricity grid. I would make it structural rather than personal, because it is an argument about order.
Stage one is not monetary. It is a legal framework credible enough that private capital comes back. Without credible rules, there is no private investment. Without investment, there is no oil and no tax base. Without revenue, there is a deficit. And a deficit breaks any exchange rate regime, whether it is denominated in bolívares or in dollars. Once those policies are in place, they will open the market and the premium will close on its own. Then, the decision about Venezuela adopting the dollar formally can be taken calmly, from strength, rather than desperately as a rescue.
In 2013 we wrote that the choice was reform or hyperinflation. Maduro chose hyperinflation, and it ran from 2017 to 2021. The 2026 version of that choice is not dollar or bolívar. A currency is imported. A State is built.
“The Kangaroo Peg” was written by Gino Bettocchi and Jesús Bolívar, Second Year Policy Analysis, Harvard Kennedy School, 2013, advised by Ricardo Hausmann. The thirteenth year update, with both figures, the model and its sources, is available here.
BRUSSELS, Belgium: Belgium’s top universities condemned on Monday the government’s refusal to help 13 students from war-torn Gaza who received scholarships at Belgian universities reach the country.
Brussels set aside plans to evacuate the Palestinian students last week in a case that has split the coalition government.
The rectors of the European country’s top 10 universities expressed their “dismay” at the move in a letter, accusing the administration of using the students as “bargaining chips” in a “disgraceful political horse-trading.”
Centrist Foreign Minister Maxime Prevot has advocated in favor of evacuating the students but has faced opposition from the Flemish conservatives party of Prime Minister Bart De Wever, according to a government source.
Prevot said one member of the five-party coalition demanded concessions on migration, including the creation of deportation centers, in return for greenlighting the evacuations.
“They must not be treated as bargaining chips or as variables to be adjusted in political debates on migration,” the rectors wrote of the Gaza students.
“Their cases must be assessed for what they are: those of students and researchers who have been awarded scholarships on the basis of their academic merit and who have all expressed their intention to return to their home countries to contribute to their reconstruction.”
The students are among about 1,500 Palestinians in Gaza currently waiting to reach Belgium, having been granted the right to do so, mainly under family reunification rules, according to several NGOs.
Yet, evacuations from the Palestinian territory at war with Israel are proceeding at a trickle, with activists and now the universities accusing the government of deliberately slowing down the process.
“Discussions in recent weeks also show that the obstacles cited do not stem from insurmountable constraints but rather from a lack of political will,” the university chiefs wrote.
The case is not isolated, with Palestinian students hoping to study in Italy, Turkiye, the Netherlands, Germany also reporting delays in recent months.
Palestinian militant group Hamas launched an attack on Israel on October 7, 2023, which killed 1,221 people, according to official Israeli figures.
Israel’s offensive has since claimed at least 73,470 lives in Gaza, according to the Gaza health ministry, which operates under Hamas.
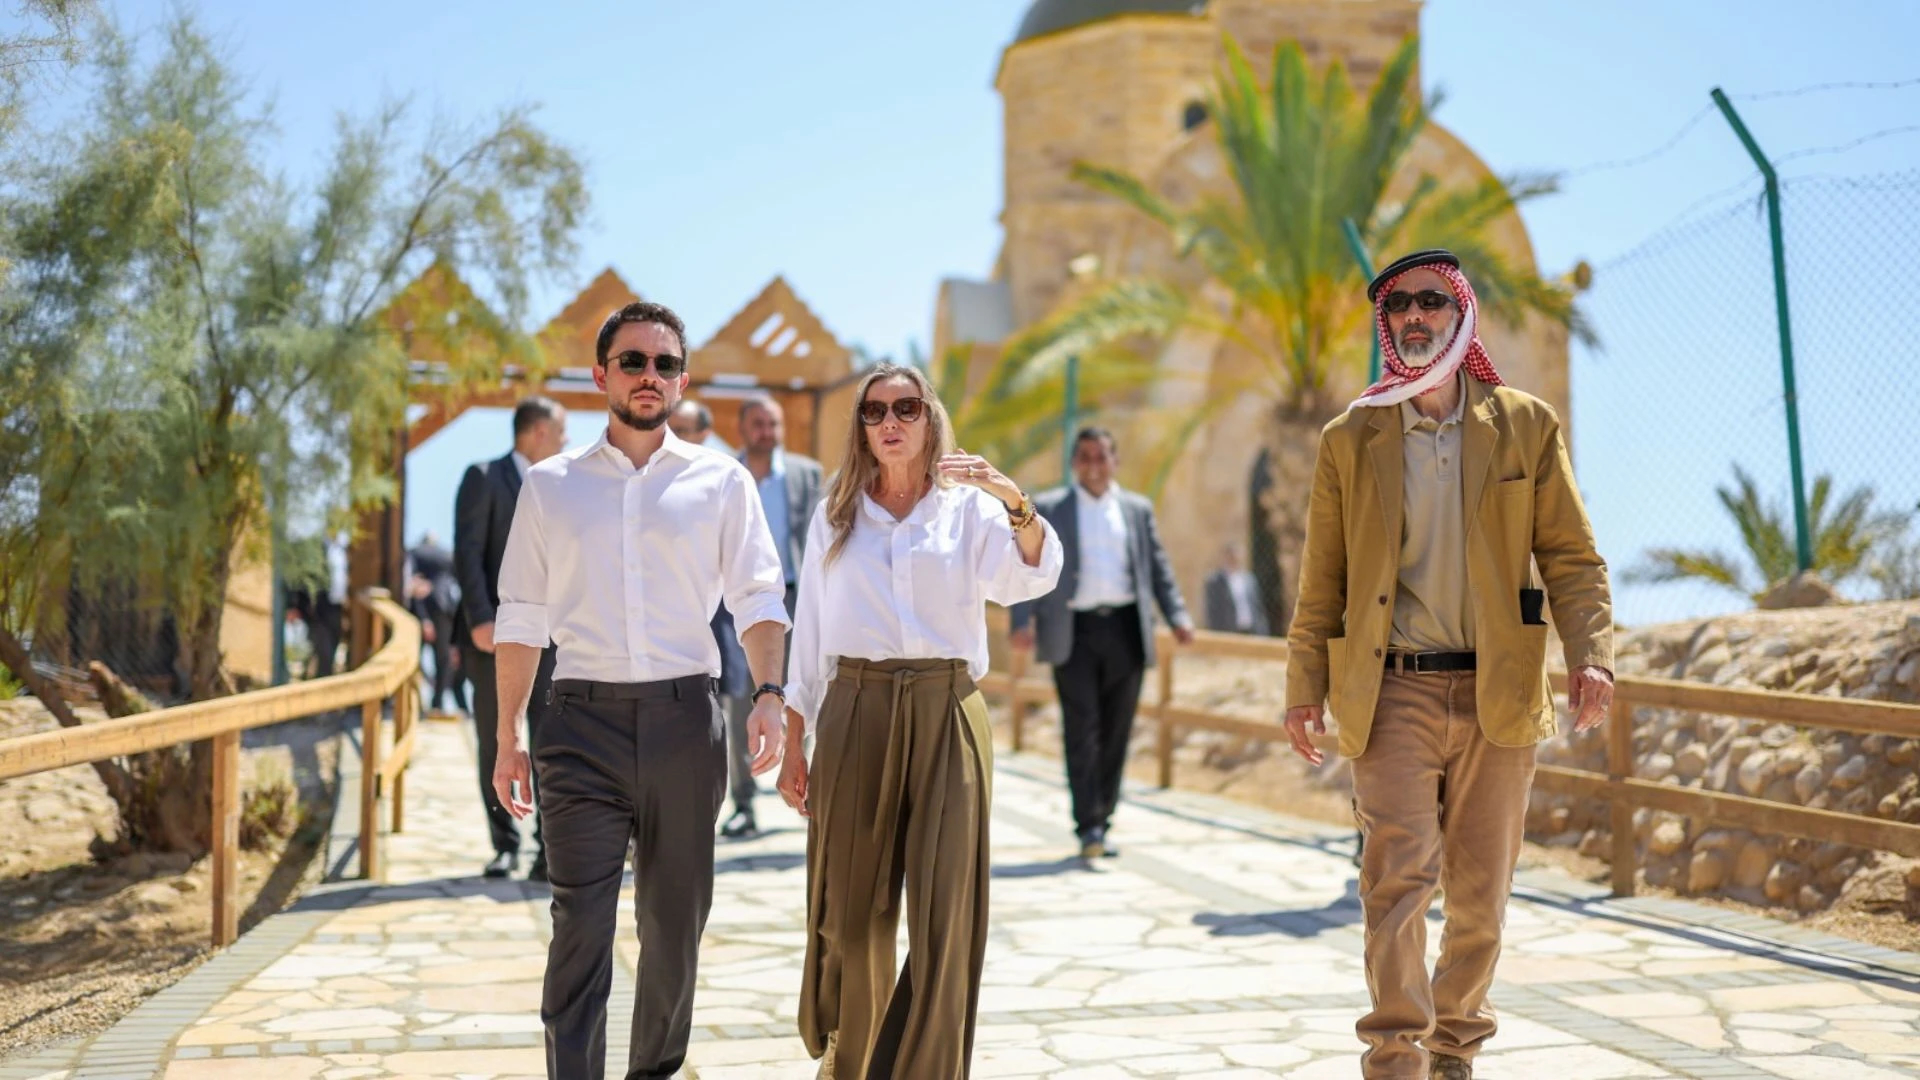
LONDON: Jordan’s Crown Prince Hussein bin Abdullah Al-Hashimi on Monday visited the baptismal site of Jesus, also known as Bethany Beyond the Jordan, to review preparations for the 2,000th anniversary of the historical event, which will take place in 2030.
He issued directives to enhance the site for the Christian pilgrims and other visitors who will visit the UNESCO World Heritage site to mark the bimillennial celebrations, the Jordan News Agency reported.
He said the upcoming occasion reaffirmed Jordan’s status as a premier destination for Christian pilgrimage. He emphasized the importance of efforts to promote the site of Jesus’ baptism, in coordination with the Ministry of Tourism and Antiquities and the Jordan Tourism Board.
During the visit, the crown prince met Prince Ghazi bin Mohammed, chairperson of the board of trustees for the Baptism Site Commission, and his wife, Princess Miriam.
Jordanian Ministry of Tourism officials recently met Palestinian counterparts to discuss collaboration in the field of religious tourism ahead of the 2030 bimillennial celebrations.
Both Jordan and Palestine are home to important Christian holy sites, including Mount Nebo in Jordan’s Madaba governorate, where the Bible says Moses saw the Promised Land before he died, and, in the West Bank, the Church of the Nativity in Bethlehem, and the Church of the Holy Sepulcher in East Jerusalem, which includes the traditional sites of Jesus’ crucifixion and resurrection tomb.
The crown prince was also joined on his tour of the baptismal site by the minister of tourism and antiquities, Imad Hijazin, the director of the Office of the Crown Prince, Zaid Baqain, and the director general of the Baptism Site Commission, Abdullah Bawareed.
CAIRO/NEW YORK: The UN secretary-general’s personal envoy for Sudan, Pekka Haavisto, held talks in Cairo on Sunday and Monday with the Arab League’s secretary-general, Nabil Fahmy, and the Egyptian foreign minister, Badr Abdelatty, as preparations continued for UN meetings in New York this month.
The diplomatic efforts came as drone strikes and other hostilities continued to endanger civilians and drive displacement across Sudan’s Darfur and Kordofan regions, and Blue Nile State.
During his meeting with Haavisto on Sunday, Fahmy stressed the importance of launching a comprehensive, Sudanese-led political process that involves all sections of Sudanese society.
He also reaffirmed the Arab League’s support for Sudan’s sovereignty and territorial integrity, and called for the prevention of external interference in the country’s affairs.
In a separate meeting on Monday, Abdelatty stressed the need to support stability, end the conflict and reach a comprehensive political settlement that preserves Sudan’s sovereignty and meets the aspirations of its people. His talks with Haavisto encompassed the latest developments in the conflict, as well as regional and international efforts to halt the escalation and advance de-escalation measures.
Abdelatty reiterated Egypt’s support for Sudan’s unity, sovereignty, territorial integrity and national institutions. He also emphasized the need to respect Sudanese ownership of any political solution.
Both sides stressed, in an official statement, the important need to respect Sudan’s sovereignty, support de-escalation efforts, facilitate the delivery of humanitarian aid and alleviate the suffering of the Sudanese people.
Meanwhile, UN spokesperson Farhan Haq said drone strikes and other hostilities in Sudan continued to threaten civilians and force people from their homes.
In Blue Nile State, several drone strikes hit fuel stations and other critical infrastructure in the state capital on Sunday, with civilian casualties reported. The UN estimates that nearly 100,000 people were displaced by insecurity across the state between January and August, about 66 percent more than the figure since the start of the year that was reported in late May.
In North Darfur, drone strikes hit several locations in Tina, near the border with Chad.
The UN said nearly 1,200 people were displaced from two villages in El-Fasher between Sept. 10 and 13. More than 1,200 others fled villages in Um Baru over the past week, with most of them crossing into Chad.
Drone attacks were also reported at several locations in West Darfur on Saturday, including a fuel market west of the state capital. Casualties were reported.
Insecurity in Kordofan continues to drive displacement and disrupt humanitarian operations. More than 7,000 people have reportedly arrived in Abassiya, South Kordofan, in recent weeks. In North Kordofan, Al-Mina Al-Bari camp in the state capital, El-Obeid, is hosting about 9,000 families, placing further strain on overcrowded sites and basic services.
Haq reiterated the UN’s call for all parties involved in the conflict to protect civilians and civilian infrastructure, and ensure rapid, safe, unhindered and sustained humanitarian access to those in need.
Sudan descended into civil war in April 2023 after tensions between the Sudanese Armed Forces and the rival paramilitary Rapid Support Forces erupted into fighting. The conflict has killed tens of thousands of people and driven a severe hunger crisis.
A report published in May said nearly 19.5 million people, about 41 percent of Sudan’s population, faced high levels of acute food insecurity.
The UN Food and Agriculture Organization, the World Food Programme and UNICEF called for an immediate cessation of hostilities. They also urged the international community to increase funding for food assistance, emergency food production, efforts to rebuild livelihoods, and nutrition, health, water and sanitation services.
Amani El-Taweel, a researcher at Al-Ahram Center, told Arab News that the meetings in Cairo reflected continuing diplomatic efforts to find a solution to the Sudanese crisis.
She said the situation remained extremely complex, particularly amid the wider escalation in the Middle East, and that the emergence of new fronts had further complicated conditions in eastern Sudan.
Ezzat Saad, director of the Egyptian Council for Foreign Affairs, told Arab News the only path out of the crisis was to unify Sudanese institutions and secure a ceasefire.
He said any solution must come from within Sudan, without interference from external parties. Haavisto’s meetings in Cairo were part of the preparations for upcoming UN General Assembly sessions in New York at which heads of state would have an opportunity to discuss regional crises, Saad added. Sudanese institutions themselves must also demonstrate a commitment to preserving the country’s unity, he said.
On Saturday, the Egyptian president, Abdel Fattah El-Sisi, met the UN secretary-general, Antonio Guterres, on the sidelines of the BRICS summit in India. El-Sisi said any threat to Sudan’s security, unity or sovereignty constituted a “red line,” according to a statement from the Egyptian presidency.
In January, Egypt hosted the fifth meeting of the Consultative Mechanism to Enhance Coordination of Peace Efforts in Sudan, which was chaired by Abdelatty.
The foreign minister said Egypt remained committed to achieving peace and stability in Sudan. He highlighted the launch of the Sudan Neighboring Countries Initiative in July 2023, which emphasized the need for a ceasefire, inclusive political consultations and the guaranteed delivery of humanitarian aid.
AutoZone (AZO) will report its fiscal fourth quarter results before the market opens next Tuesday, and all eyes will be on the do-it-yourself (DIY) segment which has been undermined by cash-strapped consumers.
EU Trade Commissioner Maroš Šefčovič will visit Manila next week to finalise a trade agreement with the Philippines, the European Commission confirmed to Euronews on Monday.
ADVERTISEMENT
ADVERTISEMENT
The agreement is nearing conclusion as Brussels has increasingly looked to the Asia-Pacific over the past year to diversify its trade ties.
Since the return to power of US President Donald Trump, the global trade order has been shifting, with the EU seeking new markets for its exports.
The latest round of EU-Philippines trade talks took place in May, with access to public procurement emerging as the final sticking point. An agreement would mark a shift for the Philippines, which has so far kept public contracts closed to foreign bidders.
The Commission told MEPs earlier this month that the rest of the agreement was ready. The aim is to lift trade barriers between both partners in most sectors.
An official from the EU executive also told MEPs that sanitary and phytosanitary rules for food products were “ambitious”, alongside automotive standards that would improve EU manufacturers’ access to the Philippine market. The official added that the EU and the Philippines were “complementary” in both industrial goods and agriculture.
The deal is an important one for Manila, which has been hit by US tariffs in 2025 and by the war in Iran, which heavily impacted energy prices in the country.
However, the Philippines also reached “upper-middle-income country” status in August, granted by the World Bank, which makes it a promising market — “One of the most dynamic economies in the East Asia Pacific region since 2010,” the World Bank said.
Bilateral trade in goods between the EU and the Philippines amounted to €16.8 billion in 2024. That same year, the EU was the Philippines’ fourth-largest trading partner, accounting for 7% of the country’s total trade in goods, while the Philippines was the EU’s 39th-largest trading partner, accounting for 0.3% of the EU’s total trade in goods.
After the Philippines, the Commission aims to conclude talks with Thailand, making 2026 a strong year for EU trade deals across Asia and the Pacific, with agreements already reached with Australia and India.
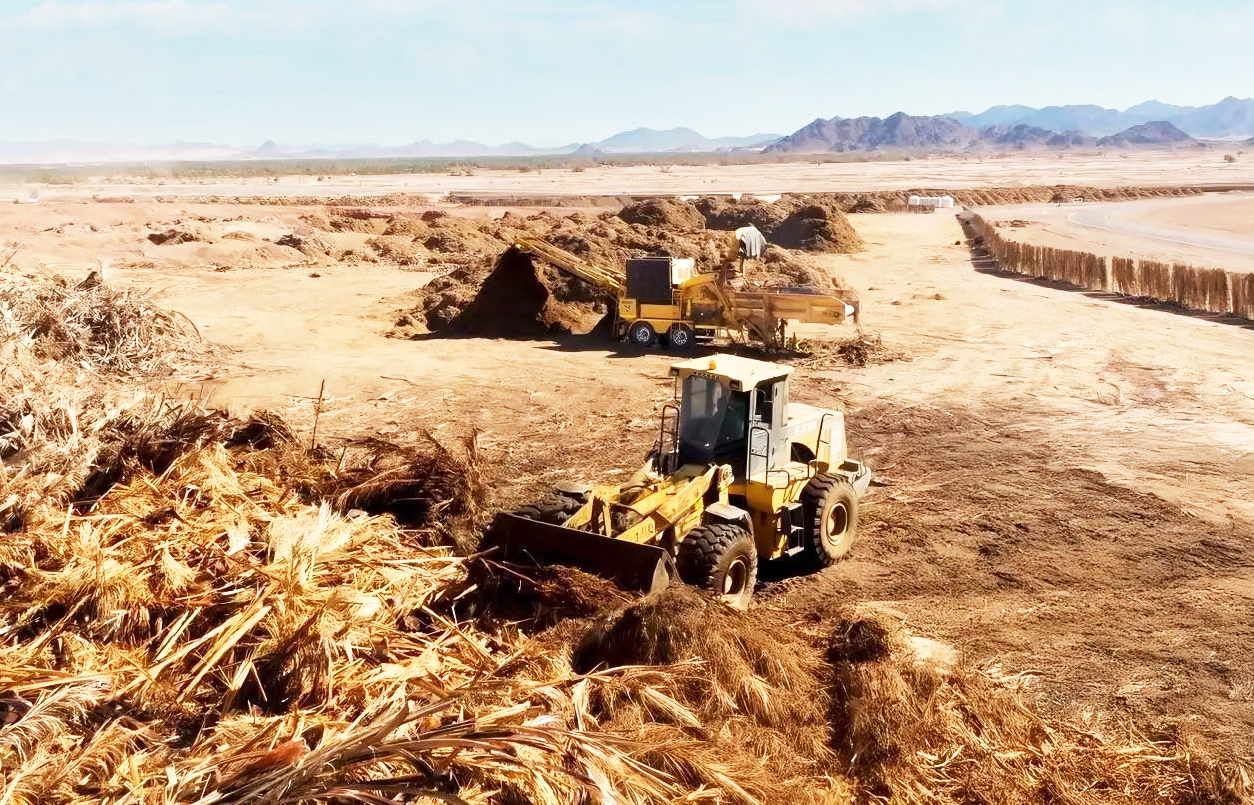
RIYADH: Madinah region has strong potential to turn date palm waste into value-added products, leveraging its competitive advantage in the palm and date sector to create investment opportunities in the circular economy.
According to Al-Madinah Al-Munawarah Chamber’s economic bulletin, the region has about 26,000 farms and approximately 8.1 million date palms, representing nearly 21 percent of Saudi Arabia’s total.
Each palm generates between 20 and 23 kg of waste annually, bringing the region’s estimated annual total to between 162,000 and 186,000 tonnes, the Saudi Press Agency reported.
Products made from date palm waste include wood and composite boards, organic fertilizer, biochar, charcoal briquettes, biofuel pellets, natural fibers, insulation materials, date seed oil, wooden products and handicrafts.
These industries could create new production chains, from waste collection, sorting and processing to manufacturing and marketing. This would open investment opportunities, diversify the palm sector’s products and improve resource-use efficiency.
The world is creating more wealth than ever before but protecting and growing it has become increasingly challenging.
To put this into perspective, BCG’s Global Wealth Report 20261 found that global financial wealth increased by 10.7% in 2025 to US$333 trillion, its highest rate of growth since 2021. The Gulf Cooperation Council (GCC) is also becoming more prominent within this evolving landscape. The region’s total wealth reached an estimated US$8.6 trillion in 2024, while EY’s GCC Wealth Management Industry Report 20252 estimated that more than 200,000 individuals across the region qualify as ‘high net worth’ (HNW).
Amid this trend, around half of the private wealth in the GCC remains tied to real estate, highlighting an opportunity for greater diversification across assets and markets.
We see this among QNB’s private banking and wealth management clients, with a move beyond traditional equity and fixed income allocations towards broader diversification strategies. For example, interest is growing in alternative investments, international opportunities and actively managed solutions that can respond to changing market conditions.
The GCC’s Growing Role in Global Wealth
The GCC’s emergence as an international wealth hub reflects the broader transformation taking place across its economies. Investment in technology, infrastructure, financial services, tourism and advanced industries is widening the range of opportunities available to investors and strengthening the region’s connections with markets across Asia, Africa and Europe.
The development of financial centres, deeper capital markets and national economic transformation programmes is also creating a more sophisticated regional investment ecosystem. These initiatives are strengthening the region’s position not only as a source of capital, but also as a destination for private wealth and a platform through which investors can access international markets.
From Portfolio Allocation to Active Stewardship
As the investment universe expands, diversification is no longer limited to simply holding a mixture of listed equities and fixed income instruments. Investors increasingly require portfolios diversified across geographies, currencies, sectors, asset classes and investment horizons.
This is driving demand for alternative investments as investors look for new sources of return and greater portfolio resilience.
According to EY’s GCC Wealth Management Industry Report 20253, 69% of wealthy clients in the Middle East hold alternative investments. This supports what we are seeing among QNB’s clients, with growing interest in private markets, structured solutions and thematic opportunities that can enhance diversification and provide attractive risk-adjusted returns.
These investments can provide access to opportunities that are not always available through public markets. However, they can also introduce liquidity constraints, longer investment horizons, valuation complexity and varying levels of transparency. Access alone is therefore not enough.
Each allocation also requires rigorous due diligence and a clear understanding of how it contributes to the objectives, liquidity requirements and risk profile of the overall portfolio.
For HNW individuals and family offices, their objectives often extend beyond investment performance. These may include capital preservation, liquidity planning, succession, or the responsible stewardship of family assets.
Such priorities are becoming more pronounced. EY estimates that approximately 500,000 older individuals across the GCC could transfer around US$438 billion to their heirs by 2030, increasing the importance of multigenerational wealth planning.
Combining Global Access with Regional Expertise
To meet the evolving needs of HNW individuals, global reach provides access to a wider universe of investments, specialist expertise and institutional relationships. At the same time, regional knowledge allows advisers to understand local market structures, emerging opportunities and individual client priorities.
Together, these capabilities support portfolio strategies that are globally diversified while remaining relevant to each client’s circumstances.
QNB Group is well positioned at the intersection of these dynamics. As a leading financial institution in the Middle East and Africa, with a presence in over 28 countries across Asia, Europe and Africa, the Group combines international market access with deep regional knowledge. This enables QNB to provide tailored wealth-management solutions informed by a strong understanding of market opportunities and client needs.
However, scale and access are only part of effective wealth management. Clients increasingly expect advice that reflects their individual circumstances, risk appetite and ambitions. This requires bespoke portfolio strategies, data-driven market insights and robust governance, supported by relationships built on trust and discretion.
A More Active Approach to Long-term Wealth
The next phase of wealth management will be more globally diversified, actively managed and advisory-led.
This degree of monitoring is essential; while investors will continue to seek wider access to international and alternative opportunities, they will also require greater discipline in how those opportunities are evaluated and integrated into their portfolios.
The GCC is well placed to play a growing role in this evolution. Its expanding wealth base, economic transformation, financial capacity and international connectivity are strengthening its position as both a destination for capital and a centre for long-term wealth creation.
Ultimately, successful wealth management depends on the ability to combine global access with regional understanding and investment opportunity with disciplined stewardship. Institutions that combine these capabilities will play an increasingly important role in helping clients preserve their wealth, navigate complexity and create enduring value across generations.
Read more about QNB Group’s wealth management capabilities and solutionshere.