LongTerm

Arab News | Citigroup tells Asharq Bloomberg: Investors are confident in Saudi Arabia’s ‘long-term’ economic story

RIYADH: David Livingstone, chief client officer at Citigroup, believes investor appetite for Saudi debt issuances reflects confidence in the Kingdom’s long-term story, while Gulf countries remain capable of maintaining their positive performance in debt markets despite higher yields and increased global supply.

Livingstone said in an interview with Nour Amache on the “East-West” program on Asharq Business with Bloomberg that the performance of Saudi sovereign issuances, as well as those of the Public Investment Fund, demonstrated the resilience of Saudi Arabia’s market and continued demand from international investors, despite the obstacles created by the Iran war this year.

Livingstone’s comments came after the Kingdom raised $3.25 billion through international sukuk in early September, attracting orders of around $16.5 billion, or more than five times the issuance size. Saudi Arabia tightened the pricing spread by about 30 basis points from the initial guidance.

The Citigroup head added that the pricing adjustment “demonstrates confidence in this long-term story,” placing it within the context of the transformations underway in the Kingdom under Vision 2030.

The comments came after Citigroup helped its clients in Saudi Arabia raise more than $40 billion since the beginning of the year. The bank also decided to increase its direct exposure limits to the Kingdom after it demonstrated “strong economic and financial resilience,” according to CEO Fahad Al-Deweesh.

Debt-market pressures

Higher global yields and increased government borrowing will give investors a wider range of choices in the bond market, Livingstone said, noting upward pressure on yields amid abundant debt supply in emerging markets, Europe, the UK and the US.

Despite this, he said that “Saudi Arabia, and Gulf countries as a whole, can continue this positive performance compared with the recent past.”

Yasir Al-Salman, chief financial officer at the Public Investment Fund, told Asharq Business with Bloomberg that international debt markets would remain the fund’s largest source of financing. The fund had around SR3.4 trillion ($906.1 billion) in assets under management after injecting about SR750 billion into the Saudi economy over five years.

Debt instrument pricing in the Kingdom is linked to US bond yields, which have recently been elevated. The yield on the 10-year US Treasury continued to rise for a fifth consecutive session on Sept. 14, exceeding 5 percent, its highest level since 2023.

Are investors affected by project reviews?

Asked about the effect of media reports concerning the postponement or reassessment of some projects in Saudi Arabia on foreign investor appetite, Livingstone said this did not change the fundamental basis of investor interest in the Kingdom. He said economic diversification remained “the attractive factor for investors,” as infrastructure development and projects connected to the economic transformation continued.

He added that the review was “justified” in light of the economic circumstances surrounding the projects being financed, with attention focused on their feasibility and sustainability.


Source link

Dutch Pension Shift Hits Long-Term Debt Market

European CFOs must adjust as the region’s biggest pension buyer of long-dated debt cuts back.

This article appears in the September 2026 issue of Global Finance Magazine.

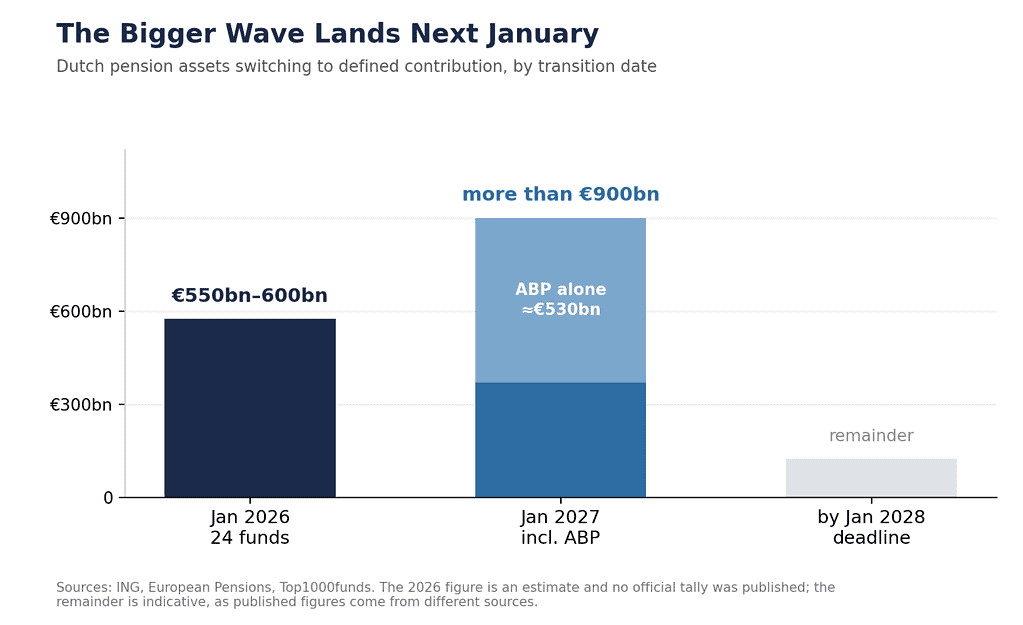
The Netherlands pension system is beginning to reduce one of Europe’s most reliable sources of demand for long-dated debt as a broad regulatory shift changes how Dutch pension funds manage their assets and liabilities. ING Groep NV estimates that nearly €600 billion ($699 billion) of assets have already been affected by the change, with more than €900 billion expected to follow early next year.

Under the old defined-benefit pension system, Dutch funds were required to hedge the interest-rate sensitivity of long-term pension liabilities by using long-dated bonds and swaps to match assets with payments extending decades into the future. Under the new defined-contribution model, which became law in 2023, that liability matching requirement has been significantly reduced, allowing funds to carry less duration and scale back their long-term hedges, resulting in less structural demand for the longest-dated debt and swaps.

For European CFOs, this could mean a higher premium for 20-, 30- and 50-year borrowing as companies and governments compete for a smaller pool of long-duration investors.

The change “should reduce structural demand for long-end duration assets and support curve steepeners over the long-term horizon,” wrote Sara Adjir, senior vice president and portfolio manager, and Jeroen van Bezooijen, account manager, at Pacific Investment Management Co., in a research note. They expect the impact will be mostly concentrated in 50-year swaps, but will also be felt in the demand for 20- and 30-year euro swaps and government bonds, including German and Dutch debt.

Deadlines

The Netherlands runs Europe’s largest pension system, with roughly €1.6 trillion in assets, and every fund must complete the switch by January 2028. Dutch pensions have long dominated the market for European long-dated debt, holding around €88 billion of interest-rate swaps maturing beyond 25 years at the end of last year, roughly a quarter of the total.

The first major wave of the transition came on Jan. 1, when 24 funds converted, among them the healthcare scheme PFZW and the metals scheme PMT, with an estimated €550 billion to €600 billion of pension assets between them. Analysis by the Netherlands central bank shows that Dutch pensions bought almost €34 billion net of swaps maturing inside 25 years while selling more than €12 billion of longer-dated ones. 

The bigger test, however, comes when more than €900 billion of pension assets is scheduled to convert on Jan. 1, with the Dutch civil service scheme ABP accounting for about €530 billion of that. 

The shift does not mean long-dated Dutch debt is suddenly becoming illiquid or even hard to sell: “Overall, we still see strong demand for our 30-year bond. Remember, we are AAA,” said Saskia van Dun, director of the Dutch State Treasury Agency.

Sovereign Issuers Adjust

Data indicates that sovereign borrowers are already adjusting to the change.

The share of Netherlands government bonds sold at maturities beyond 10 years fell from 42% at the start of 2025 to 31% by the third quarter, according to the Organization for Economic Co-operation and Development (OECD), which calls the constraint on long tenors structural. The OECD expects eurozone debt agencies to sell a record €1.35 trillion of medium- and long-term bonds this year into that thinner pool of demand.

For European finance chiefs, however, times are changing. For two decades, long-dated bond demand was unusually deep and predictable. As it recedes, the shifting cost of locking in 20 or 30 years of funding could become a live question.

Thomas Monteiro is a contributing writer based in Spain.

Source link