Crypto

ECB calls for tougher EU crypto rules and wider ban on stablecoin interest

A day after unveiling Pontes, its system for settling tokenised assets in central bank money, the ECB has set out how it wants Europe’s crypto rulebook rewritten.


ADVERTISEMENT


ADVERTISEMENT

The response, published on Tuesday by the European System of Central Banks, which groups the ECB with the EU’s national central banks, argues for tougher rules on stablecoins, staking and crypto firms.

It feeds into the European Commission’s review of the Markets in Crypto-Assets Regulation, known as MiCA, the EU’s rulebook for cryptocurrencies and the firms that trade them.

MiCA has applied since December 2024, and the last transitional deadline for existing operators expired on 1 July, including Binance, the world’s largest exchange, to stop serving European customers.

The Commission’s consultation will close on 30 September, a month later than planned.

The central banks’ recommendations are not binding, and the Commission will weigh them alongside other responses before deciding whether to reopen the law.

EU diplomats have told Euronews they expect a revision in 2027, which would need the approval of the European Parliament and member states.

No interest and no loopholes

Stablecoins are cryptocurrencies designed to hold a steady value, usually by tracking the US dollar.

MiCA already bars both issuers and crypto exchanges from paying interest on them, and the central banks want it kept that way.

“The payment of stablecoin remuneration should continue to be prohibited,” the ECB response says.

Their targets are the workarounds. Some exchanges, the response notes, offer crypto lending, borrowing and staking, “thereby replicating the economic effect of interest payments through ancillary or unregulated services.”

The central banks want the ban extended to those activities and to indirect rewards, such as certain loyalty-programme benefits, calling it “a clear legislative priority”.

Washington has gone the other way.

The 2025 GENIUS Act banned US stablecoin issuers from paying interest but left exchanges free to offer rewards, and whether to close that gap became one of the most contested fights over the CLARITY Act, the landmark crypto bill that fell ten votes short in the US Senate on 15 September.

A brake on US dollar stablecoins

The central banks want stronger tools against tokens pegged to foreign currencies.

It would be useful, they say, if authorities could impose “a prohibition to issue new tokens, as well as an obligation to redeem existing tokens” on issuers where central banks judge that the tokens pose a threat, including to financial stability.

More broadly, they see limited benefit in stablecoins for everyday payments at home, given instant bank transfers and the planned digital euro. They warn that MiCA provides no legal basis for issuing the same stablecoin both inside and outside the EU.

In a bank run, European reserves could end up paying holders elsewhere, while “EU authorities cannot determine with certainty how many tokens are held within the Union.”

Eurozone central banks also do not currently let stablecoin issuers hold customer funds with them.

A token fully backed by central bank money, the response warns, “would effectively result in a ‘synthetic’ central bank digital currency” that is essentially a private imitation of the digital euro and could, in theory, drain deposits from commercial banks, especially under stress.

Staking and decentralised finance

On staking, where users lock up crypto in exchange for rewards, the response is blunt: “Staking, lending and borrowing of crypto-assets should be regulated at Union level.”

Where a firm takes customers’ crypto and promises to return it, potentially with a premium, the central banks argue that the arrangement can be “comparable to the taking of repayable funds”, in the language of banking.

The same applies to decentralised finance, or DeFi, where lending and trading run on automated software rather than through a company.

MiCA exempts fully decentralised services but never defines the term, and the central banks cite studies showing that full decentralisation is rarely, if ever, achieved, leaving it unclear who is in control.

Who licenses crypto exchanges?

The central banks also back a Commission proposal to move licensing and supervision of crypto firms from national regulators to ESMA, the EU’s markets watchdog.

Currently, one national licence covers the whole bloc, which was the route Binance originally pursued in Greece.

The Wall Street Journal reported last week, citing people familiar with the discussions, that ECB President Christine Lagarde urged Greek Prime Minister Kyriakos Mitsotakis not to approve Binance’s application because of the exchange’s past compliance problems and fears that its scale could deepen the use of US dollar stablecoins in Europe.

A senior Greek regulator, according to the newspaper, told the exchange that Lagarde wanted the decision delayed until ESMA took over, the same shift the central banks endorse in Tuesday’s response. Binance withdrew the application on 24 June.

Neither the ECB nor the Greek regulator has confirmed the account. The ECB, which has no formal role in licensing crypto firms, declined to comment, while Binance said it would “not comment on speculation”.
Source link

Strategy soars 16% as crypto stocks advance (MSTR:NASDAQ)

Digitized Bitcoin Symbol

peterschreiber.media/iStock via Getty Images

Strategy Inc. (MSTR) advanced just over 16% on Friday, as crypto-related stocks broadly advanced after the SEC approved a temporary “Innovation Exemption” allowing certain venues and liquidity providers to facilitate trading in tokenized U.S.-listed stocks.

Shares rose $21.67 on the session

Seeking Alpha’s Disclaimer: This article was automatically generated by an AI tool based on content available on the Seeking Alpha website, and has not been curated or reviewed by humans. Due to inherent limitations in using AI-based tools, the accuracy, completeness, or timeliness of such articles cannot be guaranteed. This article is intended for informational purposes only. Seeking Alpha does not take account of your objectives or your financial situation and does not offer any personalized investment advice. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank.

Source link

Bitcoin drops after US Senate blocks landmark crypto bill

Crypto markets dropped late on Tuesday and early Wednesday, as investors digested a defeat that few in the industry had expected.


ADVERTISEMENT


ADVERTISEMENT

The procedural motion on the CLARITY Act drew 49 votes in favour and 50 against, 11 short of the 60 required to advance, dealing a major setback to efforts to pass market structure legislation this year.

The CLARITY Act, formally the Digital Asset Market Clarity Act, was meant to divide supervision of digital assets between the US Commodity Futures Trading Commission and the Securities and Exchange Commission, replacing a fragmented system in which classification has largely been settled through enforcement actions and litigation.

Bitcoin fell almost 34 over the past 24 hours to below $76,000, while HYPE, the token behind the decentralised exchange Hyperliquid, which stood to benefit from the legislation, also dropped about 4% to below $78.

Most major tokens fell alongside them.

A deal that still was not enough

The bill’s defeat is striking because so much had been conceded.

US President Donald Trump agreed over the weekend to ethics restrictions he had long resisted, including a requirement that federal officials and their spouses divest significant financial interests in crypto issuers or place them in a blind trust, and a role for state attorneys general in enforcing those rules.

Republican negotiators said that over 120 Democratic requests were written into the final text of the more than 600-page bill, representing a major bipartisan effort.

Still, it was not enough.

Four Republicans, Jerry Moran, Susan Collins, Josh Hawley and Thom Tillis, joined the 45 Democrats who voted against it. The Democratic Senator Chris Coons did not vote.

Democratic Senator Elizabeth Warren, the bill’s most prominent opponent, said it “fails to adequately protect investors, our financial system and our national security,” and attacked Trump’s crypto ventures on the US Senate floor hours before the vote.

Republican Senator Thom Tillis’s vote was a procedural exception. After having publicly backing the ethics package that morning, Tillis voted no to preserve a motion to reconsider, leaving open the possibility of another cloture vote.

Senator Cynthia Lummis, the Wyoming Republican who has led crypto legislation in the US Senate since co-authoring the Responsible Financial Innovation Act in 2022, was blunt afterwards.

“I think we’re done. It’s over,” she told reporters before going considerably further online.

“The once-proud Democratic Party is anti-consumer and pro-illicit finance, anti-ethics, anti-free enterprise, anti-worker, anti-livable wage jobs and pro-socialism,” she wrote in a social media post.

The failed vote likely means the crypto industry will have to wait until next year for clearer rules to be discussed.

The US midterm elections are in just seven weeks which complicates bringing the bill back up for consideration in the short term.

Senators are scheduled to leave Washington in early October and not return until after the election and the House recesses even earlier, heading out of town already at the end of this week.

Members, especially those in tight races, are eager to return to their home states and hit the campaign trail.

Regulators inherit the problem

The legislation’s failure does not mean nothing happens. It means the rules are more likely to be written by agencies instead.

The US Securities and Exchange Commission under Paul Atkins and the US Commodity Futures Trading Commission under Michael Selig have already been building a framework without Congress.

The two signed a cooperation agreement in March and issued a joint interpretation sorting tokens into five categories, with Atkins stating that most crypto assets are not, in themselves, securities.

The SEC’s own agenda includes registration exemptions for token launches, a safe harbour for projects decentralising away from central control, and rules on custody and trading venues.

Analysts expect that work to accelerate now.

However, the catch is durability, because agency rules can be rewritten by a future US administration, which is precisely the instability the CLARITY Act was meant to end.

Source link

Reform receives second £36m donation in two days as crypto investor matches record

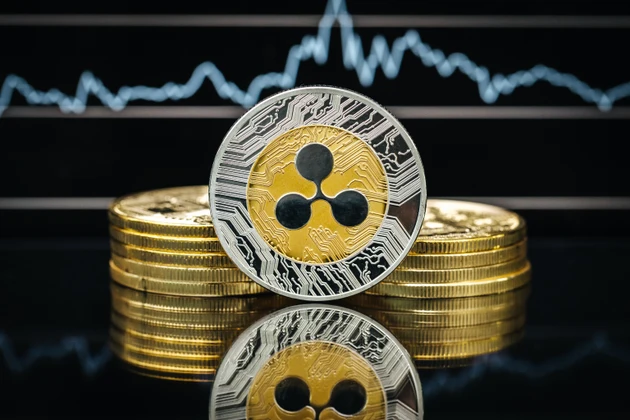
Harborne has already donated millions to Reform and Farage, who is currently under investigation by the parliamentary standards commissioner over whether he should have declared a £5m cash gift from Harborne ahead of the 2024 election.

Farage has argued that he was under no obligation to register the “purely private” gift, as it was unrelated to his parliamentary or political activities.

The party is also facing scrutiny over its finances after a broadcast by Channel 4 News last week showed two senior Reform aides apparently suggesting a way around electoral law to secure foreign party donations.

The Metropolitan Police has said it is investigating, while the party denies any wrongdoing.

The force is also looking into donations given to the party by Fiona Cottrell, mother of longstanding Farage ally George Cottrell, as well as a company controlled by its deputy leader Richard Tice.

Harborne wrote on Saturday that he had “already accumulated enough wealth for the rest of my life”, while Reform was a “start-up party” that lacked “the benefit of hundreds of years of patronage”.

“A start-up party needs more money than can be provided by membership fees alone, to build and sustain itself and be ready for government,” he said.

Harborne and Delo’s donations mark the largest sums received by a UK political party since they had to begin declaring them in 2001.

Delo, who also announced his donation in a Telegraph op-ed, said he was giving the money away because he wanted a “fair fight and a level playing field”. He said in April he was moving back to Britain from Hong Kong.

Addressing the recent scrutiny of Reform’s finances, he said: “My conclusion from Reform’s recent troubles is that they should spend less time trying to raise funds to compete on equal terms and more time preparing for government.”

Last year, he was given an unconditional pardon by US President Donald Trump over a breach of anti-money laundering laws at his crypto trading platform, BitMEX, to which he had pleaded guilty in 2022.

There are currently no restrictions on the amount of money UK-based donors can give to political parties.

However, the Labour government has introduced a £100,000 cap on donations from British citizens living overseas, and plans to introduce a similar one for those who have recently returned to the UK.

There were nine donations of £1m or more to political parties in 2025. The largest was £9m given to Reform UK by Harborne.

Labour had five donations of £1m or more – totalling nearly £10m – and the Conservatives had three of £1m each.

Labour said Reform and Farage still had “serious questions” to answer about their finances.

Party chairwoman Bridget Phillipson said Reform were “drowning” in “sleaze and scandal”,.

She added: “It’s time Farage and Reform came clean with the public, fully co-operated with the ongoing police investigations and prove they’re not just in it for themselves.”

Rachel Millward, deputy leader of the Green Party, told BBC News it wanted a cap on donations from individuals of £500,000.

She said the donations to Reform were “absolutely staggering amounts”, adding: “What I am very frustrated about is the influence of extreme wealth and the super rich. What I want to see is people in politics representing the needs of their communities and ordinary people.”

Liberal Democrat Cabinet Office spokeswoman Lisa Smart called for the government to introduce emergency legislation to cap donations.

She said: “These are eye-watering amounts of money. This is real emergency for our democracy. It presents a very clear and present threat.”

Duncan Hames, Director of Policy and Programmes at campaigning charity Transparency International UK, said: “This is a watershed moment, with two billionaires pledging £72m to one political party in less than 48 hours.

“This situation is now completely out of control, and makes an irrefutable case for government to bring forward an annual cap on political donations, and fast.”

Source link