The country has battled multiple wildfires amid record-breaking temperatures fueled by El Nino and intense drought conditions.
Published On 20 Sep 202620 Sep 2026
A massive wildfire has broken out in central Colombia, threatening the popular tourist town of Villa de Leyva, according to local officials.
The forest fire is near the Andean town in the Boyaca department, with flames engulfing the San Marcos hillside above the colonial architecture and cobblestone streets that attract more than a million visitors annually.
The blaze has already consumed 40 hectares of native forest, sending massive plumes of smoke that are visible from the town’s central square, according to Colombian authorities.
On Saturday night, Colombian President Abelardo de la Espriella posted on X that “Villa de Leyva is not alone”, pledging to mobilise all state resources to fight the fire and protect “this historical jewel” and “beautiful city that is the pride of Colombia”.
To combat the flames, the Boyaca department government said it is dispatching two aircraft. A military helicopter will also join the effort, along with firefighters from the capital, Bogota, Interior Minister Rodrigo Lara said.
The mayor of Bogota, Carlos Fernando Galan, will be sending a team of firefighters to join local crews from Tunja and Boyaca, reinforcing containment efforts and securing the urban centre, Lara said.
In the equatorial Andes, forest fires peak during the dry season, but this year they are fuelled by a severe El Nino weather pattern. Record high temperatures and lack of moisture have turned vast expanses of the Andean vegetation into tinderboxes. That has intensified a crisis that has already started 18 active wildfires across the country, according to the latest official data from Colombia’s National Unit for Disaster Risk Management (UNGRD).
The impacts of El Nino, a natural weather pattern, are felt globally and do not affect the entire South American continent in the same way, inducing extreme droughts in some regions and torrential flooding in others. This year, it comes supercharged by the effects of climate change, which is worrying many scientists, governments and aid workers.
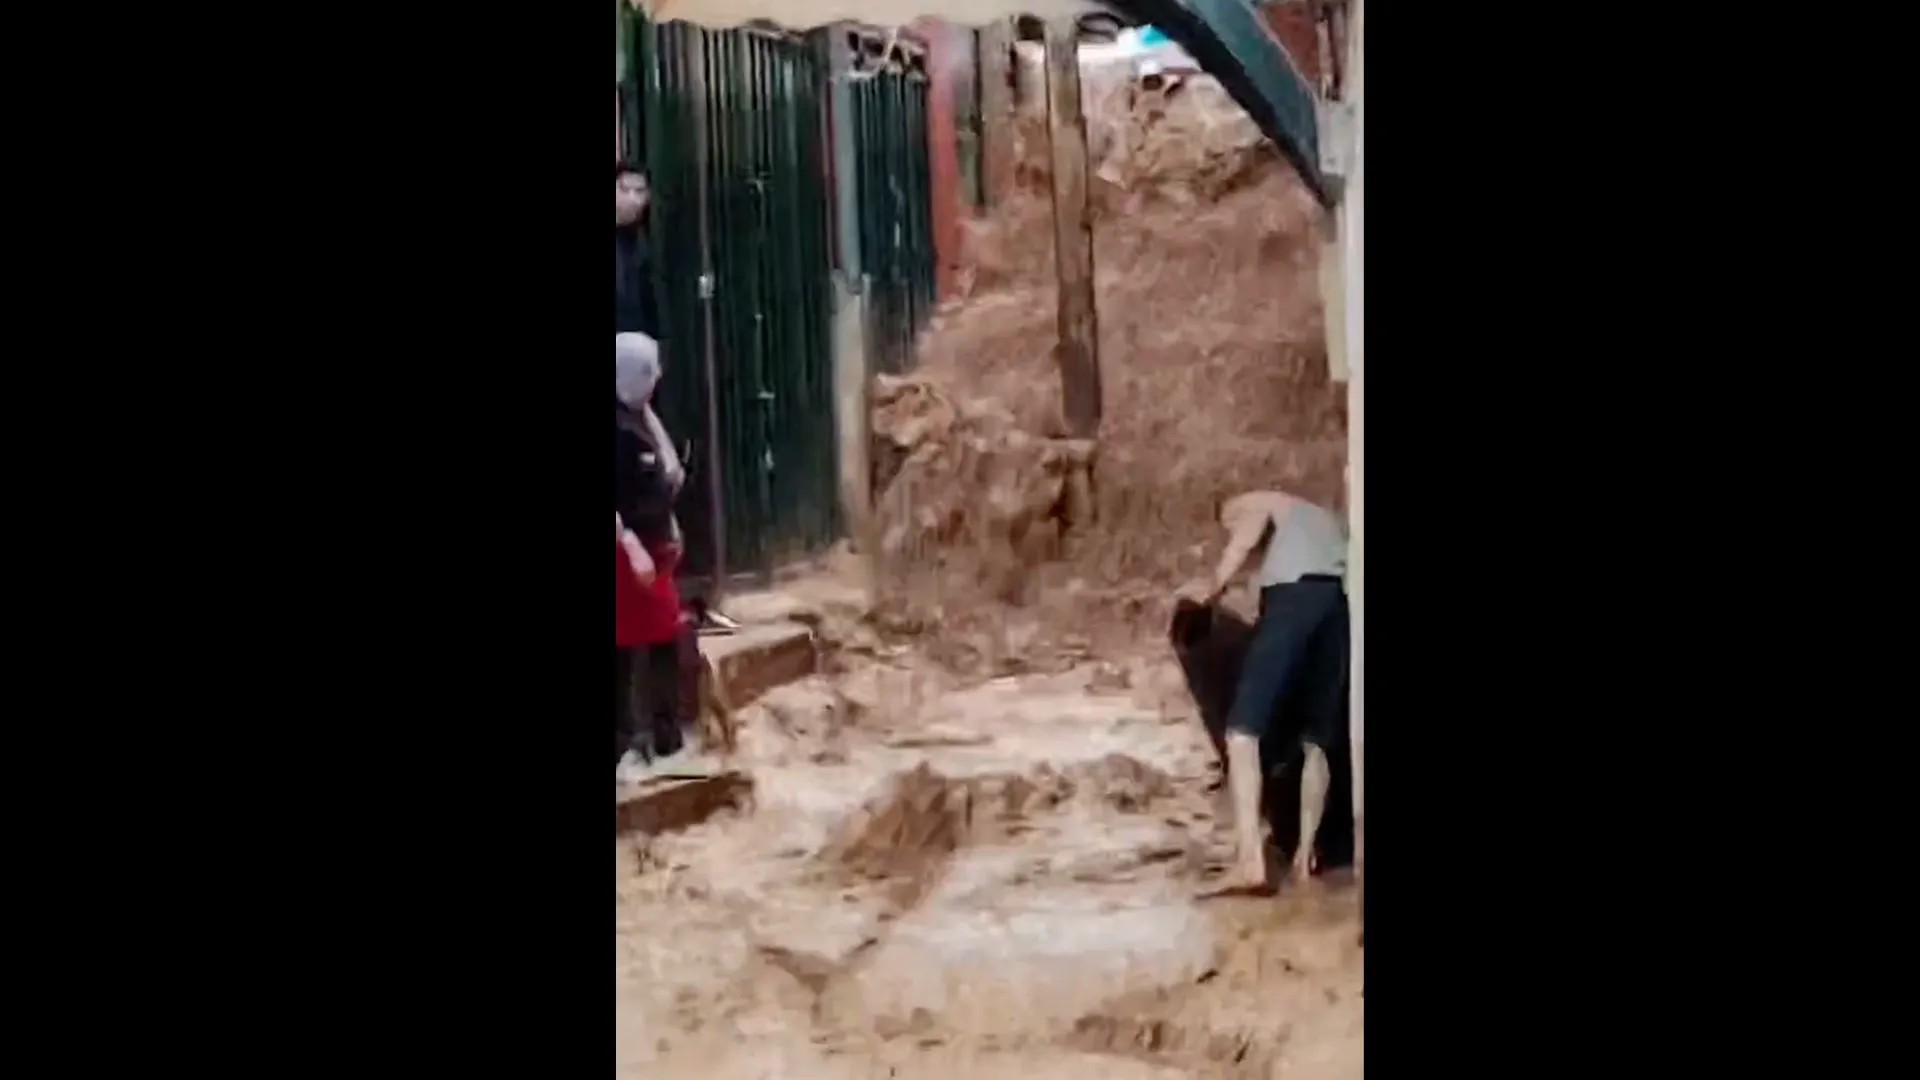
The warming of the adjacent Pacific has triggered catastrophic flash floods and landslides in countries such as Peru and Ecuador.
Unlike in the southern part of the continent, where countries including Argentina, Chile and Uruguay have been expecting unseasonably heavy rainfall, El Nino has the opposite effect in the northern part of the continent. A significant reduction in rainfall leads to severe drought conditions which can suppress cloud formation and displace normal rain patterns, driving average temperatures well above normal.
The soaring heat rapidly evaporates moisture from the ground and water basins, leaving countries such as Colombia with extended periods of drought and critically low precipitation.
“El Nino can bring devastating climate extremes on its own, but it’s unfolding today on a much warmer planet, increasing the likelihood that heat, drought, floods and fires will push communities and ecosystems beyond anything they have experienced before,” said Stephanie Roe, lead climate scientist with the World Wildlife Fund.
Central banks’ record, price-insensitive gold buying is a more credible signal of the dollar’s structural trajectory than this year’s currency markets, because FX markets are structurally bad at pricing the discontinuous, wartime-style tail risk central banks are actually hedging — so this autumn’s calmer dollar should not reassure anyone that de-dollarization has stalled.
In June, the European Central Bank made an announcement most people missed: gold has overtaken US Treasuries as the world’s single largest reserve asset. Central banks bought 289 tonnes of it in the second quarter alone — a record for that quarter and five times Q1’s pace — with Poland’s central bank openly telling investors it was “buying the dip.” Here is the part that should stop you: gold’s price fell 22% between January and September. Central banks were never more convinced buyers of an asset than while it was crashing. Either the reserve managers are wrong, or currency markets — which show none of this urgency — are the ones asleep at the wheel.
Gold peaked at $5,589 an ounce on 28 January, the same month the dollar index hit a four-year low of 95.5 and the dollar’s share of global reserves fell toward its lowest level since 1995. Both moves reflected the same story: Fed rate cuts through 2025, a US debt load past $37 trillion, and BRICS states settling more trade outside the dollar. Then the picture split. Kevin Warsh, confirmed as Fed chair in May, signalled a hawkish pivot in August; the Iran war pushed oil and inflation higher through September, and markets began pricing a rate hike rather than a cut. The dollar index clawed back to 99.46. Gold fell to $4,330. Central-bank buying did not follow the price down — Poland alone added 82 tonnes this year toward a 700-tonne target, and a World Gold Council survey found a record 45% of central banks plan to buy more within twelve months.
State the gap plainly. Two signals, same underlying question — is the dollar-centred monetary order changing — and they disagree by a wide margin. The buying signal says yes, decisively: record quarterly purchases, gold displacing Treasuries at the ECB’s own reckoning, 74% of surveyed reserve managers expecting the dollar’s reserve share to keep falling over five years, and buyers adding tonnage through a 22% drawdown rather than fleeing it. The price signal says not yet: the dollar just posted one of its sharper rallies of the year, gold is down sharply from its high, and nothing in currency markets shows the kind of stress a genuine regime shift would produce.
Stay ahead of the geopolitical week.
MD Briefing delivers expert analysis across five global fronts — the Indo-Pacific, energy, geoeconomics, European security, and the Middle East — every Monday morning. Free.
The strongest objection to trusting the buying signal is a good one, and it needs to be taken seriously rather than waved away: foreign exchange is the deepest, most liquid market in the world, turning over more than $7 trillion a day. A few hundred tonnes of central-bank gold buying — perhaps $30–40 billion a quarter — is a rounding error against that. If professional currency traders, sitting on far more capital and far better short-term information than a handful of reserve managers, saw a serious de-dollarization story unfolding, it would already be in the price. Instead the dollar just rallied. On this view, central banks are not seeing something markets are missing; they are pattern-matching off 2022, when Russia’s $300 billion in reserves was frozen overnight, and over-hedging a tail risk that has not recurred and mostly will not.
That objection assumes FX markets and central-bank reserve committees are pricing the same kind of risk, on the same time horizon, and they are not. Currency markets are exceptionally good at pricing continuous, high-frequency variables — rate differentials, growth surprises, this week’s inflation print — because that is what moves flows daily. They are structurally poor at pricing discontinuous, low-probability events until those events occur: equity volatility did not price 2008 in 2007; sovereign spreads did not price the Russia reserve freeze in the weeks before it happened. A reserve freeze, a secondary-sanctions campaign, or exclusion from SWIFT-style settlement infrastructure is exactly that kind of event — binary, rare, and catastrophic for whoever it hits — which is precisely why Poland’s central bank governor, Adam Glapiński, described his buying not as a trade but as insurance: reserves that keep the state secure “under all circumstances, including wartime, which of course we’re not expecting.” That is not the language of someone chasing momentum. It is the language of someone who manages the one asset class that keeps its value if their country is ever cut off from the dollar system, and who would rather hold it and be wrong for a decade than not hold it and be wrong once.
The buying pattern itself supports that reading. Momentum money sells into a 22% drawdown; insurance money adds to it. Central banks did the latter through the first half of this year, which is the behavioural signature of a structural reallocation program with a fixed multi-year target — Poland’s is explicit, 700 tonnes — not speculative flow riding gold’s rally. Meanwhile the dollar’s autumn recovery has an identifiable, largely cyclical cause: a new, more hawkish Fed chair and a war-driven oil shock forcing a rate-hike repricing. Neither event reverses the debt trajectory, the BRICS settlement trend, or the reserve-freeze precedent that pushed the dollar to a four-year low in January. A rally built on this year’s Fed chair and this year’s war is not proof that last year’s structural story is over; it is evidence that a cyclical force is currently strong enough to mask it.
The Scenarios
Base case (55%): The gap persists rather than resolves. The dollar holds most of its autumn gains through the current rate-hike cycle, gold range-trades below its January peak, and central banks keep buying at a steadier, slower pace toward stated targets like Poland’s 700 tonnes. Nobody is “proven right” on any particular Tuesday, because reserve diversification is a decade-scale hedge, not a trade with a catalyst date. This is the least satisfying outcome for anyone wanting a verdict, and the most likely one.
Downside case (for dollar holders): A discrete trigger — a fresh reserve-freeze or secondary-sanctions episode, plausibly connected to the still-live US-Iran war spilling into action against a third country’s assets, or a shock to Fed independence under a more political Warsh chairmanship — crystallizes the exact tail risk central banks have been hedging. Gold spikes back through its January high, the dollar index breaks below its 95.5 low, and the gap closes in weeks rather than years, vindicating the reserve managers all at once and catching FX markets flat-footed exactly as the theory predicts.
Upside case (for the dollar): The Iran war resolves, Warsh’s rate hikes cool inflation without a recession, US fiscal metrics stabilize, and BRICS local-currency settlement growth stalls on friction between its own members. Central-bank gold buying does not reverse but plateaus as reserve managers hit conventional diversification ceilings — most target 15–20% of reserves in gold, not open-ended accumulation. The gap closes gradually as price drifts up toward the buying signal over several years, with no crisis required to force the reconciliation.
The Takeaway
The dollar’s calmer autumn is not evidence the de-dollarization hedge was a mistake; it is evidence that currency markets and central-bank reserve committees are pricing two different things on two different clocks, and only one of those clocks rings in a crisis. Central banks bought through a 22% drawdown because the point of the position was never this quarter’s return.
Watch for: the World Gold Council’s Q3 2026 Gold Demand Trends report, expected in early November. A third consecutive quarter of buying that ignores price direction will confirm this is policy, not opportunism — and the moment currency markets have to agree with that policy will not be a quiet one.
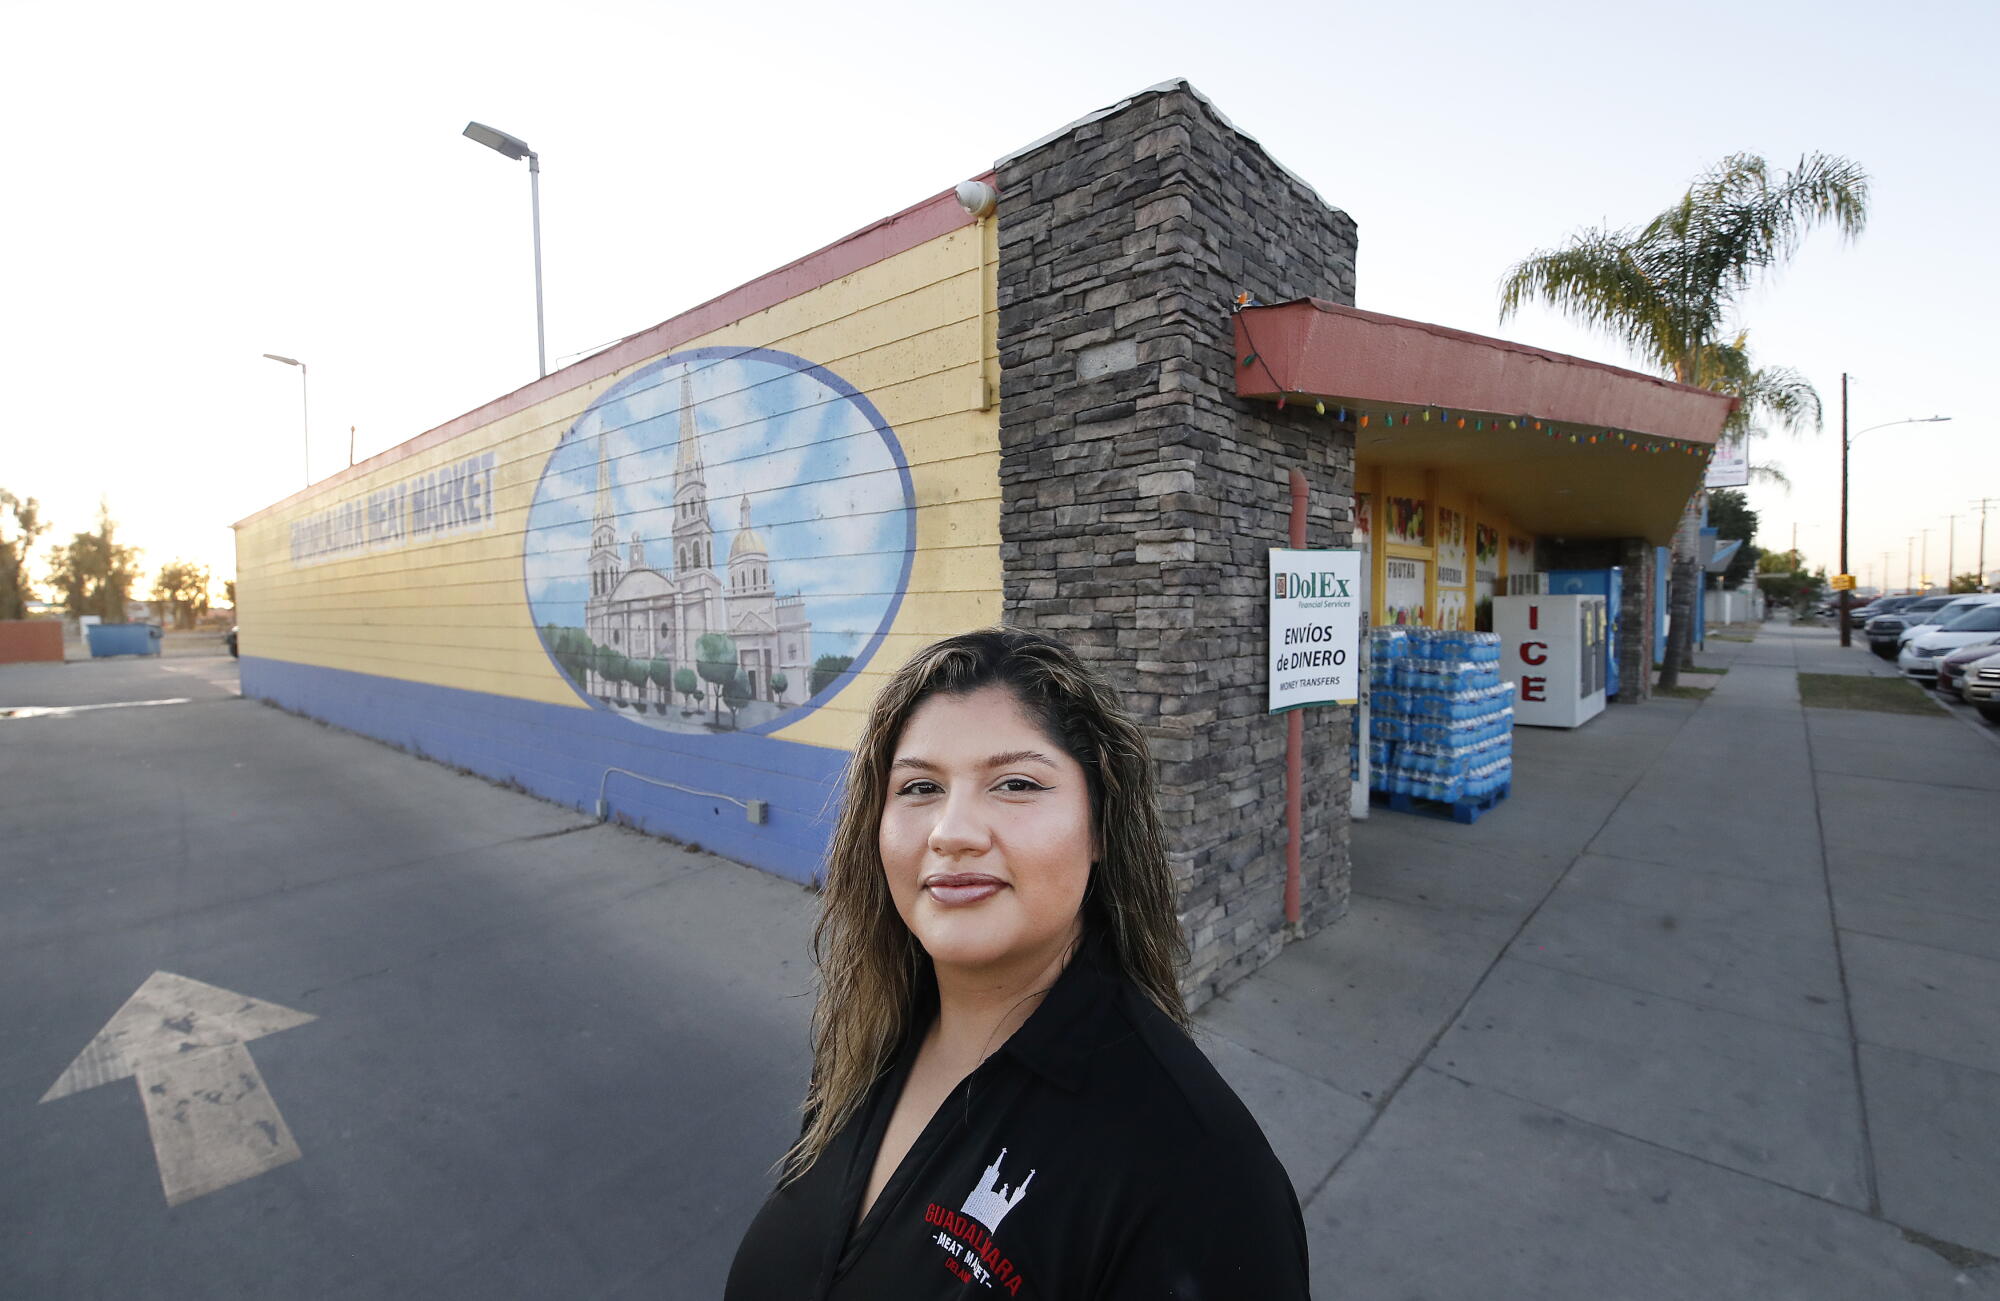
DELANO, Calif. — The rows of candies and nuts at the Guadalajara Meat Market — tamarindo con chile, seasoned pistachios, spicy paletas — sat mostly untouched as customers filtered through this carniceria in the late afternoon heat.
“You see a lot of people consuming the minimum, what they need to get by through the week,” said owner Carina Murillo, 31, as she checked out customers on a recent weekday. “Instead of buying six items, they’re buying three items.”
While customers bypass extras, like the snacks at the front counter, Murillo’s costs have gone up. Imported goods from Mexico and Canada have become more difficult to source and sometimes carry tariffs, she said. Transportation fees have risen as diesel prices respond to the war in Iran. The market’s insurance costs have risen by about a third. All of it has forced Murillo to increase prices.
“You see a lot of people consuming the minimum,” says Carina Murillo, owner of Guadalajara Meat Market. “Instead of buying six items, they’re buying three items.”
As the area struggles, Murillo, a college graduate who years ago felt motivated enough to door-knock for political causes, is among those who have become disillusioned. Those in Washington, she said, don’t understand the lives of the working people who keep the country running.
There have been “years where I feel completely overpowered to the point where I’m not motivated to take part,” said Murillo, who didn’t vote in 2024 but plans to do so in November. “That’s what happens when you feel discouraged or like nothing’s going to change.”
The economic strife plaguing Americans is clear in this rural, majority-Latino Central Valley congressional district, home to the state’smost competitive House race, the closely watched contest between Republican Rep. David Valadao and Democrat Randy Villegas.
Democrats hope the national economic angst will translate into big turnout in the midterm elections, but some in this region worry that years of financial struggle may depress voters’ desire to participate rather than motivate them.
Rep. David Valadao (R-Hanford) presides over a congressional hearing in March. The Republican is in a race against Democrat Randy Villegas that is considered a toss-up.
(Allison Robbert / Associated Press)
And Republicans, who rely on their party turnout beating that of Democrats in rural areas, also face the risk that frustration with the current political climate could dampen enthusiasm.
“Before they can think about Valadao, before Trump or Gavin Newsom or who’s going to run, families are concerned with the immediate: paying the rent, having the food on the table,” said Eliseo Gamiño, who heads the Central Valley Leadership Round Table, a coalition of Latino community leaders and elected officials. “You can’t be thinking about voting when your kids are hungry.”
Few voters who spoke to The Times in this swing district were decided on which party to support in November — or whether to vote at all. Such undecided voters will likely decide the election outcome, and persuading them is the key challenge for both parties as November nears.
Alexa Lopez sweeps up at closing time on a slower than usual Friday that saw one dress sold at Christina’s Fashion in Delano.
In a district that is the third-youngest in population in the country, the simmering uncertainty among Gen Z and millennial voters in particular could affect turnout or results.
Thirty-one percent of its voting-age population is 29 or younger, according to the Tufts University research center CIRCLE, which tracks youth civic engagement, making it among the top swath of House races in which young people could swing the outcome.
California’s swingiest district
The 22nd District, carved from the state’s agricultural epicenter, is one of fewer than two dozen toss-up races nationwide that will likely determine which party controls the U.S. House in the second half of President Trump’s current term. It is also among several high-stakes races nationwide that will test progressive candidates.
Valadao’s seat has long been considered a vulnerable one; Democrats added about 100,000 Fresno residents to the district under Proposition 50’s new map in a bid to help their chances. The boundaries include swaths of Kern, Kings and Tulare counties, along with a very small piece of Madera County.
“It’s going to be crucial in an area that is more purple, more bipartisan, where it’s very clear it can go either way … that these candidates make an effort to get those voters on their team,” said Brittany Martinez, a California-based Republican strategist.
Valadao, 49, who comes from a dairy farming family, is well known in the district and has repeatedly secured victory in close races, retaking the seat in 2020 after losing it in 2018’s blue wave. He saw a close race in 2022, then won by nearly seven percentage points in 2024, outperforming Trump.
His biggest vulnerability this time around may be his vote for the One Big Beautiful Bill Act, which included steep cuts to Medicaid. Local hospitals are bracing for funding cuts, though a carve-out may keep many valley residents from losing coverage. The district has the highest proportion of Medi-Cal recipients of any in the state, with 67% of residents enrolled as of 2025, according to the California Health Care Foundation.
Valadao spent part of the August recess touring the Central Valley for private meetings with local entities including a hospital, a housing program, a sawmill and a school district, and held a telephone town hall last week. Democrats have criticized him for not holding face-to-face voter events, including public town halls.
Democratic candidate Randy Villegas chats with residents during an August town hall in Hanford.
Villegas, 31, a professor and school board member who was endorsed by Sen. Bernie Sanders (I-Vt.) and is aligned with the Working Families Party, bested a Democrat backed by the party’s House campaign arm to win the nomination.
Villegas has banked on a more public-facing approach to win over swing voters — recently handing out popsicles from a pushcart he wheeled around a Labor Day event in Bakersfield, for instance — a strategy his campaign calls “going everywhere.” Republicans have criticized his record as too far left for the moderate district.
Both candidates have attempted to lean away from partisan narratives. Valadao rarely mentions Trump on social media and did not attend the president’s Republican convention in Dallas last week; Villegas has worked to frame the progressive issues he champions as an effort to help Central Valley voters rather than an ideology.
Trump carried the district as drawn now by less than 2 percentage points in 2024. Since then, residents say they have felt squeezed by housing, gas and grocery prices. The war in Iranhas pinched Central Valley farmers — already struggling withwater supply and other issues — by driving up fertilizer prices.
Ailyn Flores, center, picks up balloons for a party at Big Delano Discount store.
Tyler Stidham, 28, and her husband recently moved back to Lemoore from San José with their 1-year-old in order to live with family because they could no longer afford their own place.
“Rent got too high and having a family is expensive,” she said as the couple waited for their order from a food truck at the Hanford farmers market on a recent Thursday evening. They have cut out family trips and started meal-planning and budgeting to save money.
Stidham said she is planning to vote and hoping government leaders can make life more affordable. Her husband recalled a favorable impression of Valadao after once meeting him. Stidham isn’t sure who she’ll be casting her vote for.
“I haven’t done my research [yet],” she said.
Young voters said they felt frustrated waiting for a better economy that has yet to materialize.
“I feel like the government is playing in our face. I feel like everything is a show,” said Emma Woodward, 23, of Hanford.
The Sierra movie theater has closed down in Delano, Calif.
(Gary Kazanjian / For The Times)
A store manager at a coffee chain, Woodward bought a house last year to avoid throwing money at increasingly high rent payments, but it has been “hard to survive.” She got a roommate to help with costs, but the two of them sometimes find themselves using food drives for groceries. She has cut out “fun spending,” including concerts and travel.
Woodward said she wanted to vote in order to send the message to Congress that the economy needs improvement. She, too, wanted to research the candidates further; she leaned toward Villegas but was not yet convinced.
‘Whatever happens happens’
Valadao and Villegas must also battle to reach apathetic voters — those who may sit the election out or who are fed up with both parties. In one indication of voter fatigue, local organizers have found it a challenge to register new voters this year.
Dresses on display at Christina’s Fashion store after closing time on a quiet Friday night in Delano, Calif.
People who are unregistered often express mistrust in the government and the feeling that “nothing’s going to change,” said Biviana Camacho, 23, civic engagement program manager for Loud for Tomorrow, a youth organizing group based in Delano that runs voter registration events.
“A lot of folks have been in survival mode for such a long time,” she added, as the group worked on planning a fall event series on a recent afternoon. Their goal: 20 to 25 new registrations per event.
The group’s head of membership, Rosanai Paniagua, 28, agreed. “Here, there’s not a lot of hope because people haven’t seen what good policy could do for them,” she said. “A lot of apathy, for sure, because change hasn’t really happened here.”
Marco Estrada, 20, taking a break outside the Main Street barbershop where he works in Delano, said he wasn’t sure he could imagine anything Congress could do for him. He’s never voted and doesn’t plan to in November. His two co-workers said the same.
“Whatever happens happens,” Estrada said.
Valeria Valdez, a College of the Sequoias freshman, said she was planning to vote in her first election and said the government should help lower gas prices. The 18-year-old wasn’t sure, though, whether she would make a decision in the House race.
“It feels pretty far away from me, to be honest,” she said. “I just want to do what I can for our community and not focus on how corrupt the government is.”
That sentiment is part of what Villegas is aiming to target as he meets voters.
“It’s easy to feel cynical and apathetic in a moment where so many things seem stacked against us,” Villegas said in an interview. “But I tell people that … their vote and their voices do matter, otherwise we wouldn’t have billionaires and corporations spending millions of dollars trying to influence these election outcomes.”
A spokesperson for Valadao did not respond to a request for comment. Valadao said on a Washington Sun podcast in January that he “absolutely” worries about Republican voter enthusiasm, but noted it was a problem on both sides of the aisle. Earlier this month, he conveyed confidence about his race.
“I’ve won in these types of races. I can win again,” he told the Associated Press. “I think we should be fine.”
Inside Murillo’s market, business picked up as 5 o’clock neared. Murillo rang up tortillas, cuts of meat, and three-liter Mexican soda bottles. She advised a customer about treating a bug bite, helped a man wire money and cajoled a city worker about getting a sidewalk repair.
Congress should “definitely” be helping communities like hers, she said. She plans to research her voting options so she can participate in November. But trusting political candidates, she mused, can feel like a risk for voters.
“Whether they execute what they promise or not,” she said, “that’s shown with time.”
Market odds put a quarter-point hike at close to certainty, which would lift the European Central Bank’s deposit rate from 2.25% to 2.5%.
What makes this a difficult call is not whether the ECB acts, but why, and whether the reasoning survives contact with the data.
The path here has been compressed as the ECB raised rates on 11 June for the first time in three years, lifting the deposit rate from 2% to 2.25% in response to the energy shock from the Iran war, and then held rates in July while Christine Lagarde pointed hawkishly towards September.
August’s inflation figures removed any remaining doubt with eurozone inflation hitting 3.3%, up from 2.9% in July and the highest since September 2023, as energy inflation surged to 14.3% from 10.3%.
The inflation is not spreading
Look beneath the headline inflation and the picture inverts.
Core inflation, which strips out energy, food, alcohol and tobacco, actually fell to 2.4% from 2.5%. Services inflation, the component most closely tied to wages and domestic demand, dropped to 3% from 3.3%.
In other words, there is still little evidence that expensive energy is feeding through into everything else. That is what economists mean by “second-round effects”, and their absence is the strongest argument against tightening.
The ECB’s own research also supports the distinction.
In a paper published on Tuesday, ECB economists found that adverse energy supply factors, driven by geopolitical tensions, accounted for around 90% of the rise in energy inflation between January and May.
“This time the energy supply shock dominates, while demand and public policy stimulus have minor roles,” the economists wrote, adding that “these differences are key to explaining why monetary policy responses differ.”
The 2021-22 surge, by contrast, came from “a combination of large and unprecedented supply and demand-side factors,” which is why the ECB then “raised interest rates forcefully and persistently” rather than gradually.
The national spread across the EU further underlines how uneven this is.
August inflation ran at 4.5% in Spain, 2.9% in Germany and 2.7% in France, three economies facing the same energy shock with very different results, all governed by one interest rate.
Economic growth is the other complication.
The eurozone has proved more resilient than expected, which ING attributes partly to luck, partly to Asian competitors suffering more from the closure of the Strait of Hormuz and partly to fiscal stimulus. However, resilience does not mean the growth could not, or should not, accelerate.
ING characterises Thursday’s expected move as “another insurance rate hike”, or “a dovish rate hike,” noting that even at 2.5% the deposit rate sits within the range the ECB itself considers neutral.
Going further would mean deciding restrictive policy is required, which would be a different judgement entirely.
Everyone is looking to hike at the same time
The ECB is not acting alone, and that matters for the euro.
The Federal Reserve meets on 15 and 16 September, with Chair Kevin Warsh having used his first Jackson Hole address to argue that financial conditions are not restrictive and underlying inflation has not improved.
Investors had put the odds of a US hike at roughly one in three before those remarks, but now price a 60% chance the Fed hikes the target range from 3.5%-3.75% to 3.75%-4%.
The Bank of Japan follows on 17 and 18 September, with markets pricing an 80% to 90% chance of a move to 1.25%.
On the other hand, the Bank of England is expected to hold rates at 3.75% on 17 September as it currently maintains a much higher interest rate than the rest.
If the Fed were to hike while the ECB held, the dollar would strengthen against the euro and that would cut both ways for Frankfurt.
A weaker euro makes European exports more competitive, but it also makes imports dearer, and since oil and gas are priced in dollars, it would push up precisely the energy costs driving the inflation problem in the first place.
Overall, we can assume a September rate hike is a done deal for the ECB but we can also project that it won’t solve the central bank’s current dilemma of raising borrowing costs against an inflation it cannot reach, while withdrawing support an economy could still use.