billions

These Californians spent 0.07% of their billions to oppose Prop. 40

About 260 California billionaires would be subject to Proposition 40’s one-time 5% wealth tax according to the Forbes Real-Time billionaires list. Just 30 of those billionaires or their spouses, or 1 in 8, spent money opposing Proposition 40, the billionaire tax, according to a Times analysis of recent campaign filings.

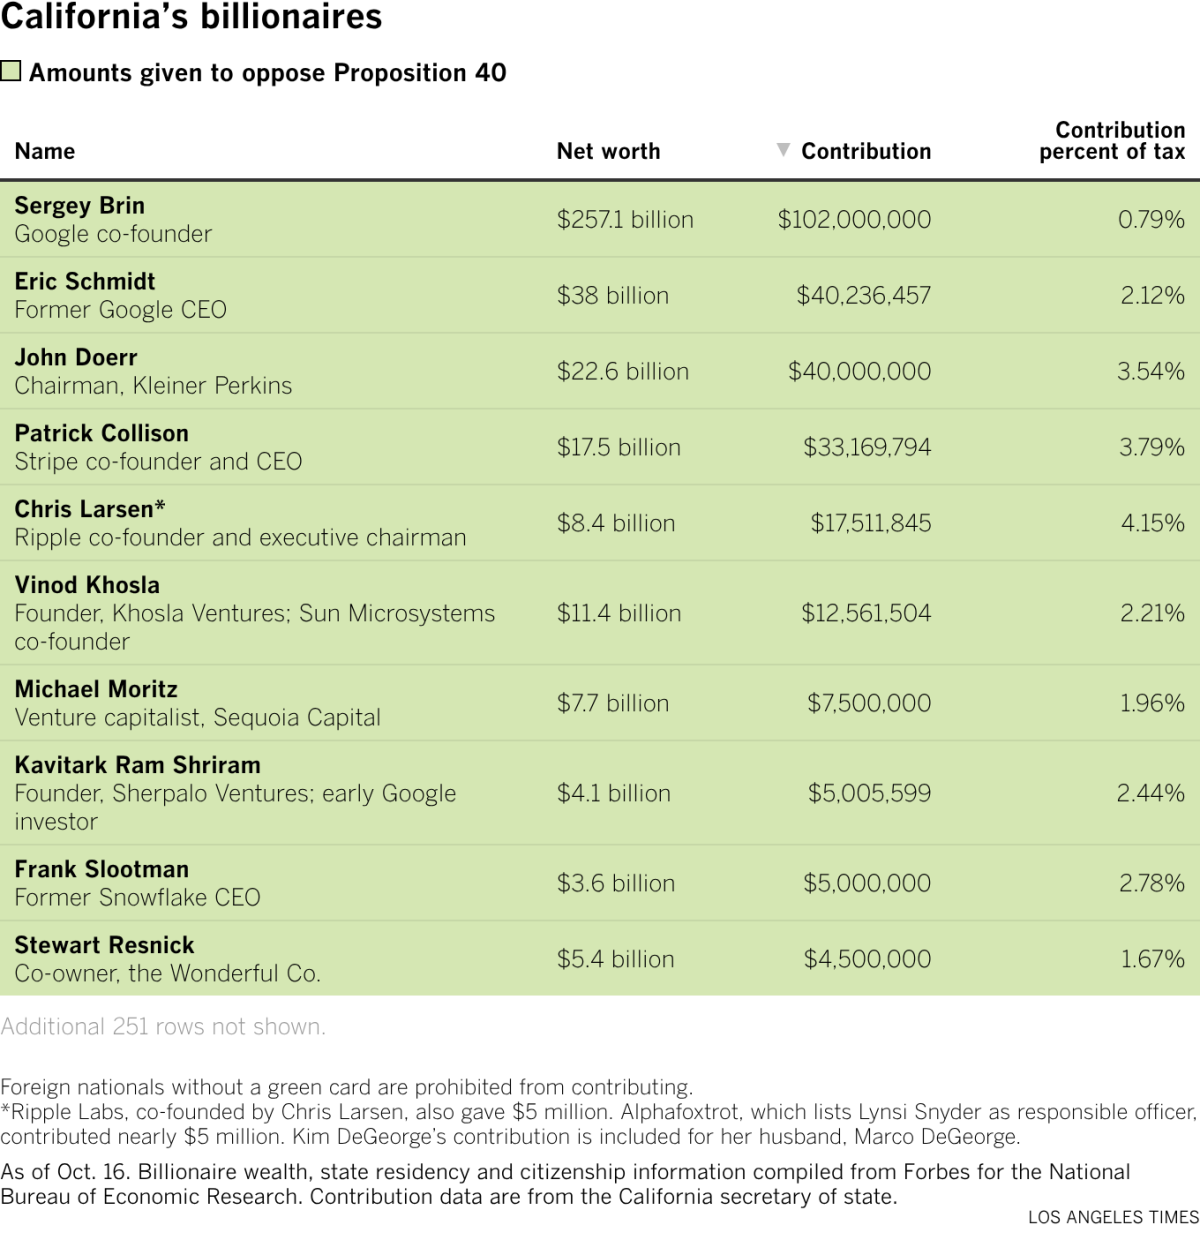
Billionaires have individually contributed $293 million to oppose the tax measure and to support Proposition 41 and 42, which would nullify the billionaire tax if either receives more votes, according to a Times analysis. Sergey Brin, co-founder of Google, has given $102 million, more than a third of all billionaire money against the measure. But this is less than 1% of his estimated tax bill.

Several billionaires also contributed to the political action committee of the California Business Roundtable, which is spending to oppose Proposition 40 and support Proposition 43. Peter Thiel gave $3 million, Eric Schmidt gave nearly $2.6 million, Marco DeGeorge’s wife, Kim, gave $1.9 million, Chris Larsen gave $750,000 and Douglas Leone and his wife gave $500,000.

Proposition 40 would apply the tax to billionaires who were California residents on Jan. 1, 2026, and the taxable amount would be based on their net worth on Dec. 31. The tax is payable over five years.

Altogether, these individuals would owe at least $107 billion in taxes, according to an analysis by economists Jasper Boll, Emmanuel Saez and Gabriel Zucman. Their research was published in the National Bureau of Economic Research in August. Saez and Zucman are also architects of the tax proposal.

This amount is 5% of their combined estimated wealth by Forbes as of Oct. 16 and factors in a certain amount of tax avoidance and evasion. Spread across all 39 million Californians, the $107 billion would be roughly $2,700 per person. The Public Policy Institute of California estimates that the median household net worth in California was $303,000 in 2023.

The four richest Californians — Sergey Brin, Jensen Huang, Larry Page and Mark Zuckerberg — would owe 40% of the estimated taxes to be collected from the billionaire tax, according to a Times analysis. Their wealth largely comes from ownership of stock in extremely high-value technology companies.

Their net worth would increase 5% in about four months if their stock investments continues to grow as they have since December.

California billionaire wealth grew nearly threefold from 2022 to 2026, according to Times analysis of Forbes data collected by Boll and his colleagues, and much of that growth was not taxed. Billionaires’ taxable income is small compared with their wealth, because most of that wealth is invested in public stocks, and gains aren’t taxed until the stock is sold.

Page and Brin disclosed no taxable income in three of the years since 2019. Many others had similarly no publicly disclosed income. For that reason, Boll and his colleagues estimate that the Proposition 40 one-time tax would raise more than $100 billion, “with comparatively minor impacts on income tax revenue” from some billionaires leaving the state.

Based on Meta’s filings, the economists estimated that Zuckerberg’s taxable income was about $947 million in 2025, just 0.4% of his net worth.

Over the summer, Zuckerberg shared with Meta advisors his plans to relocate outside California to avoid the possibility of a significant reduction in his control over the company as a result of selling enough stock to fund a 5% tax. The advisors determined that Zuckerberg’s leadership presence at Meta headquarters was essential to the company’s success. On Wednesday, Meta announced the creation of new, nonvoting Class C common stock, which will allow Zuckerberg to sell the amount he needs to pay his potential tax bill while maintaining his voting power in exchange for his commitment to remain in the state for eight years.

Researchers at the Hoover Institution estimate the revenue to the state to be closer to $40 billion based on reports of billionaires’ residential purchases outside the state before and after Jan. 1 and their estimate of unannounced residency moves.

Chris Hoene, executive director at the California Budget and Policy Center, a nonpartisan group, said the residency question hinges on the amount of time spent living in the state. “Purchasing property in another location does not mean that they have changed their residency,” he said.

Ultimately, the state’s Franchise Tax Board, responsible for administering the tax, will have to assess residency. Hoene says this task is “easier for them to do than people realize.” The board will also calculate the amount of wealth subject to the tax using publicly available stock information and private assessments of personal property, such as artwork and jewelry. Real property, pensions and retirement accounts would be excluded.

Opponents of Proposition 40 are concerned that the threat of wealth taxes will lead to billionaires continuing to leave the state, resulting in a long-term decrease in state income tax revenue. Forbes recently reported that Brin registered to vote in Nevada last year. Peter Thiel disclosed Dec. 31 that he opened a new office in Miami; Florida has no wealth tax or income tax. But in July, he purchased a $130-million mansion in Bel-Air.

“The reality is the income tax loss can never get anywhere near the scale of what the wealth tax gain would be,” Hoene said.

Ninety percent of that gain would be spent on healthcare services to fill a gap in Medi-Cal from losses in federal funding that the measure’s authors estimate would total $190 billion over the next 10 years. Medi-Cal provides healthcare coverage for one-third of low-income Californians, according to the Legislative Analyst’s Office.

Gov. Gavin Newsom opposes a California-only tax and has instead called for a national wealth tax. Democrat Xavier Becerra and Republican Steve Hilton, who are running to replace Newsom, have spoken out against the tax. Other opponents include the California Teachers Assn., the California Medical Assn., and Planned Parenthood Affiliates of California. Supporters include Service Employees International Union, U.S. Sen. Bernie Sanders (I-Vt.), the California Democratic Party and the California Federation of Labor Unions AFL-CIO.

Times staff writer Queenie Wong contributed to this report.
Source link

After federal subpoenas, Mark Walter tapped a Magic Johnson-linked firm for billions in loans

In February, after getting served with subpoenas in a federal criminal investigation, the billionaire sports mogul Mark Walter’s insurance companies abruptly stopped lending to him.

But within weeks, new loans started rolling in from a different source: a financial firm whose owners include his business protege, basketball legend Earvin “Magic” Johnson.

Amistad Financial Group, a holding company that counts Johnson as a board member and minority shareholder, loaned about $1.26 billion to Walter’s companies between March and June of this year, according to a Bloomberg News review of business records and a person with knowledge of the activity who asked not to be identified discussing sensitive matters. Another $1.06 billion went to intermediaries that routinely serve as conduits for loans to Walter.

The combined $2.31 billion of lending, which hasn’t been reported previously, highlights the way Walter relies on debt to fund his business empire, and Amistad’s role. Even before this year, the firm’s insurance units had provided billions of dollars of loans to Walter affiliates, filings show. It also acted as an intermediary to help him tap loans from his own insurers, Bloomberg reported previously – transactions that are now part of the federal investigation.

Walter himself owns a single-digit voting stake in Amistad but doesn’t control it, participate in its management or sit on its board, according to a person familiar with its operations.

Representatives for Walter’s TWG Global holding company and for Johnson did not respond to messages seeking comment.

A former point guard who led the Los Angeles Lakers to five National Basketball Association championships, Johnson has described Walter as a business mentor. They have done deals with each other for more than a decade, including Johnson’s participation in the Walter-led purchase of the Los Angeles Dodgers baseball team. Johnson doesn’t serve on Amistad’s three-person executive committee, and it’s unclear whether he was involved in or aware of the lending decisions. Some of Amistad’s insurance units are led by Eric Holoman, Johnson’s former business manager.

The federal investigation, being pursued in parallel by the U.S. Department of Justice and the Securities and Exchange Commission, focuses on Walter’s insurance companies’ failure to disclose that more than $20 billion of loans on their books went to his other businesses.

The recent lending came from two Amistad subsidiaries, Equitrust Life Insurance Co. and Heritage Life Insurance Co. It’s unclear whether Amistad executives were aware of the investigation when the loans were made. Walter’s insurers disclosed the subpoena in a regulatory filing on June 26, but the filing did not get much attention until Bloomberg News reported on it in July. Information about lending activity after June 30 won’t be disclosed until next month.

Walter is now scrambling to reduce debts to his own insurance companies, Delaware Life Insurance Co. and Clear Spring Life and Annuity Co., in part to assuage concerns from ratings agencies about the scale of affiliated lending. He has agreed to sell the Lakers at a $12.5 billion valuation to free up cash and proposed a $6.5 billion debt swap with Delaware Life. This week, the insurer said it had regulatory approval to proceed with part of that, swapping $3.8 billion.

Because he doesn’t legally control Amistad, Walter is under no such pressure to reduce his reliance on its money.

His ties to Amistad are deep. Its official corporate address is the Chicago office suite that houses Walter’s family office. Walter’s financial firm, Guggenheim Partners, serves as an investment manager for both Equitrust and Heritage Life.

Walter’s brother-in-law serves as president of Heritage Life. Walter used to control Equitrust when it was owned by Guggenheim. He sold it to Johnson in 2015, and Johnson sold it to Amistad last year.

Recipients of the new Amistad loans include a company through which Walter holds his stake in used-car seller Carvana Co., and another containing his interest in the Billie Jean King Cup, the women’s tennis competition that he has backed since 2023. The destination for most of the money wasn’t clear from regulatory filings.

New LLCs

The federal investigations revolve around how Walter’s insurers came to lend so much money to his other businesses without disclosing the arrangement to their regulator, the Delaware Department of Insurance, as required. As of the end of last year, the amount of money they had invested in affiliates was $24 billion, or about 45% of the companies’ total invested assets.

Much of the money was routed to loans for newly created limited liability companies with no public profile. These LLCs were created by Amistad and other intermediaries, which in turn sent the money back to Walter.

In January and early February of this year, that lending arrangement continued, with Delaware Life loaning $730 million to newly formed LLCs that then sent the money to Walter’s other businesses, regulatory filings show. That stopped after the U.S. Attorney’s Office in Manhattan sent the grand jury subpoenas.

But in March, Amistad’s Equitrust sent $500 million to 10 LLCs. These borrowers had been formed days earlier by Federico Hermida, a Miami-based executive at ABS Capital Co., a longtime business partner of Walter’s that has often served as an intermediary in deals between Walter and his insurers. In June, Amistad’s Heritage Life sent $303 million to a subset of the Hermida borrowers. A representative of ABS declined to comment.

Heritage Life also sent about $253 million to LLCs set up by two other intermediaries that Walter has used for loans in the past: the real estate firm Bradford Allen and Hudson Trading, both based in Chicago. Representatives of Bradford Allen didn’t respond to requests for comment, and Hudson Trading declined to comment.

The remaining $1.3 billion of loans were made to companies that are known to be part of Walter’s business empire, or that were formed by a Walter employee, or were confirmed by the person with knowledge of the matter.

Most of the loans carried interest rates of 8 percent or more, and were due to mature in September or earlier. The insurers won’t have to disclose whether those loans were repaid, extended or replaced with new debt until they file their next quarterly financial reports next month.

Despite the borrowing from Amistad, Walter had not significantly reduced his debt to his own insurance companies by June 30, the date of the most recent regulatory filings. After climbing from $24 billion to $25 billion through March, the amount of affiliated investments dropped to about $24 billion as of June.

Mider and Li write for Bloomberg.

Source link

Why do Iran’s oil ‘intermediaries’ owe the government billions? | US-Israel war on Iran News

As the United States maintains a naval blockade of Iran’s ports and imposes more sanctions on its oil exports, Tehran is confronting another problem: billions of dollars in revenue from previous oil sales that it says have gone missing.

A spokesperson for Iran’s judiciary said in September that a network of oil intermediaries known as “trustees” owed the Iranian government between 10 billion euros ($11bn) and 11 billion euros ($12bn). That figure was equivalent to half of the total oil revenue projected in Iran’s government budget for the current fiscal year.

Recommended Stories

list of 3 itemsend of list

US officials, including Treasury Secretary Scott Bessent, have tied Iran’s struggles to access oil revenues as evidence that its economic pressure campaign is having an effect. In August, Bessent said that “Iran’s shadow banking system was buckling” under pressure from the US campaign against the country, which has been ramped up as Washington seeks a way to force Tehran to capitulate in the war between the two countries, launched by the US and Israel in late February.

So who are the oil intermediaries, why does Iran depend on them, and what has happened to the billions of dollars they owe? Let’s take a closer look.

The debt, and the crisis it has created for the Iranian government, both stem from an oil-sales arrangement Tehran adopted in 2012 in response to US sanctions targeting Iranian oil exports.

American and European sanctions targeting Iranian oil sales and revenue collection began in 2012. The stated rationale behind both sets of measures was that revenue from oil sales helped finance Iran’s nuclear programme and that restricting Iranian oil exports could prevent the programme from advancing.

In response, the Iranian government devised a way to circumvent international sanctions on its oil sales. Unable to sell oil through the Oil Ministry and receive the proceeds through the Central Bank, it began selling oil to domestic buyers or using it to settle outstanding obligations to institutions and organisations owed money by the state.

This arrangement gave rise to a network of oil intermediaries often referred to in Iran as the “trustee network”. Rather than selling all its oil through official government channels, the state entrusted crude oil to institutions, individuals and companies to sell on its behalf. The proceeds were supposed to be transferred to the government’s treasury, with the sellers or recipient institutions subsequently recovering their agreed costs and outstanding claims. Some institutions sold the oil themselves, while others contracted private trading companies to handle the sales.

The Oil Industry Pension Fund, established for retired Oil Ministry employees familiar with the oil-sales process, was among the first institutions to receive crude oil for sale. Other recipients included Khatam al-Anbiya Construction Base, a major hub for large-scale infrastructure projects. Even the municipal police received payments owed to them by the government in the form of crude oil.

Effect of the nuclear deal

Even in those early experiments, discrepancies emerged between the revenue expected from oil sales and the amounts sellers actually deposited into the government’s treasury. These discrepancies eventually gave rise to some of Iran’s largest economic corruption cases.

The accounting discrepancies and the government’s inability to recover money from private sellers entrusted with Iranian oil persisted until 2016, when the Joint Comprehensive Plan of Action (JCPOA) nuclear deal was signed and when sanctions on Iranian oil sales were lifted. The government was subsequently able to regain control over oil sales.

Individuals who had sold Iranian oil but failed to return the proceeds were imprisoned. With the ability to sell oil again through legal and transparent channels, the government was able, for a time, to manage its oil revenues and spending with greater control.

How did money from oil sales go unreturned?

After US President Donald Trump withdrew the United States from the JCPOA in 2018 during his first presidential term, the Iranian government once again had to rely on private oil traders to sell its oil. But the problems associated with selling oil through intermediaries rather than official state channels, including delays in returning revenues, accounting discrepancies, debts owed by oil sellers to the government, and the occasional seizure of Iranian oil shipments at sea, once again constrained the government’s ability to manage its oil revenues.

Moreover, the US expanded its sanctions beyond Iranian government institutions and interests, adding bank accounts involved in transactions with the Iranian government, currency-exchange offices, companies, and individuals to its sanctions lists. As a result, the time between individuals participating in Iran’s oil-trading network and being sanctioned themselves, along with their assets and companies, and having their accounts blocked or frozen grew progressively shorter.

This contributed to an accumulation of debts owed by sanctioned oil traders – no longer able to access their accounts – to the government. It also left Iran with little choice but to expand its private oil-sales network. That meant increasing the number of people involved in trading Iranian oil, reducing the volume of oil allocated to each individual or company and, ultimately, increasing the risk that the proceeds would not be returned.

Iranian officials have also accused trustees of exploiting the sanctions workarounds to enrich themselves.

The billions of dollars owed by private oil sellers to the Iranian government are a combination of outstanding payments, disputed financial obligations and allegations of corruption. Iran’s judiciary chief recently addressed the issue, warning that oil sellers who refuse to return the proceeds from oil sales will face legal action. But such warnings do not change the sanctions environment or remove the obstacles that prevent some oil sellers from returning the money.

Source link