

Eurozone annual inflation accelerates to 3.8% in September, topping expectations (EUR:USD:)
- Eurozone annual inflation accelerated to 3.8% in September, up from 3.2% in August and above market expectations of 3.6%, according to preliminary estimates.
- Core inflation, which excludes energy and food, rose to 2.5% from 2.4%, in line with expectations.
- CPI

Who’s Funding the Asian Century?
Hong Kong listing reforms and surging deposits show regional markets funding Asia’s future.
This article appears in the October issue of Global Finance Magazine.
When the International Monetary Fund and World Bank convene their annual meetings in Bangkok this October, it will be the first time the joint gathering has returned to the city in 35 years. IMF officials have taken to calling Asia the “driving force” of the global economy — shorthand for a region that accounts for one-third of global gross domestic product, 29% of global public equity market capitalization, 56% of listed companies and 52% of global venture capital activity, according to the Organization for Economic Cooperation and Development’s Asia Capital Markets Report
The question for chief financial officers isn’t whether Asia is growing — it’s whether the region can finance that growth on its own terms, or whether it still depends on capital, listings, and liquidity from the West. The answer, based on bank data, exchange records, and conversations with practitioners and economists on the ground, turns out to be both.
Alex Ibrahim, until recently corporate CFO of Yanolja, the Seoul-headquartered travel technology company, said Asia is a picture of change. Its financial sector has matured in the decades since the 1960s to 1990s, when headlines proclaimed the rise of the Asian Tigers and countries became synonymous with rapid, export-driven industrialization funded largely from abroad.
“Back then, the economies were growing very fast, and a lot of the money was coming from the U.S. to invest,” said Ibrahim, who before joining Yanolja spent nearly a decade running international capital markets at the New York Stock Exchange. “If you look now, capital has developed locally and the financial infrastructure in Asia is much more robust.”
Marc Iyeki, a board advisor who formerly led the NYSE’s Asia-Pacific listing sector and shepherded about 100 companies to market, said the shift reflects a change in decision-making. “Decades ago, the money was in New York. Decisions were made in New York,” he said. Since then, regional private equity and venture firms have placed people on the ground in Asia who understand the home market and make the calls themselves, often after training at global firms and bringing that experience back. The region has also produced homegrown standouts such as PAG, Hillhouse Investment, MBK Partners, and Peak XV Partners.
That evolution is seen in how Asia’s own exchanges are performing. Over the past ten years, Hong Kong’s equity market has moved through cycles in liquidity and new issuance, but 2025 marked a rebound from the post-pandemic slowdown. Average daily turnover on the Hong Kong stock exchange rose from HK$66 billion in 2016 to HK$248 billion in 2025, nearly 3.7 times the level a decade earlier. Initial public offering proceeds were more volatile: HK$194 billion was raised in 2016, followed by several weak years before rebounding to HK$285 billion in 2025.
Japan’s exchange has risen more steadily. On the Tokyo Stock Exchange’s Prime Market, average daily trading value for domestic common stocks rose from 3.2 trillion yen in fiscal year 2022 to 4.3 trillion yen in fiscal year 2023, and 6.7 trillion yen in fiscal year 2025.
Iyeki recalled that when Alibaba first wanted to list in Hong Kong in 2013, the exchange turned it away over governance requirements — and New York landed the IPO. Losing a flagship company forced a reckoning. Some in Hong Kong worried that loosening listing rules would weaken protections for retail investors; others warned the market would be “hollowed out,” as local companies sought listings in New York and London. Hong Kong changed its rules, and years later Alibaba came back for a dual listing. The infrastructure now absorbing record IPO volumes and Alibaba-scale capital was built, in part, out of that earlier loss.
One of the people behind that financial infrastructure is Larry Li, a Hong Kong-based fintech founder who worked on Stock Connect, a market access program that links the stock markets of mainland China and Hong Kong. It has become a major cross-border equity trading tie between China and international investors. Its northbound turnover more than doubled to 345 billion yuan in the first half of 2026; southbound turnover hit a new high of $123 billion yuan. “It’s a closed loop, so capital cannot fly out of the system,” Li said.
Li, a director of Digital Asset Clearing Center, which aims to develop a financial settlement and clearing infrastructure that can integrate digital and tokenized assets into mainstream capital markets, argued that areas like Hong Kong, Singapore, and Shanghai have pockets of innovation in financial AI. Li said the region’s token economy “drives market infrastructure upgrades, attracts capital globally, and enjoys support from governments as a strategic force of growth.”
Fintech, Banking, and Innovation
Li pointed out that the region’s tokenized economy fosters “co-opetition” between the banking industry and fintech enterprises. Consumers across the region have largely turned to fintech-developed super apps like Alipay and WeChat Pay, while banks have doubled down on the regulated back end: cross-border settlement, know your customer, and other compliance rules.
Some of the same banks figuring out Asia’s patchwork of KYC and settlement rules are also among the world’s fastest-growing lenders. Banking data makes the same point in numbers. S&P Global Market Intelligence’s 2026 ranking of Asia-Pacific’s 50 largest lenders by assets found China’s big four — Industrial and Commercial Bank of China, Agricultural Bank of China, China Construction Bank, and Bank of China — grew assets about 16% year over year in US-dollar terms as of December 31, 2025. S&P also singled out Singapore’s three largest banks — DBS, Oversea-Chinese Banking Corp., and United Overseas Bank — for strong double-digit asset growth, driven by regional deposit inflows rather than capital raised abroad.
China’s financial system is bank-led and primarily state-directed, according to Standard & Poor’s. The country’s household savings, pensions, and corporate liquidity flow into banks rather than capital markets, giving lenders a large, stable funding base that the government then channels toward priority sectors. Beijing has supported that base with a 520 billion yuan capital injection into four state-owned banks in 2025, followed by plans announced in March 2026 to issue another 300 billion yuan in special bonds to recapitalize ICBC and Agricultural Bank of China.
“As the primary liquidity conduit for fiscal stimulus, state-owned banks increased their financial investments by 19% in 2025,” Iris Tan, a senior equity analyst at Morningstar, said in the S&P report. These financial investments were “fueled by a record 28% surge in government bond issuance,” according to Tan.

Vietnam as a Case Study
None of this means that Asia’s approximately 48 countries are growing equally. Sam Van, managing partner of SRO Partners and an advisor on Vietnamese capital markets, said the region is still layered by tier. Blue-chip regional companies can borrow cheaply from local banks at rates set by well-capitalized central banks — sometimes so cheaply, he said, that “it’s better to borrow money from the bank than actually issue a bond.” Midsize companies, those earning under $50 million in revenue, are a harder sell to credit officers weighing thin margins against career risk, which pushes some smaller businesses toward informal lenders. Van sees this gap as a reality in a still-maturing system rather than evidence that the system isn’t working.
Van, who recently co-authored a book that chronicles Vietnam’s economic rise, said the country illustrates how quickly a market can mature once the incentives align. Vietnam’s IMF-linked compliance upgrades — the product of what Van calls the government “consistently wanting to meet that standard” since joining the IMF in the 1990s — helped it earn an upgrade to FTSE Russell’s emerging-market status in September.
Critical Economic Views
Two economists watching from outside the deal room caution against overstating the region’s financial self-sufficiency. Bala Ramasamy, professor of economics at the China Europe International Business School in Shanghai, argued that “the driver in Asia, for Asia and by Asia is definitely China” — its outbound foreign direct investment to the Association of Southeast Asian Nations alone can match what comes from the EU or the US, and the reconfiguration of trade around geopolitical frictions is relocating supply chains in ways that are boosting growth across Southeast and South Asia. Japanese and Taiwanese capital, he noted, is increasingly heading toward the US to secure market access and stay aligned with Trump-era industrial policy, even as flows from Europe and the US slow elsewhere. “I don’t think Asia can do without it,” he said.
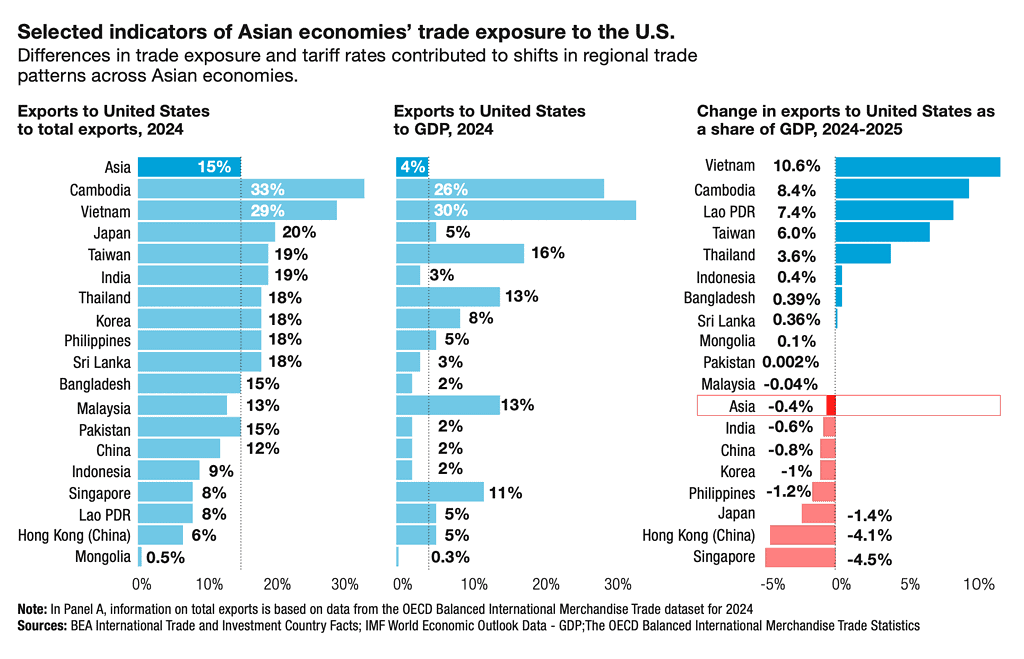
Prema-chandra Athukorala, emeritus professor of economics at the Australian National University, said Asia’s growth is substantial, but its export-driven economy still relies heavily on the rest of the world. Domestic savings rates across the region dwarf the emerging-market average of roughly 25% — Singapore’s is near 58%, China’s near 49.5%, India’s around 30% — and in most Asian economies, investment rates run below those savings rates, meaning the region is, on balance, a net exporter of capital rather than an importer of it. Intraregional FDI from China, Korea, Taiwan, and Singapore has grown substantially over the past two decades. However, Athukorala said that extra-regional FDI still accounts for the larger share of investment in Vietnam, Malaysia, Thailand, and Cambodia, where Western multinationals remain central to “China+1” supply-chain strategies, and even domestically financed activity depends heavily on global demand. “Over two-thirds of the regional exports are still destined to extra-regional markets,” he said.
Taken together, the practitioners and the professors describe a region that finances far more of its own growth than it used to, yet remains clearly reliant on the rest of the world.
Weld Royal is a contributing writer based in the U.S.
Comcast’s NBCUniversal reportedly slashes streaming tech jobs

nazdravie
- Comcast’s (CMCSA) NBCUniversal is said to be cutting jobs in its global streaming technology organization.
- The number of employees affected would depend on the outcome of consultations with employees, as per Reuters.
- Most of the cuts are at Sky, Comcast’s European
Japan’s unemployment rate rises to 2.5% in August, above expectations (EWJ:NYSEARCA)

- Japan’s unemployment rate edged up to 2.5% in August from 2.4% in July, moving above the 2.4% market consensus.
- The number of unemployed increased by 100,000 to 1.77M, while employment rose by 300,000 to 68.34M.
- Separately, the jobs-to-applicants ratio held at
Algoma expects 65% drop in Q3 steel shipments after turbine outage (ASTL:NASDAQ)

zhaojiankang/iStock via Getty Images
Algoma Steel (ASTL) fell 2.4% post-market Thursday after warning it expects to report a sharp decline in Q3 steel shipments due to the impact on production caused by a turbine outage.
The Canadian steel producer guided for Q3 steel shipments of ~145K
ChronoScale expands and adds new AI deals towards $1B revenue run rate
- ChronoScale (CHRN) announced on Thursday that it signed an expansion with an existing AI infrastructure customer and a separate agreement with a new customer.
- Combined with existing contracts, the deals now support a $1B annualized revenue run rate by Q3 2027.
How RBI Is Using AI to Strengthen Relationship Banking
AI is rapidly changing banking. What are the biggest challenges and opportunities for clients and financial institutions?
Elitza Kavrakova: The biggest question for organisations today is no longer whether they should adopt AI, but rather how to do so responsibly and effectively.

Financial institutions and corporates face multiple challenges. They need to strike the right balance between innovation, regulatory compliance, cybersecurity and data governance. At the same time, there is a genuine risk of becoming overly reliant on AI.
While AI can significantly improve efficiency and decision making, it should remain a co-pilot rather than an autopilot. Human judgment, accountability and critical thinking remain indispensable, especially in areas such as risk management and compliance.
Clients also continue to value human interaction. Technology can enhance the client experience, but trust-based relationships remain at the core of banking.
How are client expectations changing and what does this mean for relationship banking?
Elitza Kavrakova: Clients increasingly expect real-time access to information, faster execution, greater transparency and more proactive services from their banking partners.
They are also looking for actionable intelligence that helps them anticipate developments and make better decisions. This is where AI has the potential to fundamentally change the role of relationship managers. AI will elevate relationship managers from being information providers to becoming strategic advisors.
At RBI, we already use data-driven insights to support client engagement. AI can help relationship managers better interpret and understand client needs, identify opportunities earlier and provide more relevant solutions to navigate increasingly complex environments. This can include next-best-offer recommendations, data-driven pricing decisions, more effective meeting preparation and stronger post-sales engagement.
AI can also help identify relevant developments earlier, enabling relationship managers to engage with clients in a more informed and meaningful way.

How is technology transforming transaction banking and client connectivity?
Sabine Zucker: Customers are increasingly interested in a smooth and seamless interaction with their bank. This requires strong connectivity between banking platforms and clients’ treasury or bookkeeping systems. APIs play a major role here, as they provide the basis for straight-through connectivity and support increasingly tailored client experiences.
Looking ahead, the integration of AI into transaction banking could drive a new wave of innovation, including smarter liquidity management, predictive cash-flow forecasting and advanced fraud prevention capabilities.
This will help banks meet rapidly changing client expectations. For example, a few years ago, corporates rarely used instant payments. Today, companies expect instant information on their liquidity position at any point in time, enabling them to make faster and better-informed decisions.
What will define successful AI adoption in the years ahead?
Sabine Zucker: There is no doubt AI will change the way we work and support us a lot day-to-day.
The challenge will be to use all the benefits AI offers without losing sight of the importance of maintaining personal relationships and human judgment.
Elitza Kavrakova: Successful adoption requires robust governance frameworks that address transparency, accountability, data protection, model validation and human oversight. AI can support decision-making, but responsibility must always remain with people.
We are particularly excited about developments in generative AI, predictive analytics, ecosystem banking through APIs and the continued digitisation of trade finance and cross-border transactions. These technologies are helping institutions move from reactive to predictive service models.
Ultimately, the institutions which will be most successful are those able to combine innovation with trust, responsible leadership and a strong understanding of clients’ needs. The winning model will blend human judgment, trusted relationships and AI-powered intelligence.
Discover practical insights and solutions for streamlining payment processes and driving operational efficiency. Click on the logo below
SA Asks: Does AMD still have upside after its latest rally? (AMD:NASDAQ)
To ensure this doesn’t happen in the future, please enable Javascript and cookies in your browser.
Is this happening to you frequently? Please report it on our feedback forum.
If you have an ad-blocker enabled you may be blocked from proceeding. Please disable your ad-blocker and refresh.
Court overturns $22.7M patent infringement award against Gogo (GOGO:NASDAQ)

izusek/E+ via Getty Images
A U.S. district court in Delaware overturned a jury decision to award $22.7M to the plaintiffs in a case against Gogo Inc. (GOGO), ruling that SmartSky Networks failed to present sufficient evidence that it suffered legally recoverable damages and
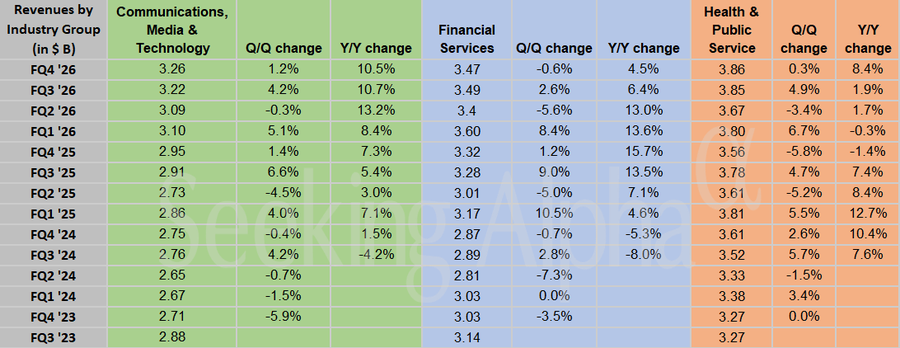
Accenture in charts: Americas revenue up 7%, CMT industry group gains 10%
Accenture in charts: Americas revenue up 7%, CMT industry group gains 10%
Source link
House Democrats seek investigation into taxpayer-funded Trump ads

gguy44/iStock via Getty Images
Two Democratic lawmakers are said to have called for independent probes into taxpayer-funded TV ads featuring President Donald Trump running ahead of the November midterm elections.
Representative Jamie Raskin, the top Democrat on the House Judiciary Committee, and Representative George Whitesides, asked the Government
Caribbean Central Banks Ditch CBDCs
As CBDCs struggle with low adoption, the Caribbean is pivoting to instant payment systems to boost trade and financial integration.
This article appears in the October issue of Global Finance Magazine.
The Caribbean was at the vanguard of adopting central bank digital currencies with the Bahamas’ SandDollar, one of the world’s earliest retail pilots in 2020. A year later, the Eastern Caribbean Central Bank followed suit with its DCash.
With take-up rates low, DCash has since been discontinued as central banks pivot to instant payment systems. The aim is to provide a resilient and flexible system in an area prone to natural disasters and reliant on tourism and remittances as economic drivers.
“These central bank digital currencies had quite poor uptakes. They never really took off,” said Caribbean economist Dalano DaSouza. “Barbados went the route of doing a fast payment system [BiMPay launched on June 12] and the ECCB is embarking on the same journey because they believe that’s where the transformation lies in terms of digital payments.”
The fact that DCash had an outage in 2022 that stopped new transactions for two months did not help consumer confidence and the project was discontinued in February. Jamaica’s Jam-Dex gave the first 100,000 users who signed up a J$2,500 bonus ($15.69), which accounted for about 0.09% of currency in circulation. The 310,443 registered users represent approximately 11% of Jamaica’s population.
“The lessons learned are that full integration with the banking system is vital. A fast payment system will still be sending and accepting digital payments, but it will be done from the client’s bank account,” DaSouza said.
WiPay, Lynk and Trinidad and Tobago adopting India’s UIP interface shows a region keen on integrating and expanding its trade opportunities. This includes the possibility of being incorporated into the African Continental Free Trade Area. This would be accomplished via the Caribbean Community’s CAPSS payment system, which is itself based on Africa’s Pan African Payment System platform.

Economist
A pilot scheme to harness the Caribbean and African payment systems is underway, involving Barbados, ECCB and the Trinidad and Tobago central banks. The African Export-Import Bank (Afreximbank has been at the forefront of moves to bring the two regions together. The idea that Caribbean countries can join AfCFTA opens a market of 54 countries with 1.3 to 1.4 billion consumers with a combined GDP of approximately $3.4 trillion.
“Potentially, by using the system to make an instant payment from the Caribbean to a vendor in Africa, you would be bypassing correspondent banks, and you would be bypassing the U.S. and their banks,” DaSouza said.
This removes a barrier to African integration, which is the current issue in the history of payments and having to use correspondent banks in the U.S., England, or Europe.
Digital trade and paperless trade systems reached 73% implementation in 2025, according to the United Nations Economic Commission for Latin America and the Caribbean.
With the Caribbean piloting the next stage of instant payments, the hope is that this can lead to greater business opportunities, not just regionally but globally. CBDCs arguably started the digitalization of the Caribbean financial system, but now it seems time for instant payments.
“Digital payments will be critical to opening new markets and streamlining old ones,” DaSouza said.
Nic Wirtz is a contributing writer based in Guatemala.
Southport Acquisition II prices $200M initial public offering at $10

Andrii Yalanskyi
Southport Acquisition Corp. II (PORT.U) announced the pricing of its initial public offering of 20M units at $10.00 per unit, raising $200M in gross proceeds.
The blank check company’s units are scheduled to begin trading on the New York Stock
Micron expects fiscal Q1 revenue of $61.5B ±$1.5B as it raises fiscal 2027 CapEx plans amid tighter 2027-2028 supply-demand (NASDAQ:MU)
Earnings Call Insights: Micron Technology (MU) Q4 fiscal 2026
Management View
- “Micron delivered an exceptional fiscal Q4 with significant records in revenue, gross margin and EPS, each exceeding the high end of our guidance.” (CEO & Chairman Sanjay Mehrotra)
- “We
Seeking Alpha’s Disclaimer: This article was automatically generated by an AI tool based on content available on the Seeking Alpha website, and has not been curated or reviewed by humans. Due to inherent limitations in using AI-based tools, the accuracy, completeness, or timeliness of such articles cannot be guaranteed. This article is intended for informational purposes only. Seeking Alpha does not take account of your objectives or your financial situation and does not offer any personalized investment advice. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank.
Fed’s Waller Eyes Agentic AI Commerce
Agentic AI has a toehold in B2C transactions, but has a way to go to capture B2B transactions, Waller said at the Sibos conference.
Artificial intelligence and autonomous AI agents will fuel the next evolutionary leap in global and cross-border payments, Federal Reserve Board Gov. Christopher Waller said during a speech at Sibos 2026 in Miami.
The payment industry’s early adoption of machine learning and large language models has helped combat payment fraud and quicken reconciliation and similar tasks, said Waller.
“Now it is helping build the foundation infrastructure for AI agents to operate more broadly in the economy,” he added. “These agents can plan and execute multistep processes using LLMs, enabling those agents to transact autonomously.”
Waller separated agentic commerce into two models: agentic-assisted and agentic-delegated. In the agentic-assisted model, the agent is primarily for product search and discovery, while the buyer remains in control. In the agentic-delegated model, “a buyer grants authority to an AI agent to shop and make payments on their behalf. The buyer may specify some constraints and set up guardrails, but the agent operates autonomously.”
Because agentic-delegated commerce could increase the risk of unintended purchases, Waller suggested deploying more extensive trust mechanisms and guardrails.
Agentic B2B Payments
Although agentic commerce has gained traction in consumer-to-business transactions with personal AI assistants, Waller said that business-to-business purchases would be fertile ground for agentic-delegated commerce.
“The purchases are often recurring and abide by a set of rules, such as approved suppliers and budget limits, which create natural guidelines for agents,” he said. “Agents could also potentially negotiate terms with suppliers and develop payment strategies to optimize working capital.”
However, the industry would need to develop and deploy robust controls and monitoring capabilities since B2B transactions typically carry a higher value than their consumer counterparts.
Also, unlike consumer-to-business transactions, AI agents executing B2B transactions will need to support a broad range of payment rails, including the Automated Clearing House, wire transfers, instant payments, and credit cards.
The biggest barrier to agentic commerce adoption is building trust mechanisms between buyers and sellers, which changes the payment authentication paradigm, said Waller. “The question shifts from proving that a buyer is an authorized payer to proving that an agent has the authority to pay on the buyer’s behalf. Capturing this will require new authentication approaches.”
He also noted two key questions about the future of agentic commerce: whether it will migrate toward platform-specific or interoperable standards. The latter would work across ecommerce systems, agent interfaces, and payment methods. “In this sense, they could help to level the playing field for smaller merchants and payment providers seeking to operate in this space.”
The payment industry still needs to take significant steps before it can bring agentic commerce to fruition, including developing standards for how agents can “carry identity, consent, and payment credentials across the full ecommerce stack,” as well as striking the proper balance between convenience and friction regarding agent authorization, Waller said.
These steps will require the payments industry to balance innovation with the safety, integrity, and stability that underpin trust in payments, he concluded.
Legislation on permanently banning Chinese vehicles in the U.S. stalls in the Senate (F:NYSE)

Republican Senator Rand Paul is standing in the way of the bipartisan Connected Vehicle Security Act of 2026, sponsored by Senators Bernie Moreno of Ohio and Elissa Slotkin of Michigan, from passing through the Senate. The legislation aims to prohibit the import, manufacture, and sale

Gulf Investors Look to Libya and Algeria
Energy market disruptions and regional uncertainty are pushing GCC countries to boost North Africa investments.
This article appears in the October issue of Global Finance Magazine.
In July, Qatar’s UCC Holding signed a $1 billion deal with Libya’s National Oil Corp. and the Libyan Investment Authority to increase output at the Ghadames Basin from 33,000 to 80,000 barrels a day.
A few weeks earlier, Oman’s OQEP signed a similar contract to explore investment opportunities in Libya, “so our production will not rely only on exports from the Strait [of Hormuz],” OQEP Board Chairman Ashraf Al Mamari told Arabian Gulf Business Insight in July. That same month, Libyan Prime Minister Abdul Hamid Dbeibah visited the United Arab Emirates and Qatar to encourage new partnerships.
Disruptions in energy markets at home are pushing Gulf countries to scale overseas investments and increase involvement in riskier destinations. With its large oil reserves, Libya is an attractive opportunity; but for years, it has been a headache for foreign investors. After Muammar Gaddafi’s fall in 2011, the country split between rival governments and became a playground for militias. Yet, despite instability, Gulf states—led by the UAE, and to a lesser extent Qatar—developed relationships with both capitals: Tripoli and Benghazi.
“Gulf states have been navigating this landscape for some time,” said Mohamed Dorda, head of business intelligence at Libya Desk, a consulting firm that advises businesses looking to enter Libya. “It’s really a matter of, first, having a foot in the door; and then, knowing where to put your feet. In Libya, they’ve been investing in the necessary political capital for quite some time now.”
Signs of Improvement
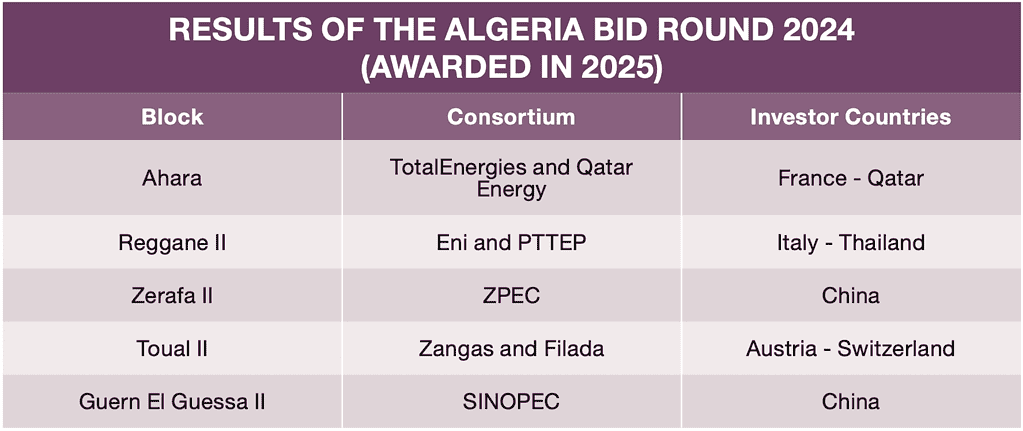
Today, the situation is showing signs of improvement. Both sides have taken steps toward greater stability, including the reunification of the central bank in 2023 and the approval of a common state budget in April of this year. Libyan authorities are now looking to reopen the energy sector to foreign investors. In February, the country resumed licensing for the first time since 2007, attracting oil majors like Italy’s Eni SpA, France’s TotalEnergies SE, Spain’s Repsol SA, and U.S.-based Chevron Corp.
The renewed interest extends beyond Libya. In recent months, the U.S. administration has stepped up engagement with North Africa, with Middle East adviser Massad Boulos visiting several countries. European nations, including Turkey, as well as China, are also moving to secure market shares.

“North Africa is becoming increasingly important in global trade because of its proximity to Europe and its capacity to help fill supply gaps created by the wars in Ukraine and the Middle East,” Dorda said. “People see that Libya and Algeria are among the strongest candidates to help meet global energy needs, and that creates opportunities.”
Algeria has drawn around $9 billion in Gulf-backed projects over the past 18 months, led by Saudi Arabia’s Midad Energy’s $5.4 billion oil and gas deal in October 2025 and by Qatar’s $3.5 billion Baladna dairy venture, now in its second phase.
Algerian state-owned hydrocarbon company Sonatrach plans to increase production and drill 1,450 wells by 2030, but it needs foreign know-how and capital to modernize infrastructure. In April, Algiers opened a new licensing round for seven oil and gas blocks. Bids are underway, and contracts are expected to be signed in January.
Chloe Domat is a contributing writer based in France.