Earnings Call Insights: Advanced Energy Industries (AEIS) Q3 2026
Management View
CEO Stephen Kelley said the company “delivered a record third quarter with revenue and earnings above the high end of guidance,” adding that “total revenue grew over $120 million sequentially” and that “earnings per share
Seeking Alpha’s Disclaimer:This article was automatically generated by an AI tool based on content available on the Seeking Alpha website, and has not been curated or reviewed by humans. Due to inherent limitations in using AI-based tools, the accuracy, completeness, or timeliness of such articles cannot be guaranteed. This article is intended for informational purposes only. Seeking Alpha does not take account of your objectives or your financial situation and does not offer any personalized investment advice. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank.
AngloGold Ashanti (AU) climbed 3.3% in Monday’s trading as TD Cowen initiated coverage with a Buy rating and $123 target price, viewing the miner as “a high-quality senior producer, offering a combination of organic production growth and strong free cash flow generation, with a good
Short interest among U.S. micro- and small-cap REITs was concentrated in a handful of stocks, led by healthcare and office property owners, along with mortgage REITs.
Medical Properties Trust (MPT) and JBG SMITH Properties (JBGS) were the
Coherent (COHR) and Applied Optoelectronics (AAOI) were upgraded by Northland Capital Markets on Monday after Marvell Technology (MRVL) announced its deal for Lumentum (LITE).
“While the upside in the AI Optical group from reports that MRVL was fleeting, it served to
DBS Bank’s Group Head of Institutional Banking reflects on the bank’s historic World’s Best Corporate Bank win, the shift toward more intentional supply chains, and how agentic AI is reshaping the way DBS serves corporate clients.
Han Kwee Juan, Group Head of Institutional Banking, DBS Bank, speaks with Global Finance after the bank was named World’s Best Corporate Bank 2026.
DBS Bank is the first bank from Southeast Asia to be named World’s Best Corporate Bank by Global Finance. Han Kwee Juan, Group Head of Institutional Banking, calls the award “a defining moment” for the bank. He sees it as recognition of DBS’s shift from a Singapore-centric corporate and institutional bank into a global partner that clients trust with their banking in Asia.
Han says many describe today’s supply chains as disrupted, but DBS sees something different among its clients: intentional supply chains. Companies are adopting local-for-local and region-for-region strategies to deal with trade challenges and tariffs. DBS responds by giving clients the flexibility to move across trade corridors while managing risk and liquidity. It also draws on its knowledge of Asian markets to help clients choose the right capital structure for each investment.
Technology is changing DBS in three ways, Han explains. First, a modernised tech stack enables instant payments and settlement. Second, agentic AI is transforming how the bank works internally. As an example, DBS has rolled out an agentic credit memo solution to all its relationship managers. With memos repared for them, it eaves RMs free to apply their own judgment and client knowledge. Third, DBS is preparing for an agentic world, ready to interact with clients’ own AI agents when they are ready.
Looking ahead, Han notes that liquidity is plentiful but under pressure. Hyperscalers and developed-market governments are drawing heavily on it to fund the AI and data infrastructure build-out, which makes it harder for other borrowers to access. DBS sees opportunity in new ways of raising funds for clients. That includes partnering with financial sponsors in private credit and private equity, and combining loans, syndication and capital markets with private players and insurers.
Glencore (GLCNF) (GLNCY) has proposed to change CEO Gary Nagle’s pay package to allow him to cash out long-term share awards more quickly if the company is taken over, the Financial Times reported Monday.
Ennis (EBF) has acquired Telemark Diversified Graphics, a thermal paper products manufacturer located in Sturgis, Michigan.
The acquisition expands Ennis’ thermal paper capabilities and broadens its product offerings for distributors serving financial institutions, retailers, and other businesses.
Stock futures rebounded early Monday as investors looked past October’s tech decline and turned toward pivotal corporate earnings and political catalysts.
Here are some of Monday’s biggest stock movers:
Biggest stock gainers
Inovio Pharmaceuticals (INO) +224%– Shares surged after the
This time, the tech revolution is different as AI threatens to automate its own labor.
The artificial intelligence revolution is hitting the global economy much as Ernest Hemingway described bankruptcy: gradually, then suddenly. The rapid acceleration has left central bankers, CEOs, and international financial institutions concerned.
AI technology is not new, said Jack Clark, cofounder and head of policy at Anthropic, during a panel discussion at the annual International Monetary Fund and World Bank meeting in Bangkok. “By some measures, it’s about 60 or 70 years old. The world is full of computer vision systems that do very useful work today and help us make robots smarter using small-scale language models.”
Nonetheless, the accelerating pace of technological change has affected global equity, credit, and sovereign debt markets, prompting people to ask what the ultimate benefit to society is.
“Productivity is the fundamental source of rising living standards for all our citizens,” said panelist Tiff Macklem, Governor of the Bank of Canada. “We want to see adoption. We want to see diffusion, but we need to manage the risks, or we won’t reap the benefit.”
Where Are the Jobs?
Every wave of new technology has created more jobs than it has destroyed, Macklem said. “I’m not saying there hasn’t been creative destruction, a simple economic term for something getting destroyed. As other things get created, resources have to transfer from one place to another.”
Just as the 18th-century spinning jenny displaced many textile workers, AI will replace jobs involving repetitive tasks and should create demand for new positions.
Unlike previous technologies, AI is the only one that could automate away the new jobs it creates, he said. “So far, the data show it happening to certain professions in most countries, but you cannot see it at an aggregate level.”
A recent labor-market study by the IMF found that demand for higher-paying skilled jobs that didn’t exist before is rising, with about 10% of jobs falling into this category. In turn, these new jobs typically increase spending on services, which in turn generates more service-based jobs.
“The problem is that service jobs do not pay a lot,” said fellow panelist Kristalina Georgieva, IMF’s Managing Director. “You get young people who normally would have gone into professional routine jobs serving coffee at Starbucks.”]
It’s easy to see which jobs are being destroyed, said Macklem. “It’s not easy to identify which new jobs will be created.”
Preparing the Post-AI Workforce
Policymakers will need to be proactive in determining what these new jobs will be, where they will be, and what they will require, since only a handful of economies benefit most from the AI value chain, said Georgieva. “In Africa, 50% of the people do not have Internet access, and there is a tremendous problem with just access to electricity.”
Singapore has already begun providing subsidized skills training, said panelist Ayesha Kahnna, co-founder and CEO of Addo AI. “They’re giving hundreds of millions of dollars to businesses to transform so they can absorb these newly skilled workers.”
Inside Anthropic, the company has hired experienced workers because it needs managers, Clark added. “You want to hire people with experience in management to manage these virtual workers.”
Rob Daly covers the economy and fintech. He can be reached at rdaly@gfmag.com
Apollo Global Management (APO) has launched European Credit Company (ECC), a platform focused on European performing credit, including corporate and asset-backed lending.
ECC begins operations with more than €10B in lending capacity, positioning itself as a long-term financing partner for businesses across
The White House’s acquisition of equity in U.S. companies raises questions about conflicts of interest.
This article appears in the November issue of Global Finance Magazine.
The Trump administration has joined a growing number of governments that have embraced industrial policy, often at the expense of strict free-market doctrine.
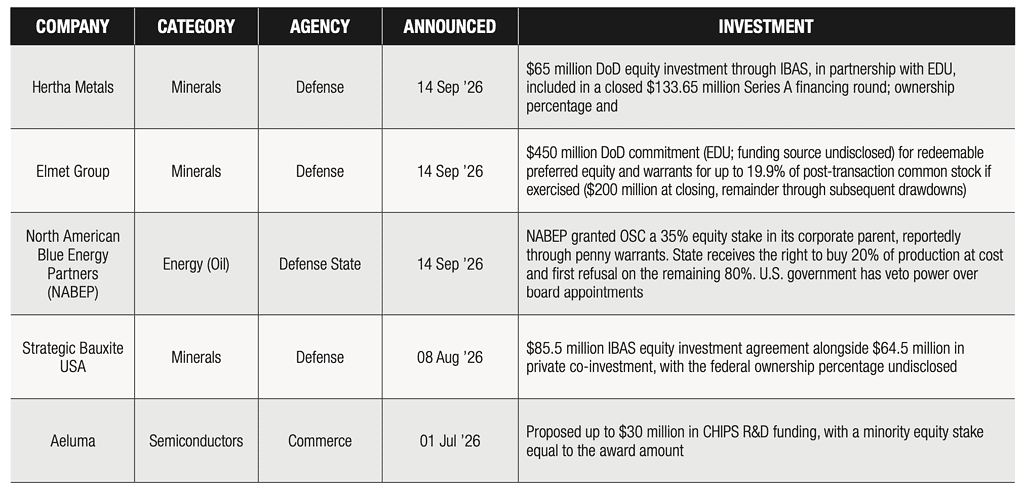
In an abrupt break from past practice, the federal government under President Donald Trump has taken equity or equity-like stakes in 34 private-sector companies in the U.S., as of Oct. 1, spanning industries from critical minerals and semiconductors to quantum computing. Its August 2025 announcement that it would take a 10% stake in Intel Corp. marks its biggest such step and makes the U.S. government the chipmaker’s largest shareholder.
The goal of industrial policy is to put a nation’s economy on a more globally competitive footing by providing government support, increasingly in the form of equity as well as loans and tax credits, to companies deemed strategically important for the economy or for national security. Details vary widely from government to government, but while others have taken equity stakes in private-sector companies, the U.S. approach raises serious concerns.
Critics warn that industrial policy can lead to rent-seeking by governments and corruption at the level of individual government officials. The Trump administration’s practices raise just this issue, according to critics on both the left and right.
In a recent blog post, Cullen Hendrix, a senior fellow at the Peterson Institute for International Economics, a Washington, D.C.-based center-right think tank, wrote that when state control is exercised in an ad hoc fashion through privately negotiated channels and without any pretense of independent oversight, as the Trump administration has done, “state ownership and control typically redistribute benefits to politically connected clients and away from the public. This potentially corrupting phenomenon is the prevailing concern with the Trump administration’s approach.”
“This is not what anyone could reasonably want from industrial policy.”
Dean Baker, Center for Economic Policy and Research
Dean Baker, co-founder of the Washington, D.C.-based progressive think tank, the Center for Economic Policy and Research, went further in an interview with Global Finance: “It would be overly generous to call this industrial policy. It is simply Trump arbitrarily exercising power. We don’t know whether he or his family have gotten kickbacks from the companies. This is not what anyone could reasonably want from industrial policy.”
The White House offered this statement in response:
“The only special interest guiding the Trump administration’s decision-making is the best interest of the American people. Securing and reshoring America’s critical supply chains has been a top priority for President Trump, and the Trump administration continues to take historic action to safeguard America’s national and economic security.”
Several members of Congress contacted for this story did not immediately respond to requests for comment.
Maximizing Discretion
Industrial policy is by no means synonymous with corruption and self-dealing. “There are many examples out there in the world of having more socialist orientation in the economy while still staying loyal and faithful most of the time to price signals and supply and demand,” Hendrix said, noting that many countries take a technocratic approach to managing their holdings. But the Trump administration is following a very different path, “maximizing the independent discretion of the executive.”
The U.S. Commerce Department claims that the government’s stakes in private-sector businesses enhance the return on investment for taxpayers. But “even a profitable portfolio would not resolve the underlying institutional problem,” Tad DeHaven, a policy analyst at the Cato Institute, a Washington, D.C.-based libertarian think tank, said in a recent article on its website. “Even a profitable portfolio would not resolve the underlying institutional problem,” which consists of manifold conflicts of interest.
“The federal government is now acting as regulator, customer, financier, and shareholder,” he wrote. “Decisions involving contracts, trade restrictions, permits, and subsidies can affect the value of its holdings. Competitors have reason to question whether the playing field is level. And if a portfolio company falters, Washington will have an added incentive to protect its investment with more taxpayer support.”
(Chart below: Five of the Trump administration’s most recent equity stakes in U.S. companies as of Oct. 1, bringing the total to 34 .)
(Source: Cato Institute)
Might it mitigate these risks to lodge these holdings in a sovereign wealth fund? Wealth funds are common around the world and in the cases of Norway and Saudi Arabia, help to diversify their economies away from dependence on oil revenue. The White House last year announced that it would create such a fund, though none has materialized to date.
Wealth funds aren’t really designed for industrial policy, Hendrix said, but to maximize returns on surplus revenues in anticipation of a rainy day. Adnan Mazarei, a nonresident senior fellow at the Petersen Institute, added that the standards for governance of wealth funds themselves need improvement, as the so-called Santiago Principles that apply to them and were finalized in 2008 are woefully out of date.
Even the most stringently negotiated and overseen government investments can still be subject to political influence, even when they are passively managed. But, as Hendrix and other observers noted, there are guardrails that can and should be imposed to limit it. If the state is going to start acquiring assets, Hendrix said, “then you build a bureaucracy within the state to manage those assets.”
So far as the Trump administration’s equity interests are concerned, he noted in his blog post, “the terms under which these stakes have been acquired and managed by the administration—ad hoc, privately negotiated, and with significant executive discretion—are more troubling than the equity stakes themselves.”
Government-held stakes in private-sector companies are unnecessary for effective industrial policy in the first place, Baker said, noting that subsidies such as research grants, tax credits, and patent and copyright protection are more than sufficient. These have helped produce, at least until recently, the world’s leading pharmaceutical industry and highly competitive computer and software companies, he added.
“The best way is to have laws that make industrial policy formulaic, so that it does not depend on executive decisions,” Baker said. “Our patent and copyright monopolies are probably the best examples of this sort of policy.”
Oversight, Japanese Style
Japan offers a contrasting approach. Its industrial policy was initially administered by the Ministry of International Trade and Industry, which was reorganized in 2001 as the Ministry of Economy, Trade and Industry. Both operated under strict conflict-of-interest oversight.
According to the Organization for Economic Cooperation and Development, responsibility in Japan for addressing anti-corruption that might arise from industrial policy is shared among the Ministry of Justice, the Ministry of Foreign Affairs, and the National Police Agency, while the National Public Service Ethics Board monitors potential conflict-of-interest situations for civil servants and the Ministry of Internal Affairs supervises political finance.
“The central government has adopted strategic objectives for mitigating public integrity risks in public procurement,” the OECD noted in a 2024 analysis comparing Japan’s industrial policy with other governments.
According to an index of government control of private industry maintained by the Varieties of Democracy Institute at the University of Gothenburg in Stockholm, the U.S. dropped from second place in the world for freedom from such control, a position it had held since 2007, to 16th this year, while Japan has maintained its long-standing position in first place, notwithstanding its commitment to industrial policy.
The CHIPS and Inflation Reduction Acts passed by Congress under the Biden administration represent a form of industrial policy, but, Hendrix observed, the support they provided for the semiconductor and green energy industries came primarily in the form of tax credits and other subsidies. Equity stakes were not taken under CHIPS, although the Trump administration used money appropriated by CHIPS for the Intel acquisition.
Weaponizing Uncertainty
There’s some question whether Washington even has the authority to purchase equity in private-sector companies, as Peter Harrell, an attorney specializing in international economic law and a member of the Council on Foreign Relations, wrote in a recent article at Lawfare. Congress may have to step in to make sure that the “profound policy questions” raised by such stakes are addressed, he added.
“If Congress wants the government to expand its role in the private sector,” Harrell wrote, “it could also adopt more general legislation — a modern-day Government Corporation Control Act — stipulating how and under what circumstances the government could take equity and setting out how such equity should be governed.”
In Hendrix’s view, however, the White House is likely to oppose such legislation: “The Trump administration does not like an institutional approach. It values having strategic autonomy and being able to weaponize uncertainty.”
Baker said, by contrast, that a new bureaucracy is unnecessary. “Congress and the courts have all the tools needed to rein in the Trumpian abuses,” he said. “A stake in specific companies will provide an incentive to throw good money after bad. We should use regulatory policy to promote desirable investment and discourage harmful practices. An ownership stake is not needed for these goals.”
The weaponization of uncertainty was evident in the case of Intel, where the administration pushed for the removal of CEO Lip-Bu Tan because of his ties to China before relenting in exchange for its equity stake. Unless the White House drops this approach, the criticisms of conflict of interest in U.S. industrial policy will continue to mount.
Ronald Fink is a contributing writer based in the U.S.
The S&P Global Australia Manufacturing PMI was revised slightly lower to 49.6 in October 2026 from the preliminary estimate of 49.7, remaining unchanged from September’s 21-month low.
The reading marked a second consecutive month of sector contraction, driven by the sharpest drop
Chinese electric vehicle maker Li Auto (LI) delivered 29,025 vehicles in October 2026, representing a 43.6% Y/Y decline from 51,443 units in October 2025 and an 8.8% M/M drop from 31,817 units in September 2026.
Quant rankings for the upcoming earnings calendar show strength concentrated across information technology, energy, and health care, while weakness is more pronounced in financials and real estate. A total of 1479 companies are scheduled to report in the coming week.
Oil prices declined ahead of Tuesday’s U.S. midterm elections as investors weighed renewed attacks on commercial vessels near the Strait of Hormuz against prospects for a diplomatic resolution to the conflict with Iran.
Canadian Prime Minister Mark Carney said he and President Donald Trump agreed to pursue a new trade agreement in the coming weeks, signaling renewed negotiations after talks broke down in August.
Carney disclosed the conversation Sunday, two days before U.S. midterm elections