secure

Can Britain Secure a Role in the EU’s Made in Europe Plan?

Britain is seeking a closer economic relationship with the European Union by asking to participate in the bloc’s “Made in Europe” industrial strategy, as Prime Minister Andy Burnham argues that the UK and EU face many of the same economic and industrial challenges.

Travelling to New York for his first United Nations General Assembly as prime minister, Burnham said Britain would seek to become a “trusted partner” in the initiative, which is intended to strengthen European production and reduce dependence on Chinese components.

“Europe’s argument is not with us,” Burnham told reporters on Monday. He said Britain and the EU faced similar pressures, particularly in industries such as steel, and argued that the UK should not face unintended consequences from a policy aimed at addressing dependence on China.

The British government has warned that excluding UK companies could disrupt established supply chains and create additional trade barriers between Britain and EU member states.

Stay ahead of the geopolitical week.

MD Briefing delivers expert analysis across five global fronts — the Indo-Pacific, energy, geoeconomics, European security, and the Middle East — every Monday morning. Free.

Why Britain wants access

The EU’s Made in Europe initiative is part of a broader effort to increase domestic industrial capacity and reduce reliance on overseas supply chains, particularly those involving China.

For Britain, exclusion could have consequences for sectors that remain closely integrated with European markets. The automotive industry, for example, relies on supply chains that cross the English Channel in both directions. Industry representatives have warned that excluding British manufacturers from European incentives and procurement opportunities could affect the competitiveness of both British and European companies.

British officials therefore want the EU to treat the UK as a partner in the initiative rather than as an external supplier.

Burnham has argued that British participation would reflect the practical connections that remain between the UK and European economies despite Brexit.

A wider attempt to rebuild UK EU ties

The dispute over Made in Europe is taking place as Burnham’s government seeks to deepen Britain’s relationship with the EU.

The UK government has already been pursuing closer cooperation with European countries in areas including defence, technology and manufacturing. Finance Minister John Healey recently urged EU counterparts not to exclude Britain from the bloc’s industrial strategy.

The government has also been seeking greater cooperation on European security. However, negotiations over British participation in the EU’s SAFE defence fund broke down, creating another obstacle to the government’s efforts to expand cooperation with Brussels.

Burnham has said he wants to move further and faster in rebuilding ties with the EU. His government has also been working toward a UK EU summit that was delayed following the change in prime minister.

The challenge inside Europe

Britain’s request for access is not simply a matter of negotiating with EU institutions. Member states also have different interests in how far the bloc’s industrial policies should extend to non member countries.

The proposed policy is intended to direct European economic activity toward European production and strengthen industrial resilience. Extending its benefits to British companies could therefore raise questions about what obligations Britain would have in return and how EU based businesses would compete with UK firms.

There are also broader questions about the meaning of the UK’s post Brexit relationship with the bloc. The British government is seeking closer economic and security cooperation without reversing the country’s decision to leave the EU.

That creates a difficult balance. London wants greater access to European programmes and markets, while Brussels must determine the conditions under which a non member state can participate in policies designed partly to strengthen the EU’s own industrial base.

What comes next?

Burnham’s immediate objective is to secure British participation in the Made in Europe framework while avoiding new barriers for industries whose supply chains remain closely connected to the continent.

The issue could become part of wider negotiations over the future of UK EU relations. Burnham has said his focus is on a renewed summit with European leaders, which he hopes can take place before the end of the year.

The outcome will indicate how far Britain and the EU can move toward closer economic cooperation without reopening the fundamental question of Britain’s membership.

For London, the argument is that Britain and Europe face shared challenges from global supply chain disruption and dependence on foreign production. For the EU, the question is how to strengthen European industrial capacity while determining the appropriate role for a neighbouring non member economy.

The debate over Made in Europe therefore reflects a broader post Brexit question: how closely can Britain integrate with European economic and security structures while remaining outside the bloc?

With information from Reuters.
Source link

Trump Allies Secure Venezuela Resource Concessions as ExxonMobil Eyes Return

Venezuela has opened its energy and mining sectors to US interests. (PDVSA)

Lisbon, Portugal, September 17, 2026 (venezuelanalysis.com) – Continental Resources, a firm owned by billionaire and Trump donor Harold Hamm, struck a deal on Wednesday to exploit one of Venezuela’s largest oilfields.

Under the agreement with Venezuelan state oil company PDVSA, Continental will receive a long-term concession with “100 percent working interest” for the 500 square-kilometer Ayacucho 2 block in Venezuela’s Orinoco Oil Belt. The block contains an estimated 30 billion barrels of extra-heavy crude.

“Continental was built to recognize great resource opportunities and have the conviction to pursue them,” Hamm told Fox News, vowing that the deal would take his company to an “entirely new level.”

For her part, Venezuelan Acting President Delcy Rodríguez claimed that the agreement would “strengthen [Venezuelan] oil production” and “create opportunities for economic growth.”

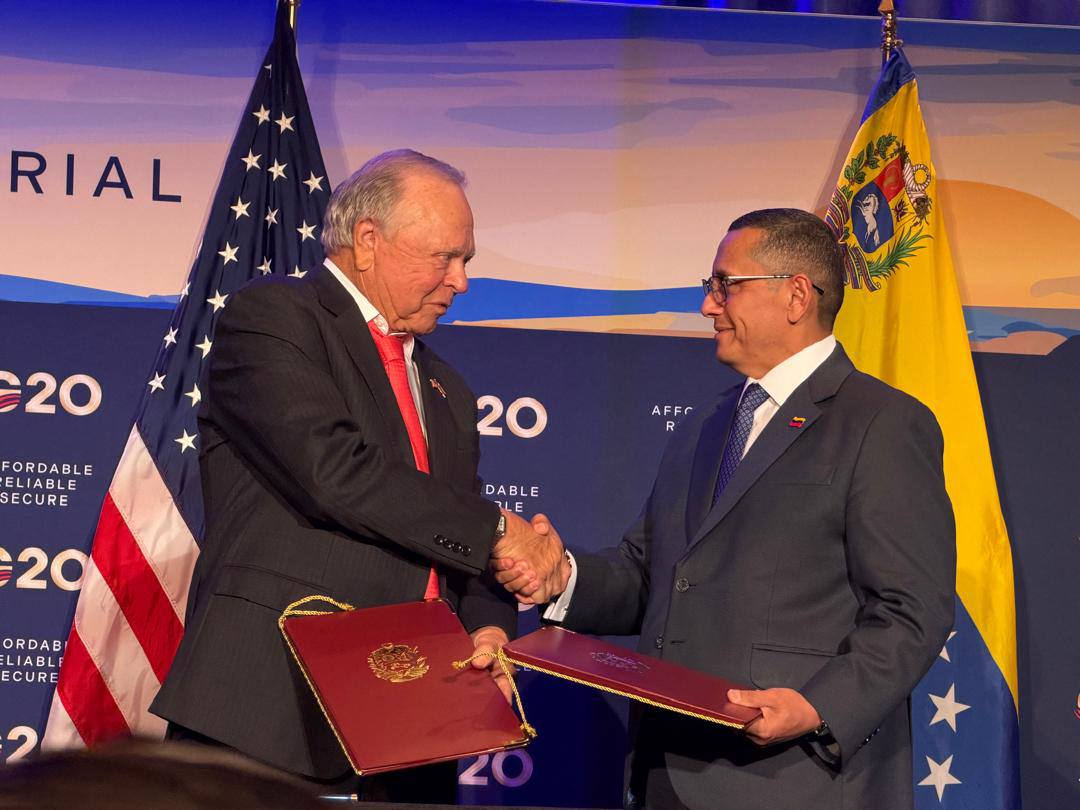
Hamm and PDVSA Vice President Jovanny Martinez signed the contract in Houston on the sidelines of the G20 energy summit. Martínez and Oil Minister Paula Henao attended the conference to pitch investment opportunities in Venezuela’s oil and gas sector.

PDVSA had previously assigned the Ayacucho 2 block to Chinese private firm Anhui Guangda in 2025. However, no information on investments or output were publicly disclosed, while Venezuelan authorities have not justified rescinding the contract with Anhui.

US government-controlled corporation NABEP, which recently received long-term concessions to 17 major Venezuelan oilfields containing 65 billion barrels in reserves, will also take over projects formerly run by Chinese enterprises, including state-owned CNPC. Beijing has called for its investments and interests in Venezuela to be respected.

Hamm was one of the corporate executives present at the White House on January 9, when Trump announced that Washington would control Venezuela’s oil industry and called on Western majors to invest. Since the January 3 US attacks and kidnapping of President Nicolás Maduro, the White House has managed the South American country’s crude export revenues.

The White House has also backed Venezuelan authorities’ pro-business overhaul of the energy sector while issuing sanctions exemptions to select US-aligned corporations. Chevron, Shell, and Eni are among the companies that have signed new contracts or renegotiated existing ones in recent months.

According to Bloomberg, ExxonMobil is in advanced talks to return to the Caribbean country after a litigious past. The energy giant is negotiating rights to four major oilfields in the Orinoco Oil Belt, two of which it previously owned before they were nationalized by former President Hugo Chávez.

In the 2000s, the Texas-based corporation refused to comply with reforms implemented to assert state sovereignty over the oil industry. ExxonMobil refused compensation offers and pursued international arbitration after its assets were nationalized. The company received an arbitration award significantly below its demands. 

ExxonMobil was additionally denounced repeatedly by Caracas after it spearheaded offshore drilling projects in the territorial waters of the disputed Essequibo Strip.

On Wednesday, Venezuelan authorities likewise inked a 20-year agreement with Florida-based Denarius Holding Group, controlled by Turkish energy group Çan2 Termik. Denarius is taking over the Petrokariña project in Anzoátegui state, which contains 10 oilfields producing a variety of crude types.

Heeney Capital receives gold mine concession

In parallel to its oil opening, Venezuelan authorities have also fast-tracked reforms opening the country’s mining sector to multinational corporations.

On Wednesday, New York-based Heeney Capital and commodities trader Mercuria Energy received a 30-year concession to operate the Chocó 10 mine in Bolívar State. The project holds considerable gold deposits and was run by Rusoro Mining in the 2000s before being nationalized by the Chávez government.

Heeney and Mercuria pledged US $1 billion in initial investment in the Chocó project. The two firms had struck a previous agreement with Caracas to purchase and trade Venezuelan minerals and other commodities.

One of Heeney’s co-founders, Sean Pi, signed the deal at the presidential palace in May and praised Trump’s “leadership” in defending US access to mining resources abroad. Pi has endorsed legislative initiatives deregulating and streamlining mining projects to bolster the US supply of critical minerals.

Under the trading agreement, Heeney and Mercuria are reportedly preparing to ship 15,000 metric tons of Venezuelan aluminum to the US. The corporate partners are likewise seeking to take over VENALUM, Venezuela’s biggest aluminum smelter. Glencore, an Anglo-Swiss mining and trading multinational, is also interested in VENALUM, according to reports.

Venezuelan authorities have not commented on the negotiations for the aluminum smelter. In April, Rodríguez appointed a commission to evaluate privatization of “non-strategic” state assets.

The Trump administration has identified securing access to Venezuelan mineral riches as a key national interest and is reportedly preparing an executive order to boost US corporate participation in Venezuelan mining projects.

Edited by Lucas Koerner in Philadelphia, USA.

Source link