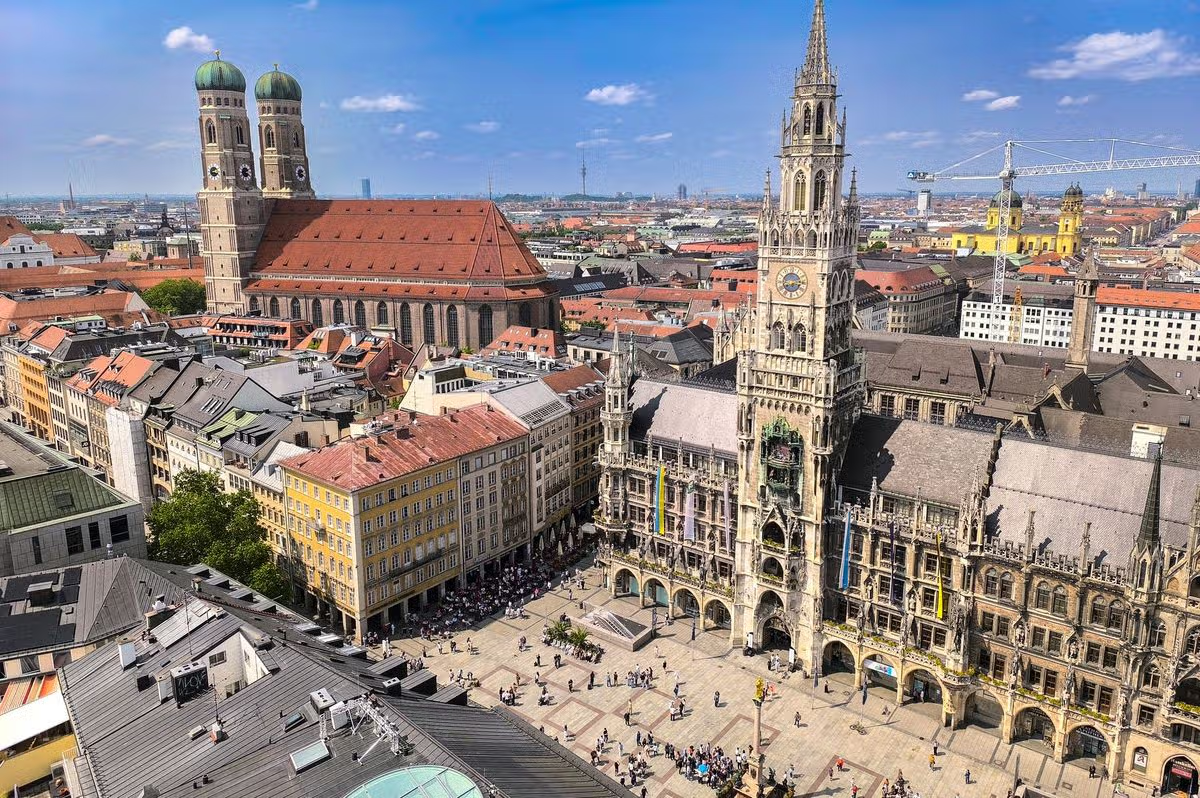
Germany has the largest GDP in Europe(Image: Getty)
When you think about wealthy countries, places like Dubai, China and the US might spring to mind. However, Europe has its fair share of rich countries too. The wealthiest of all has been revealed in new data this year, and it’s not Luxembourg or Sweden.
According to figures from the World Population review, Germany is Europe’s wealthiest country when judged by gross domestic product (GDP). Germany has a GDP of $5.45trillion (£4.026T).
What is GDP?
GDP is a way to measure a country’s productivity and prosperity. The GDP of a country is the total monetary value of all goods and services which that country produced within its borders over a year.
To calculate it, economists take the spending of everyday consumers, the investment of businesses in the country, and government spending and net exports to figure out the final calculation.
If GDP is rising year on year, it’s a good sign that the country is doing well financially. If it is consistently lowering, it’s a sign of an incoming recession.
Is it accurate?
GDP is not a very accurate indicator of the prosperity of a country’s people. It does not indicate how the wealth is distributed, nor the happiness or individual wealth of people.
These flaws are why GDP is often calculated alongside other metrics such as the Human Development Index, which measures the economy as well as life expectancy and education to get a better idea of how a country is functioning.
There’s also the Inclusive Wealth Index, which measures the “savings account” of a country by looking at infrastructure, natural resources and workforce alongside its finances.
How does the UK compare?
According to the most recent data, the UK is in second place with a GDP of $4.23trillion (£3.148T).
France is in third place with $3.17trillion (£2.654T), Italy fourth with $2.42trillion (£2.021T), and Russia fifth with $2.21trillion (£1.962T).
In the case of Germany’s GDP, it is larger than two other European nations combined. Portugal has $380.6billion (£281.0B), and Greece has $307.6billion (£227.1B).
Brits now prefer taking multiple UK-based micro-cations throughout the year and EV savings make cost-effective short breaks even cheaper.
11:55, 24 Aug 2026Updated 12:00, 24 Aug 2026
Smart Energy GB explore how Brits are enjoying Bank Holiday weekend
More than four in 10 Brits now favour taking several UK-based micro-cations throughout the year – rather than a single annual holiday, according to new research. A survey of 2,000 adults revealed they would rather put the money a big getaway would cost towards multiple short breaks spread across the year. A fifth are planning one of these short trips – within 100 miles of their home – this bank holiday weekend.
According to the findings, 44% are now taking more micro-cations than they were five years ago. Three quarters enjoy these types of breaks as they have helped them uncover more historical landmarks, coastal towns, and greater swathes of the British countryside.
The study, commissioned by Smart Energy GB, found 49% have taken a micro-cation in the past year alone, while 58% agreed micro-cations are now firmly part of their annual travel plans. For 44%, they have become a first-choice option.
Victoria Bacon, director at Smart Energy GB, said: “With household budgets under pressure, shorter breaks closer to home offer the chance to relax, recharge and create lasting memories without travelling far and often at a lower cost.”
The research also revealed that 69% agreed a micro-cation was more affordable than heading overseas, and of those who have swapped a foreign holiday for a micro-cation, 67% did so to save money.
Of those who’ve cut costs by taking this type of break, 34% have used the extra cash to enjoy more short trips, while 47% put it straight into their savings.
The research also surveyed 593 EV drivers and discovered that almost half (47%) said owning an electric vehicle has made them more inclined to take a micro-cation.
Two in five (39%) appreciated the ease of setting off from home with a fully charged car, without having to hunt down a service station or public charging point.
Based on publicly available data verified by New Automotive, a 200-mile round trip costs £36.57 in fuel in an average family car. By contrast, it costs as little as £14.92 to charge an EV at home on a standard electricity tariff to cover the same distance – a saving of 59%.
Meanwhile, smart meter owners can trim costs even further by charging overnight on a flexible EV tariff – bringing the cost down to just £4.57 on average. It turns out that 37% of electric car drivers are already doing this, compared to just 14% who opt for public charging points.
Victoria Bacon added: “By using a smart meter to access an EV tariff that fits your needs best, you can save a significant amount on travel costs by charging during cheaper, off-peak periods.”
Double Olympic champion and EV enthusiast, Helen Glover OBE, said: “Some of our best family adventures haven’t involved travelling hundreds of miles – they’ve been spontaneous trips that are less than a couple of hours away by car.
“Whether it’s the rolling countryside of Devon, the dramatic coastline of Cornwall or the peaceful trails of Dartmoor, there are so many hidden gems waiting to be discovered.
“As an EV driver, those local adventures can be more affordable, convenient and sustainable too.”
TOP 10 REASONS BRITS ARE PACKING FOR A MICRO-CATION:.
NS&I has just improved the prize draw odds but the personal finance expert has warned over the best place for money
11:18, 24 Aug 2026Updated 11:24, 24 Aug 2026
Martin Lewis has given advice for anyone with Premium Bonds on the chances of winning(Image: ITV)
Personal finance expert Martin Lewis has told anyone with Premium Bonds about the ‘£5,000 rule’ and warned about the chances of actually winning anything. The ITV and BBC star has said that unless people have at least £5,000 in there, the statistics suggest they might be wasting their time.
Premium Bonds are a government-backed UK savings product issued by NS&I (National Savings and Investments). Instead of earning regular interest, a person’s money buys unique £1 bond numbers that are entered into a monthly prize draw to win tax-free cash prizes ranging from £25 to £1 million.
Mr Lewis has spoken out about the bonds, and last week, in a new update, NS&I said that there will be an increase to the Premium Bonds prize fund rate and improved odds from the September 2026 draw. There will be an estimated £63 million of extra tax-free prizes in September, compared to August 2026, NS&I said. There is also an immediate interest rate increase for around 428,000 Direct Saver and 222,000 Income Bonds customers.
More than 22 million Premium Bonds holders will see a boost to the prize fund rate to 4.35%, up from 3.80%, for the September 2026 draw. At the same time, holders will have even more chances to win, with the odds shortening to 21,000 to 1 from 22,000 to 1. The Premium Bonds prize fund rate and odds were last improved in July 2026.
However, Mr Lewis has said that people would have a much better return with normal savings – if they don’t put enough money in – because of the odds. He explained that premium bonds are only worth getting if you have a certain amount of money. In particular, he advised that many grandparents would be better off giving grandchildren cash via normal savings accounts.
He said: “For years, many people, especially grandparents, have gifted their children premium bonds. And frankly, in my view, for many they would’ve done better sticking with normal savings. Premium bonds are government-backed savings, where the interest is based on a prize draw. The current prize fund rate is just 3.6 per cent, yet even that overestimates what most people will actually win with typical luck.”
Martin said that premium bonds are typically only worth buying if you have more than £5,000, to give you a chance of winning the prizes. He noted that premium bonds are “best for”: Those with larger savings, say over £5,000, as then you’ve a better chance of earning closer to the published prize fund rate. “With less, the odds are you will win little or nothing”, he said
Those who pay tax on their savings interest, who have used up their ISA allowances, as premium bond winnings are always tax-free
He added: “As most children have small amounts of savings and aren’t taxpayers, premium bonds are particularly unsuitable. Of course, there’s the ludicrously small chance your child will win a million, but they could also toss a coin and it land on its edge.”
“So if you’re thinking of putting £1,000 or less into premium bonds for a child, it’s worth noting that with average luck our premium bonds probability calculator shows they are likely to win nothing over a year (give it a try based on your scenario).”
He has also delivered his assessment of Premium Bonds in general: “Premium Bond prizes aren’t taxed, which means that if you’ve larger savings in cash, and have maxed out your £20,000 a year ISA allowance and earn enough interest to exceed your PSA, Premium Bonds are probably a decent choice… if you can accept the random nature of the ‘interest’.
“For everyone else, cash ISAs – savings accounts you never pay tax on – are still likely to be the better choice. The top easy-access cash ISA rate is currently 4.4% – slightly lower than the standard non-ISA rate, but tax-free and offering a guaranteed return that’s higher than the current Premium Bond prize rate of 3.6% (which you need to be lucky to get).”
He also said the prize rate – 4.35 per cent from September up from 3.80 per cent is the average return. He said: “The smallest prize is £25. So what happens on £100 is a lot of people get nothing and a few get £25.” He said the mena average, which is 4.35 per cent from Sept, but more important: “Is the median average which is zero on £100 in Premium Bonds over a year.
“Median is if you lined everybody up who had £100 in Premium Bonds from those who win the most to those who win the least what would the person exactly halfway along win.
“The first thing to say is someone with typical luck will always win less than the mean average. What affects the amount you win, generally, is the amount you’ve got in. The more you have in the closer you will get to the mean average on typical luck.”
However, the ‘tax-free’ nature of Premium Bonds could offer a benefit, he suggested: “Most people do not pay tax on savings. That’s because, as well as your normal personal allowance up to £12,570 a year you can earn from any source, most people are getting either a £1,000 personal savings allowance – so that’s £1,000 of interest they can earn a year without paying tax on it – or £500 personal savings allowance if you are a higher rate taxpayer.”
If someone has a lot of savings, it could mean they’re paying tax on the interest, and if that’s the case, he said people should consider making sure their ISA allowance is full.
He said: “If you’ve got a cash ISA allowance available, I’d be putting it there. Then, if you’re paying tax on your savings and you’ve filled up your cash ISA allowance, and especially if you’re higher rate taxpayers which means you’re going to be losing 40 per cent off your savings interest on any that you pay tax on, at that point, Premium Bonds even on typical luck at around 3.2 3.3 per cent after tax start to look good value.”
Mr Lewis also urged people to place their savings in high-yield accounts. For those who relish the excitement of potentially winning big, he proposed purchasing a small Lotto ticket: “To all those people who say ‘what about the thrill of winning’, yes there’s the thrill of winning but, you know what, if you put savings account, you’re going to win interest each month and you’ll know exactly how much you’ll be getting and it’ll probably be bigger.
“There is a chance of winning a million, but if you really want to talk about the thrill of winning, then it’s probably far more sensible and more effective for those people who don’t pay tax on savings and who aren’t higher rate taxpayers, to go and put their money in top savings and then take a couple of quid out and put it in the National Lottery and then you get your thrill of winning anyway but you get more return on the underlying savings.”
NS&I responded at the time: “Premium Bonds remain one of the nation’s favourite savings products and are a flexible and fun way to save. They offer the excitement of potentially winning tax-free prizes every month, the safety and security of the 100% government guarantee, and easy access to withdrawals.
“Every Premium Bond has a separate and equal chance of winning a prize each month, however the more Bonds you buy, the better your chances of winning.
“Each month we pay out millions of prizes ranging from £25 to £1 million. In our most recent draw, there were more than 6.1 million prizes worth over £403 million.”