Healeys

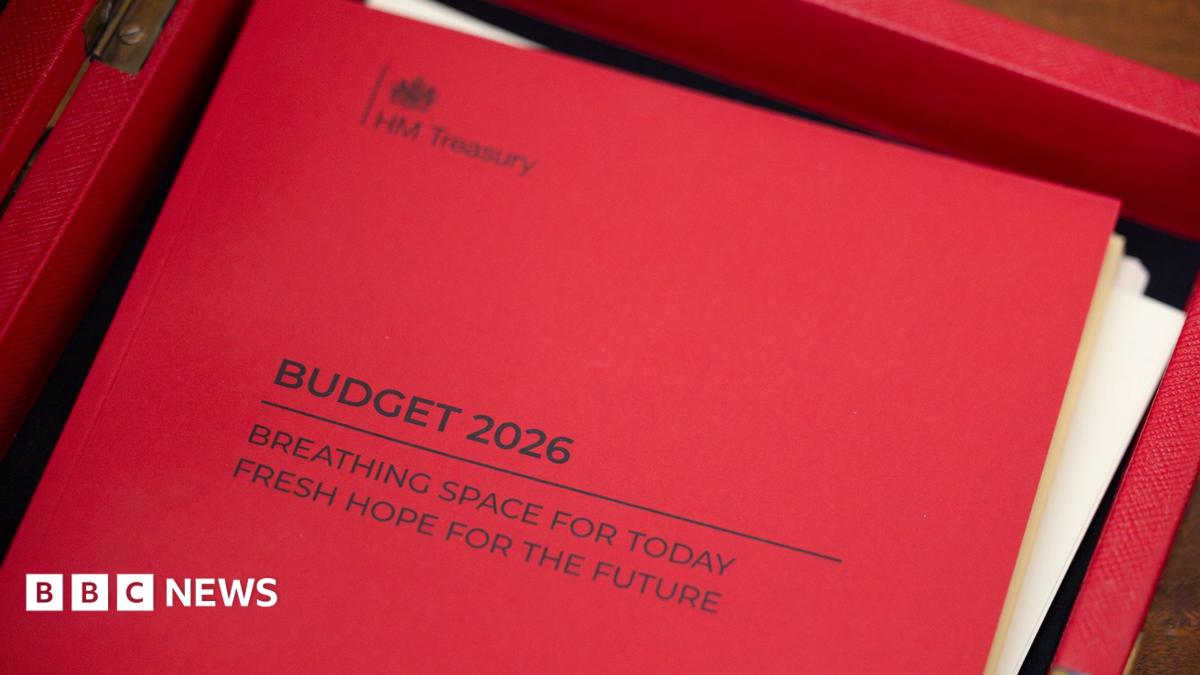
Budget 2026: Key points from John Healey’s speech

  • One-off £100 payment for up to 20 million households in council tax bands A-D in England to help deal with rising energy bills, with equivalent funding for Scotland, Wales and Northern Ireland

  • Standing charges – fixed daily fees customers pay regardless of usage – to be removed from household gas bills in England, Scotland and Wales, with costs added to the unit rate instead

  • VAT cut on electricity bills extended beyond April to July

  • A green levy – the Gas Shipper Obligation to fund hydrogen projects – to be removed from energy bills and put on to general taxation

  • Freeze on fuel duty extended again to July

  • Import taxes to be removed on more than 100 food products, including gherkins and marmalade, as well as kerosene and fertilisers

  • A 55p per mile tax-free mileage rate for those driving up to 10,000 miles for work made permanent, with the rate rising from 25p per mile to 35p above that distance

  • A new scheme taking 25% off electricity bills for 10,000 firms to launch in April, with payments backdated for energy costs this year

  • Source link

    Healey’s Budget needs to sustain the stronger economy through gathering clouds

    Back in Healey’s time under Gordon Brown, there was no OBR. Back then it was not unknown for late budget maths problems to be settled with an optimistic tweak of a forecast, a date change to the economic cycle, or choosing a stronger rate of long term growth.

    The OBR’s verdict is crucial now – to what extent it agrees with projected welfare savings or even the importance it places on stronger GDP figures matters now.

    The bigger point here is that the chancellor must be shocked by the contrast between the sheer power of the Brown Treasury to do what it wanted, and the reality of what he currently faces: the constraints of the OBR, manifesto red lines, bond markets, significant debts and an energy shock.

    There are reasons to postpone some of the toughest decisions beyond this Budget, such as how to fund desired increases in spending on defence and social care. The economic outlook could improve were the Iran war to settle at some point in the next few months, and after revised statistics the OBR may also have cause to rethink last year’s downgrade to long term economic growth.

    There is an imaginable pathway to a forecast next year with higher growth, lower inflation and lower debt interest costs, plausibly improving the public finance projections by tens of billions.

    This would be a much more agreeable basis upon which to decide the pace of those big ticket spending rises. It also may be a tempting option for anyone thinking about an election. Former Treasury officials lament: “There is always a reason for procrastination.”

    Expect the Chancellor to laud the resilience and strength of the UK economy and seek to sustain it, and spread growth geographically. His key judgement, however, will be a balance between extra financial and economic support and the peril of still elevated borrowing costs.

    He will try to offer breathing space. It may be needed not just for households and families, but for the Exchequer itself.

    Top image credit: Reuters/Getty Images

    Source link

    Banks expect tax increase in Healey’s first Budget

    Senior banking executives have told the BBC they expect the sector to be “on the menu” when the chancellor announces his Budget in two weeks’ time.

    John Healey has described the banks as part of “the crown jewels” of the UK economy, yet has refused to rule out a raid on the sector.

    The biggest four banks collectively made around £15bn profit in the first six months of this year, leading to calls from trade unions and others for additional taxes.

    However, the banking sector trade body, UK Finance, warned that “further increases in bank taxes would weaken competitiveness, discourage investment and job creation, and work against the government’s ambition to deliver growth in every postcode”.

    The UK’s biggest banks and building societies currently pay a surcharge of 3% on top of the baseline 25% rate of corporation tax, plus a levy on the assets held on their balance sheets.

    The sector contributed nearly £40bn to the Treasury last year, if income tax on employees is factored in.

    The bank levy generated £1.4bn last year and the surcharge a further £1.2bn.

    There are a number of ways the chancellor could extract more money from the sector.

    The 3% surcharge was reduced from 8% under Rishi Sunak when he was chancellor, at the same time as he raised corporation tax from 19% to 25%. Returning the surcharge to its previous level could raise around £2bn a year.

    The bank levy currently charges 0.1% on outstanding short-term loans and 0.05% on longer-dated loans, although mortgages are excluded from the calculation.

    In the past banks have successfully argued that higher taxes would risk making the UK uncompetitive with other jurisdictions and would reduce their ability to lend, and therefore be anti-growth.

    In truth, banks were pleasantly surprised they were not hit at the last Budget, given the large profits they have been making in recent years. Rising interest rates have expanded the margin between the rate at which they lend to customers and the rate they pay savers.

    There is another option that has been discussed with Treasury officials. Currently banks can use losses from the past to offset against profits – thereby reducing their tax bill in any given year. Lloyds in particular has been a beneficiary of this policy, as large losses from the financial crisis have been used to lower tax bills ever since.

    Some analysts and bank executives have pushed the idea of a moratorium on this practice for a few years, which would yield an estimated extra £1bn per year for the Treasury. That would provide a windfall while being “a lot more bearable”, in the words of one bank executive.

    It would also spare foreign banks from an additional hit, including JP Morgan, whose chief executive Jamie Dimon has warned that the UK already has one of the highest tax burdens on banks in the world. He warned that adding further sector-specific taxes could discourage investment and damage competitiveness.

    However, industry leaders say any form of tax rise that hits UK banks and exempts foreign banks’ operations in the UK would be hard to square with the government’s push to back British business.

    Whatever form it takes, banks believe the chancellor now has much more of an appetite to take a larger slice of their pie.
    Source link