Global

How US sanctions on Iran ripple through global markets and consumers | Business and Economy News

The administration of United States President Donald Trump has announced new economic sanctions on Tehran, describing the measures as an “economic D-Day” as the US war on Iran approaches the six-month mark.

US Treasury Secretary Scott Bessent announced the sanctions on Monday, alongside a naval blockade of Iranian ports.

Recommended Stories

list of 4 itemsend of list

Bessent said the sanctions target key sources of Iran’s revenue, including its oil and gas industry, and called on countries around the world to cut economic ties with Tehran.

What are the sanctions?

The Treasury Department said the sanctions will target Iran’s aviation, digital assets, gold, technology and shipping sectors, as well as impose sanctions on 60 specific individuals and vessels.

“The main point is that Iran seems to have much less room than it did in previous years to simply work around sanctions,” Peiman Salehi, a Tehran-based geopolitical analyst, told Al Jazeera.

Bessent also said on Monday that the new sanctions expose Tehran’s trade partners to secondary penalties. According to a Treasury Department release on Monday, the targets include ships based in or associated with countries including Singapore, China, and Hong Kong.

“Today’s sanctions are mostly incremental, but are part of trying to intimidate remaining trading partners into cutting ties [with Iran],” said Rachel Ziemba, an adjunct senior fellow at the Center for a New American Security think tank.

“There’s a lot of signalling and bluster aimed at getting other countries to crack down on entities involved in grey-zone trade, but new measures are mostly incremental for now,” she said. Grey-zone trade refers to both illegal, underground trade and trade that is unsanctioned but difficult.

The Treasury Department said Iran has used cryptocurrency to circumvent its longtime sanctions and facilitate transactions involving the Islamic Revolutionary Guard Corps (IRGC) and members of the Iranian regime. The department also said Iran has used gold to help prop up the value of its currency amid economic instability.

The new shipping sanctions target Iran’s state-linked shipping fleet, which the Treasury Department alleges is being used to transport oil as well as “sensitive weapons components”.

The technology sanctions are intended to restrict Iran’s acquisition of materials that could be used in its weapons programmes. The aviation sanctions target Iranian airlines that the Treasury Department alleges are being used to transport weapons and military personnel, as well as financial resources to Iran’s proxies.

Washington also indefinitely suspended several broad exceptions to its ongoing sanctions on Iran, including those covering academic exchanges, personal money transfers and certain sporting activities. Organisations currently engaged in those activities have until September 8 to wind down their operations.

Ziemba says these measures “will have more effect on Iranians, not just the regime”.

What sanctions were already in place?

Washington’s sanctions on Iran have been in place since 1979, after students took hostages at the US Embassy in Tehran, and increased over the next 45 years. Sanctions were briefly paused, however, after the administration of President Barack Obama and world powers signed a nuclear deal with Tehran in 2015. But the Trump administration withdrew from the deal during its first term, in 2018, bringing back old penalties while adding new ones.

Washington imposed new sanctions during Trump’s second term, many of them before the US and Israel first struck the country on February 28.

In February 2025, the Treasury Department sanctioned 30 individuals and vessels involved in the “brokering [of] the sale and transportation of Iranian petroleum-related products”, according to a department release. The targets were based in several countries, including India and China.

In December 2025, Washington sanctioned 29 vessels it accused of being part of a so-called shadow fleet used to transport Iranian petroleum. It also sanctioned Egyptian businessman Hatem Elsaid Farid Ibrahim Sakr over his businesses’ alleged ties to seven of those 29 vessels. The measures continued the 1979 sanctions campaign against Iran’s oil industry.

The Treasury Department stepped up the sanctions again in April 2026, targeting another two dozen individuals, companies and vessels operating within the network of Iranian oil shipping magnate Mohammad Hossein Shamkhani, the son of now-deceased senior Iranian security official Ali Shamkhani.

Later that same month, the Treasury also targeted what it described as “regime-linked cryptocurrency” and said it had seized nearly half a billion dollars from so-called “shadow banking networks”.

How have sanctions affected US consumers?

Pressure on the Iranian oil market, both through existing sanctions as well as the current war, has tightened the rest of the globe’s oil supply and affected countries that buy Iranian oil.

China, for example, is the primary destination for Iranian oil, buying roughly 90 percent of Iran’s crude oil exports. Beijing bought 1.4 million barrels per day in 2025.

At the same time, Asian markets, China included, also heavily rely on oil travelling through the strategically vital Strait of Hormuz, where roughly one-fifth of the globe’s oil transited before Iran choked off the route.

This has put pressure on the global oil supply, meaning the benchmark for crude oil has ticked up, translating to higher prices on fuel and food.

For US consumers, that has been most apparent at the petrol pump. The average price for a gallon of petrol (3.78 litres) is $4.09, up from $2.98 on February 28 when the US and Israel first struck Iran, according to the American Automobile Association (AAA), which tracks daily petrol prices.

Experts warn that if Iran retaliation accelerates, it could hit Americans hard.

“If sanctions provoke Iranian retaliation against Gulf shipping, materially reduce oil exports, or cause insurers and shipping companies to avoid the region, then Americans could feel it very quickly through gasoline, diesel, airfares, freight costs and ultimately inflation,” John Deal, managing director of capital markets at Post Oak Group investment bank, told Al Jazeera.

The economy and Iran are emerging as key issues heading into the US midterm elections, with voters expressing dissatisfaction on both fronts. That could put pressure on Republicans in competitive races, including in traditionally red states such as Texas.

A late-July Reuters/Ipsos poll suggested that only about a third of Americans supported the war, while just 28 percent of respondents in a CNN poll approved of Trump’s handling of Iran.

On the economy, an AP/NORC poll suggested that 32 percent of Americans approved of Trump’s performance. A recent Reuters/Ipsos poll, meanwhile, suggested that Democrats were narrowly ahead of Republicans on which party voters trust more to handle the economy—the first Democratic advantage in roughly a decade.

How are the sanctions affecting markets?

The latest sanctions announcement is weighing on Wall Street as well as the oil and gold markets.

On the heels of the announcement, the price of gold, largely considered a safe investment during times of economic uncertainty, jumped by 0.8 percent to $4,639.49 per ounce (28 grams) in midday trading, ticking up to its highest level since mid-May.

As for oil, prices pulled back on Monday after two weeks of gains. The price of the global benchmark Brent crude tumbled by more than 2 percent on Monday to $85.22 a barrel.

On Wall Street, the major indices are mixed amid the latest sanctions news as well as Trump’s announcement of new tariffs on Canada. The Nasdaq is down 0.5 percent, and the S&P 500 is down 0.2 percent. The Dow Jones Industrial Average, however, is trending in positive territory, 0.2 percent higher than the market open on Monday.

The oil sector is taking a hit. Chevron is down 0.8 percent, ExxonMobil tumbled 0.9 percent, BP fell more than 2 percent, and Shell is down 0.2 percent.
Source link

The Biggest Winner in Sports May Be the Insurance Industry| Global Finance Magazine

As the sports economy grows, insurers rush to cover risks from World Cup disruptions to NIL liabilities.

This article appears in the September issue of Global Finance Magazine.

On 104 separate occasions in June and July, World Cup organizers tried something new. They held games at 16 venues across Mexico, the U.S., and Canada. More games in more locations increased the risk of cancellation due to threats of terrorism, fire, and climate-related catastrophes, as well as cyber incidents and other disruptions.

Long before players took the field, a small army of insurance professionals analyzed risks, negotiated policies, and drafted contracts to help ensure FIFA would not suffer crippling financial losses if an event was canceled. FIFA carried about $1 billion in event-cancellation coverage for this year’s tournament, up from an estimated $900 million for Qatar in 2022, according to Mario De Cicco, vice president of Morningstar DBRS’s Global Insurance & Pension Ratings group. 

FIFA is just one component of the mammoth worldwide sports industry, which the World Economic Forum estimates generated $2.3 trillion in revenue in 2025. 

“It’s not only the large events like the World Cup which are becoming more frequent and more complex,” said De Cicco. “There is also growing participation at every level, from amateurs to professionals. So there are more potential financial losses, and that creates higher demand for insurance protection.”

The magnitude of the money isn’t the only thing that’s changed; the risks CFOs must insure against are also evolving. A decade ago, sports insurance meant stadiums, workers’ comp, and injured players. Today it means ransomware, brand damage, NIL (name, image, and likeness) contracts, and even sports-betting integrations with little or no actuarial history, forcing carriers and brokers to build coverage from scratch in real time for risks that may not have existed five years ago.

Burgeoning demand has transformed a specialty market into a profit center for insurers, according to De Cicco. Large carriers such as Zurich, Munich Re, Swiss Re, and Allianz dominate the top end, he noted, while niche players like American Specialty Insurance and Berkley Insurance add depth. Often, the largest sports insurance contracts are underwritten by a syndicate, using a risk-sharing structure to mitigate catastrophic losses.

The Change at Colleges

Rory Lough,
Gallagher

College sports illustrate what can happen when rapid growth hits an area with little or no actuarial history. Much of the growth comes from NIL compensation and the revenue-sharing framework established by the landmark 2025 House v. NCAA decision, which turned university athletic departments in the U.S. into direct payers of athlete compensation — and bearers of financial risk when a star gets hurt.

Zurich entered the market in August 2025 with the sports-data firm Players Health, after about 15 years of providing coverage to schools and sports organizations. They built a product that reimburses institutions for NIL value when an athlete misses at least 40% of a season, up to policy limits of $2 million. However, for the new line, Zurich had no direct actuarial history.

“We weren’t pricing it blind,” said Marty Banaszek, head of Group Accident at Zurich North America; Players Health’s underlying injury data across sport and position helped to make the risk underwritable. Premiums run roughly 6% to 12% of contract value, weighted toward the highest-exposure positions: “starting quarterbacks, starting running backs,” Banaszek said.

Tate Gillespie, vice president of NIL Strategy & Partnerships at Players Health, helped build the product with Zurich. His “aha” moment came while working in sports at the University of Kansas, when the team’s starting quarterback, a player earning significant NIL money, was injured. A friend and eventual Players Health co-founder asked what the university’s risk management plan was, assuming there wasn’t one. 

“You realize that’s not how the National Football League does it,” his friend said, pointing out that pro teams had been insuring against this kind of loss for years, but nothing like it existed in college sports.

The combined NIL and revenue-share market is approaching $3 billion today, Gillespie estimates, and he projects it will reach $4 billion to $5 billion in a year, with 30% to 40% annual growth. Banaszek frames buying behavior in financial terms: “These organizations really need to think of this spend as an investment portfolio, not dissimilar [to] how insurance or other financial institutions make investment decisions.”

When Risk Stopped Being Physical

That’s already the case, said Rory Lough, senior vice president at global brokerage Gallagher, who pointed out that NIL has broadened exposure well beyond the training room. It now includes athlete protection, contractual and business liability for collectives, and institutional compliance risk related to Title IX and employment classification. 

“Stakeholders are no longer looking at insurance as simply protection against injury,” she said. That newly intangible category of risk — brand, data, governance — runs through nearly every exposure. Cyber touches it all, from contract records and fan payment data to medical files, compliance documentation, and more.

Cybercriminals target major sporting events for their high visibility, said Jeffrey Lang, senior vice president and California Platform Leader at brokerage Trucordia. However, the risk is particularly hard to price because of its relative newness and the perpetrators’ adaptability. A game-day ransomware attack on a stadium operator can simultaneously bring down payment systems, digital ticketing, security access, and broadcast feeds. Risk rises with AI deepfakes and misinformation that can derail a team’s reputation. 

“How do you put a precise dollar figure on lost brand trust or broken sponsor confidence?” Lang asked. “You can measure the cost of rebuilding a damaged wall, but calculating the financial damage of a ruined reputation is much harder.”

Ten years ago, he said, he would talk with prospects about insuring their stadium against fire or property damage, covering concourse slip-and-falls, buying workers’ comp for staff, and securing basic coverage for player injuries or weather-related cancellations. If something broke or someone got hurt, the carrier absorbed the financial hit. That playbook, Lang said, no longer applies.

Much of the sports insurance build-out can be ascribed to the growth of major sports franchises, some of which have become multifaceted corporations, worth more than many Fortune 500 companies. They run real estate portfolios, media companies, and massive data operations. 

But the nature of the insured is different too. 

“The big difference between a sports franchise and a typical corporate entity is visibility,” Lang added. “If a corporate server goes down quietly, it’s an internal headache. If a stadium’s entry system fails live on international TV and in front of 70,000 fans, it’s global news instantly.”  

Weld Royal is a contributing writer based in the U.S.

Source link

Ebola cases in DRC hit 5,515 as Pope Leo urges global action to save lives | Ebola News

Case fatality rate climbs to nearly 48 percent in the DRC, meaning almost one in two people infected with Ebola are dying.

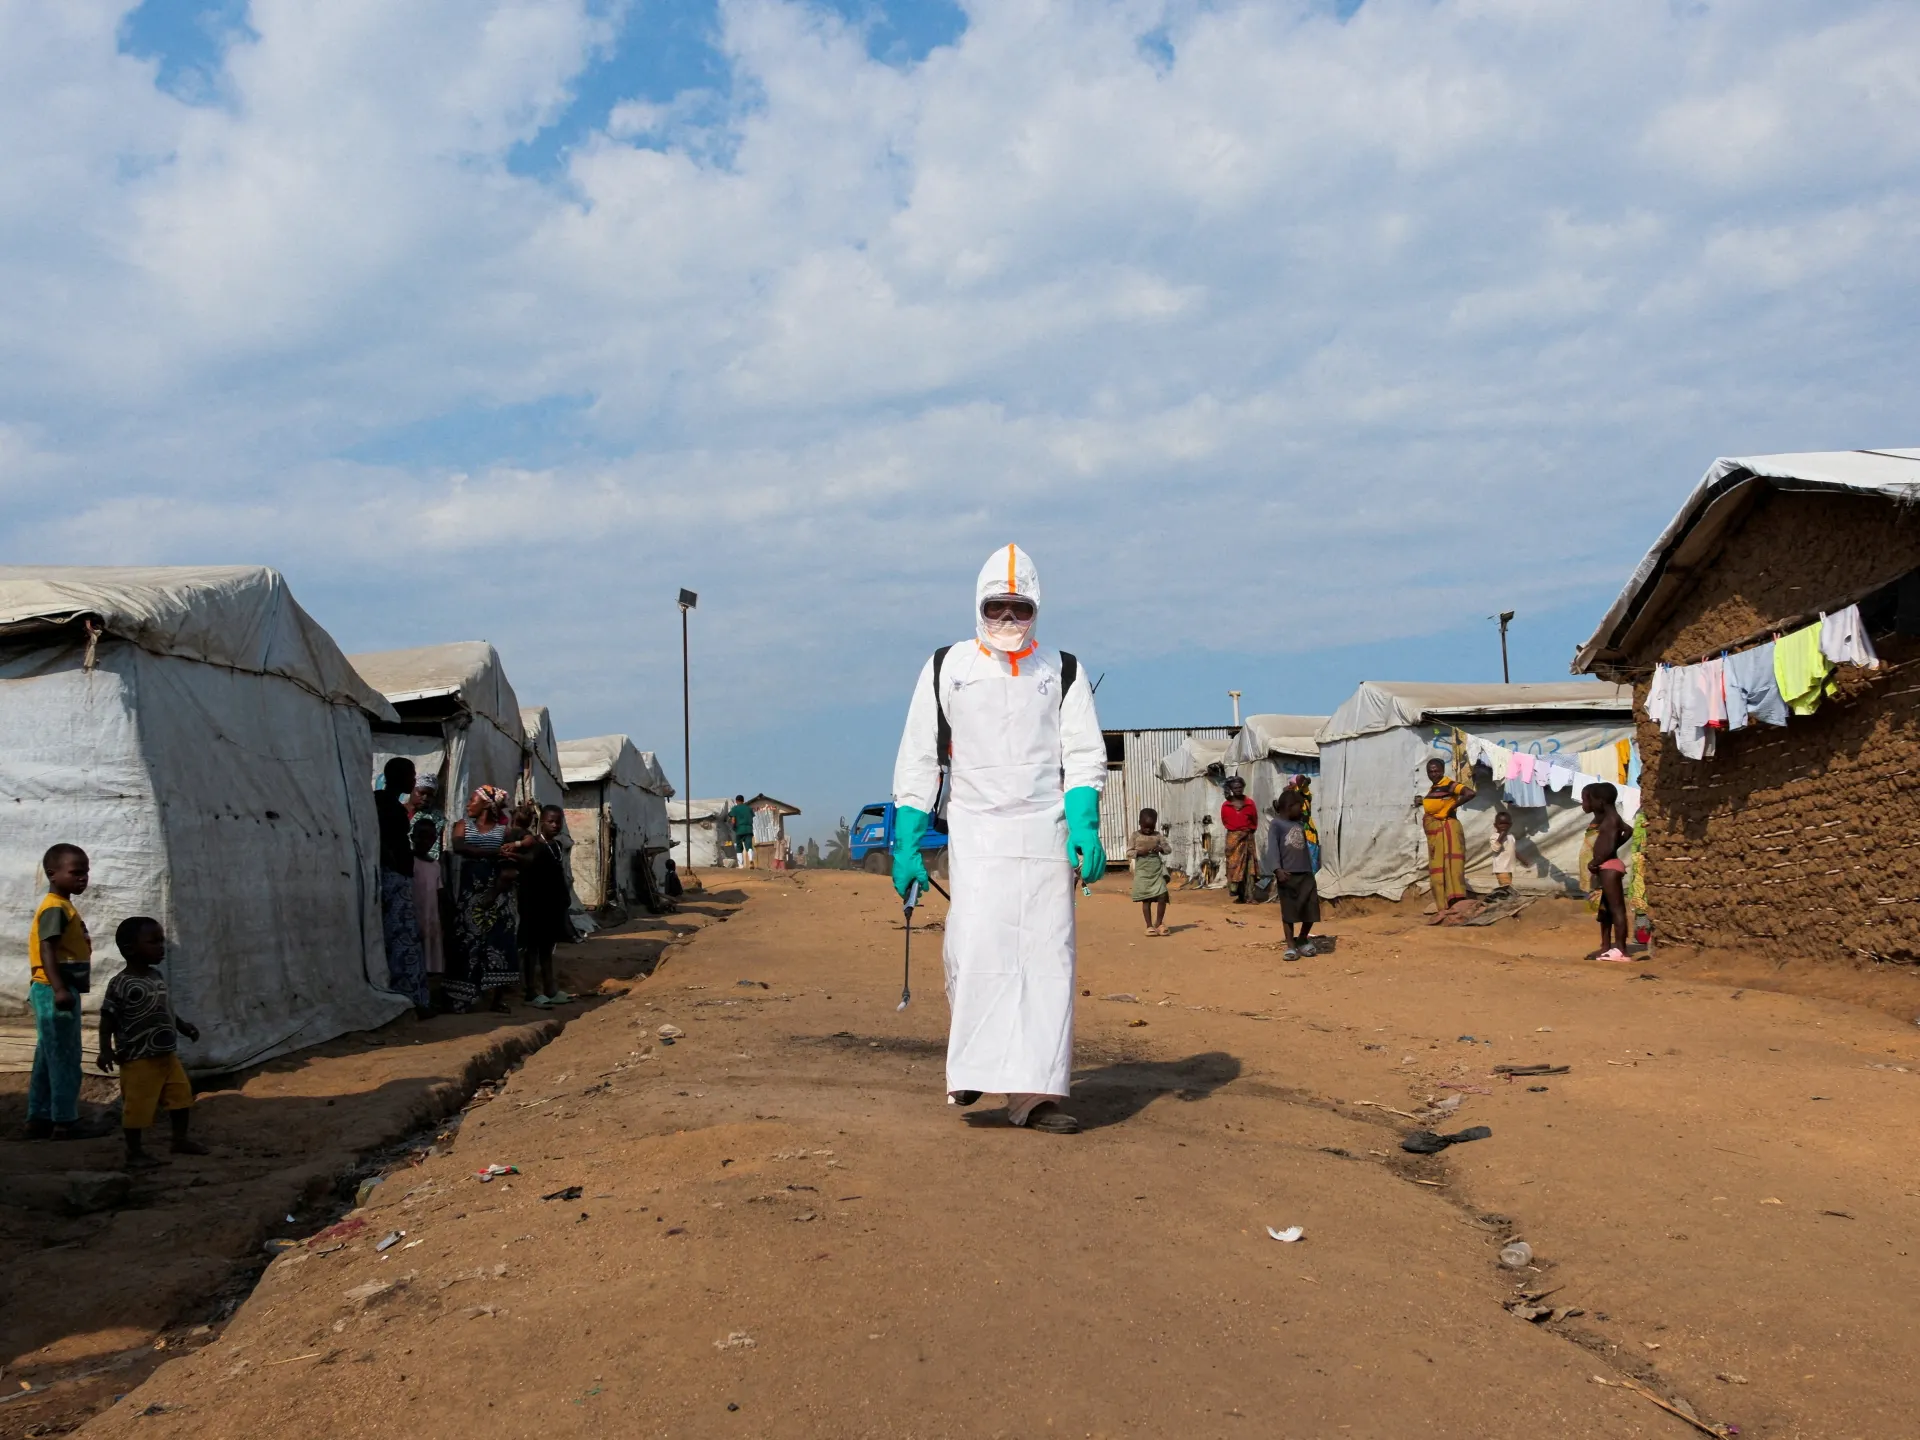
The Ebola outbreak in the Democratic Republic of the Congo (DRC) has reached  5,515 confirmed cases of infection and killed 2,642 people, with 51 new cases detected in Ituri and North Kivu provinces, according to the latest government figures.

The update on Sunday came as Pope Leo called for ⁠international action to help contain the epidemic, which is now the deadliest Ebola outbreak in the DRC’s history.

Recommended Stories

list of 3 itemsend of list

Declared in mid-May, it is the DRC’s 17th Ebola epidemic and was designated a Public Health Emergency of International Concern by the World Health Organization (WHO), its highest alert level, also covering neighbouring Uganda.

The outbreak is now on track to surpass the deadliest Ebola epidemic on record, which was the 2014–2016 outbreak in West Africa that killed more than 11,000 people.

According to government figures, the case fatality rate in the DRC has climbed from about 20 percent in early June to nearly 48 percent now, meaning almost one in two people infected are dying.

Contact tracing, however, has improved sharply, from 30 percent in June to more than 85 percent.

The disease has also proved deadly for those fighting it. About 160 health workers have been infected, and about 45 have died, according to the WHO.

Efforts to contain the outbreak, however, have been hampered by armed conflict in the affected provinces, displacement, attacks on medical personnel and facilities, a mobile working population and a lack of critical infrastructure.

Vaccines arrive in DRC

There is no approved vaccine or treatment for this particular strain of Ebola, known as Bundibugyo, which is rarer than the virus type behind most past outbreaks.

The WHO has pledged 70,000 doses of the Ervebo vaccine, which is licensed for Ebola and has been effective in past outbreaks. According to the global body, early data from animal trials suggest it may offer some protection against Bundibugyo.

Some 16,250 doses of the vaccine arrived in the DRC on Friday.

WHO Director-General Tedros Adhanom Ghebreyesus and other officials said the response in the DRC needs to be scaled up two to threefold to contain the outbreak and reach every affected area.

They also called for more support and protection for front-line health workers, including protective equipment, timely payment, and access to rapid diagnosis and high-quality supportive care if they fall ill.

Abdulsalami Nasidi, a public health consultant who helped establish the Africa Centres for Disease Control and Prevention, told Al Jazeera that the outbreak was “getting out of hand”.

He blamed weak infection control measures and a lack of trust between authorities and affected communities for the continued transmission.

“This is no longer just a national or regional issue; it is a global issue. If it spreads to neighbouring places with lower immunity, it will be a disaster,” Nasidi added.

The WHO currently rates the risk to the global public as low, but warns that the danger inside the DRC remains very high.

Despite the surging cases, Uganda and several health zones in DRC’s Ituri and South Kivu have interrupted transmission, which the WHO said is evidence that rapid detection, decisive leadership, and community cooperation can break the chain of transmission.

At the Vatican on Sunday, Pope Leo offered prayers for the DRC, “in light of the spread of the Ebola epidemic, which is sadly ⁠claiming many lives”.

The pontiff also called for global action to help save lives.

“I urge the international community to ⁠respond in a way that also involves local communities ⁠in prevention efforts to save ⁠as many lives as possible,” he said.

Source link

Could the Iran War Spark a Prolonged Global Fuel Crisis?

The Iran war has pushed the global energy system into a deeper crisis, with the disruption increasingly shifting from crude oil supplies to the refined fuels that power transportation, industry and economies worldwide.

While global oil markets have adapted relatively well to the loss of a significant share of Middle Eastern crude production, the refining industry has had far fewer options to compensate.

That imbalance is already visible in fuel prices.

Brent crude is around $90 a barrel, roughly 25% above its level when the conflict began on February 28 but well below its wartime peak of $118.

Stay ahead of the geopolitical week.

MD Briefing delivers expert analysis across five global fronts — the Indo-Pacific, energy, geoeconomics, European security, and the Middle East — every Monday morning. Free.

Refined fuel prices, however, have remained much higher. European diesel prices have risen more than 70% since the start of the war, while U.S. gasoline prices have increased around 60%.

The growing divergence suggests that the biggest energy shock may no longer be coming from crude oil itself, but from the world’s ability to turn crude into usable fuel.

Why Are Fuel Prices Rising Faster Than Oil?

The key problem is declining refinery capacity.

The International Energy Agency estimates that more than 20% of the Middle East’s 9.6 million barrels per day of refining capacity was knocked out during the conflict.

At the same time, the closure of the Strait of Hormuz has restricted fuel exports and disrupted the movement of Gulf crude.

The result has been a chain reaction.

Refineries, particularly in Asia, have had to reduce operations because of difficulties obtaining crude, while damaged Middle Eastern facilities have struggled to return to normal production.

This has created a shortage of diesel, gasoline and other refined products even as crude oil prices have retreated from their wartime highs.

How Has Russia Made the Fuel Crisis Worse?

The Middle East is not the only source of disruption.

Months of Ukrainian attacks on Russian energy infrastructure have also reduced global refining capacity.

Russian refinery throughput has fallen by nearly 30% in recent months to below 4 million barrels per day.

The decline has forced Moscow to restrict diesel exports, removing another major source of refined fuel from international markets.

The combination of Middle Eastern refinery damage and reduced Russian output has left the global market with fewer alternatives.

That is particularly important for diesel, which is essential for freight transportation, agriculture, construction and industrial activity.

Why Are Diesel Refining Margins Surging?

The shortage is reflected in refining margins.

European diesel refining margins have more than tripled since February, rising above $75 a barrel.

U.S. diesel margins have increased more than 140%, reaching a record $100 earlier this week.

These figures demonstrate how severe the shortage has become.

Refineries capable of producing diesel and other fuels are commanding exceptionally high margins because demand remains strong while available capacity is shrinking.

The problem is that simply increasing refining margins does not immediately create new refining capacity.

Building or repairing refineries can take months or years, particularly when specialised equipment is required.

Have Global Fuel Inventories Been Depleted?

Yes, and that could become one of the biggest problems in the months ahead.

Fuel stockpiles provided an important buffer when the conflict began.

That buffer is now largely gone.

According to the U.S. Energy Information Administration, global oil inventories fell at a rate of around 3.5 million barrels per day between March and July.

Stocks are expected to continue declining through the end of the year.

U.S. diesel inventories are already at their lowest seasonal level in three decades, while gasoline stocks are at their weakest seasonal level since 2012.

This leaves the market increasingly exposed to any additional disruption.

Is There a Global Fuel Production Shortfall?

The data suggests there is.

Global refinery runs during the second quarter were 5.1 million barrels per day lower than a year earlier, according to the IEA.

High fuel prices have reduced consumption, with demand for refined products falling by around 4 million barrels per day.

But that reduction has not been sufficient.

The result was still a shortfall of more than 1 million barrels per day.

The imbalance could become even worse during the third quarter.

Refinery runs are expected to remain 4.1 million barrels per day below last year’s level, while demand is projected to fall by only 2.4 million barrels per day.

In other words, fuel supply is declining faster than demand.

Would Reopening the Strait of Hormuz Solve the Crisis?

Not necessarily.

A diplomatic breakthrough between Washington and Tehran that permanently reopened the Strait of Hormuz could send crude prices sharply lower.

But cheaper crude would not automatically translate into cheaper gasoline and diesel.

The reason is that the refining infrastructure itself has been damaged.

More than 20 Gulf refineries suffered damage during the war, and many require extensive repairs.

Crucial equipment such as compressors, heat exchangers and specialised catalysts can take significant time to obtain.

Lead times for some of these components were already stretched before the conflict.

Consequently, even if crude shipments resume quickly, refinery capacity could remain constrained for much longer.

Why Is China Important to the Energy Crisis?

China’s response could have a major impact on global fuel markets.

China is the world’s second-largest refining centre and sharply reduced refinery processing rates and fuel exports during the conflict.

If Beijing keeps exports limited, the international market will lose another potential source of refined products.

Conversely, an increase in Chinese refinery utilisation and exports could provide some relief.

But China must also balance domestic fuel demand, inventory requirements and its own energy security.

That makes its decisions particularly important for Asia and the wider global market.

Could the Energy Crisis Fuel Global Inflation?

The answer could be yes.

The immediate impact of higher fuel prices is already appearing in inflation data.

U.S. consumer prices rose 3.4% year-on-year in July, with energy costs increasing 14.7% and gasoline prices rising 24.6%.

Euro zone inflation accelerated to 2.9%, driven partly by a 10% increase in energy costs.

Japan’s producer price index rose 7.2% in July.

These figures raise concerns that the energy shock could spread beyond fuel markets.

Higher transportation costs increase the cost of moving goods, while expensive diesel raises costs for agriculture, manufacturing and logistics.

If those increases persist, businesses may eventually pass them on to consumers.

Why Could the Energy Crisis Last for Years?

The central problem is that refining capacity cannot be restored as quickly as crude production.

Oil wells can continue producing once transportation routes reopen.

Refineries, however, require complex infrastructure, specialised machinery, skilled workers and maintenance.

If damaged facilities need major reconstruction, restoring capacity could take years.

At the same time, depleted fuel inventories will eventually need to be rebuilt.

That means refiners could face sustained pressure to process more crude even after the immediate crisis ends.

The result could be a prolonged period of elevated refining margins and fuel prices.

What Does This Mean for Europe and Asia?

Europe and Asia could face particularly severe pressure.

Both regions rely heavily on imported energy and have already experienced increases in refined fuel and liquefied natural gas prices.

For European economies, expensive diesel could increase transportation and industrial costs.

For Asian economies, disruptions to Gulf crude supplies and reduced Chinese fuel exports could create additional pressure.

The combination of higher fuel and LNG prices could therefore create a broader energy inflation shock rather than an isolated oil-market disruption.

Could Consumers Eventually Reduce Demand?

Demand destruction remains one of the few mechanisms capable of restoring balance.

If fuel prices remain extremely high, consumers may drive less and businesses may reduce transportation and energy consumption.

Companies may also delay investment and cut production.

That could eventually reduce demand enough to ease pressure on the refining system.

But demand destruction carries an economic cost.

A reduction in fuel consumption caused by efficiency improvements is very different from a decline caused by households and businesses being unable to afford energy.

The latter can slow economic growth while inflation remains elevated.

Analysis: Why the Refining Crisis May Matter More Than the Oil Shock

The most important lesson from the Iran war energy crisis is that the global energy system is not simply dependent on how much oil exists, but on whether the world can refine and transport that oil into usable fuel.

The crude market has shown considerable resilience.

Refined fuel markets have not.

That distinction could determine how long the current energy shock lasts.

Even if diplomacy reopens the Strait of Hormuz and crude prices fall, damaged refineries, depleted inventories and reduced Russian exports will continue to constrain fuel supplies.

This creates a particularly difficult situation for central banks.

If energy prices rise temporarily, policymakers can theoretically look through the shock. But if fuel shortages persist for months or years, higher transportation and production costs can become embedded across the economy.

That would make the assumption of a short-lived inflation shock increasingly difficult to defend.

The depletion of global inventories is perhaps the biggest warning sign.

Stockpiles normally provide a cushion against geopolitical disruptions. That cushion has now been significantly weakened.

As a result, another major refinery outage, shipping disruption or escalation in the Middle East could produce a much larger price response than it would have before the war.

The world therefore faces a dangerous mismatch: crude supplies may recover faster than the infrastructure needed to turn them into fuel.

That is why the energy crisis could outlast the war itself.

The Iran conflict may have started as a crude oil shock, but its most consequential economic legacy could be a prolonged global shortage of refined fuels, keeping inflation and energy costs elevated long after the fighting ends.

With information from Reuters.

Source link