
Joa_Souza/iStock Unreleased via Getty Images
Joa_Souza/iStock Unreleased via Getty Images

Nes/E+ via Getty Images
Jeld-Wen Holding (JELD) and its creditors are discussing a debt transaction that could extend upcoming maturities, raise new capital and give some unsecured bondholders a stronger position in the company’s capital structure.
Under the proposal, holders of Jeld-Wen’s first-lien loan due

With high rates here to stay, CFOs rely on internal cash and working capital for stability.
In August, U.S. Treasury yields reached multi-decade highs. Treasury Secretary Scott Bessent responded by doubling the size of buyback operations for 10- to 20-year and 20- to 30-year securities to a floor of $4 billion each, effective Sept. 9 — a stopgap lasting through November 4, when the Treasury releases its next official policy statement.
Yet while Washington intervenes to stabilize government debt, finance chiefs must reckon with higher costs of capital.
“Higher rates have changed the math and, more importantly, reduced the margin for error,” Thomas DeFabrizio, CFO, Americas at Impellam Group, said in an email. “The hurdle rate should move when the cost of capital moves. Otherwise, you are pretending the financing environment has not changed.”
This reality is forcing companies to look inward, turning operational efficiency into a primary source of funding. “Every dollar released from receivables or inventory is a dollar you do not have to borrow at today’s rate,” DeFabrizio said — a meaningful gap when investment-grade credit is yielding around 5.5% and broad high-yield debt is near 7%, with lower-rated credit running considerably higher.
“That makes working capital much more than a finance housekeeping exercise,” DeFabrizio added. “It becomes a capital-allocation decision.”
Elevated borrowing costs directly filter down into corporate balance sheets and consumer demand, sparking broader concerns over whether public and private debt issuance has reached a tipping point. Rather than waiting for a rate relief cycle that may never materialize, finance leaders are taking direct defensive action.
Duncan Young, principal at San Francisco-based consulting firm Saorsa Growth Partners, specializes in providing fractional CFO services to companies. Businesses, he told Global Finance via email, are now prioritizing balance sheet durability over aggressive expansion.
To hedge against benchmark rate risks, companies are restructuring their short-term obligations and shifting benchmark exposure.

“This is likely a function of risk-off bondholders and bank balance sheets, shifting away from Treasuries towards corporates. We’re pricing off SOFR when possible, to avoid the Treasury rate risk,” he said.
Instead of speculating on interest rate cuts, companies with near-term debt maturities are moving quickly to lock in fixed terms to insulate themselves from further upside volatility in yields.
“Our ‘current debt’ revolvers are being paid back [or] termed out to give us more resilience, heading into uncertainty. We aren’t expecting yields to ease,” Young said.
That posture is showing up across the broader CFO community.
Middle-market companies, firms that typically generate less than $1 billion in annual revenue, have even less room to maneuver. Nick Araco, CEO of CFO Alliance, hears that many CFOs “are stretched thinner on what their current options are.”
As a result, they’re watching the Federal Reserve more closely, he added. “They don’t have the same flexibility to just refinance on their own timeline.”
“The ones sitting on debt maturing in the next 12 to 24 months are largely not betting on yields easing meaningfully,” Araco said, describing conversations across the group’s roughly 9,000 members.
This conservative stance is fundamentally altering capital allocation strategies. Rather than relying on leverage to fuel aggressive top-line targets, firms are relying on internal cash generation. They’re scaling back capital expenditures and holding cash as a strategic buffer.
“Return on cash gives us some benefit — for example, it softens the opportunity cost of us paying off debt. Terming out on a fixed rate and sitting on the cash so we can stay liquid in the next liquidity crisis is insurance worth paying,” Young added. “Given the AI outlook and the consequences of a bubble pop, we’re prioritizing resilience over growth rate, and this means less leverage and a more liquid balance sheet.”
Government debt continues to test the limits of market capacity. An August 30-year Treasury auction drew below-average demand and record dealer absorption as yields hit 5.2% — the highest since 2001. Meanwhile, foreign investors’ share of U.S. debt has slid to about 30% from a 2008 peak of 49%, according to the Committee for a Responsible Federal Budget and the Bipartisan Policy Center.
That combination — elevated base yields sitting alongside historically tight credit spreads — is unsettling CFOs more than the headline numbers suggest.
“Tight spreads feel almost like a false sense of calm,” Araco said. CFOs aren’t treating today’s all-in cost of debt as the new normal, he added. They’re stress-testing what happens if spreads normalize on top of already-elevated base rates.
“It’s less about action today and more about scenario planning,” Araco said, “and making sure that their capital structure isn’t fragile if that spread compression reverses.”
Corporate leaders are taking matters into their own hands. By prioritizing liquidity, extending duration, and managing leverage, CFOs are ensuring their organizations remain resilient regardless of where government bond yields head next.
“If Treasury yields remain elevated and spreads widen at the same time, the all-in borrowing cost can change quickly. I would model that combined shock now,” DeFabrizio warns. “Once you need the capital, your negotiating position has already changed.”
Anthony Noto covers corporate finance and private credit. Contact him at anoto@gfmag.com
Rising bond yields are lifting borrowing costs for governments, businesses and households across the global economy.
For more than a decade, governments got used to cheap borrowing. That era may now be ending.
Government bond markets are flashing warnings around the world.
Across major economies, yields – the interest rates governments pay to borrow – are climbing to levels not seen in years and, in some cases, decades.
Investors are pricing in more risk before they’ll lend to governments already carrying heavy debt loads.
Inflation remains stubborn, geopolitical tensions are adding pressure, and central banks may have to keep interest rates higher for longer.
Those higher borrowing costs are pushing up what banks charge companies and homeowners.
Published On 9 Sep 20269 Sep 2026
Share
European CFOs must adjust as the region’s biggest pension buyer of long-dated debt cuts back.
This article appears in the September 2026 issue of Global Finance Magazine.
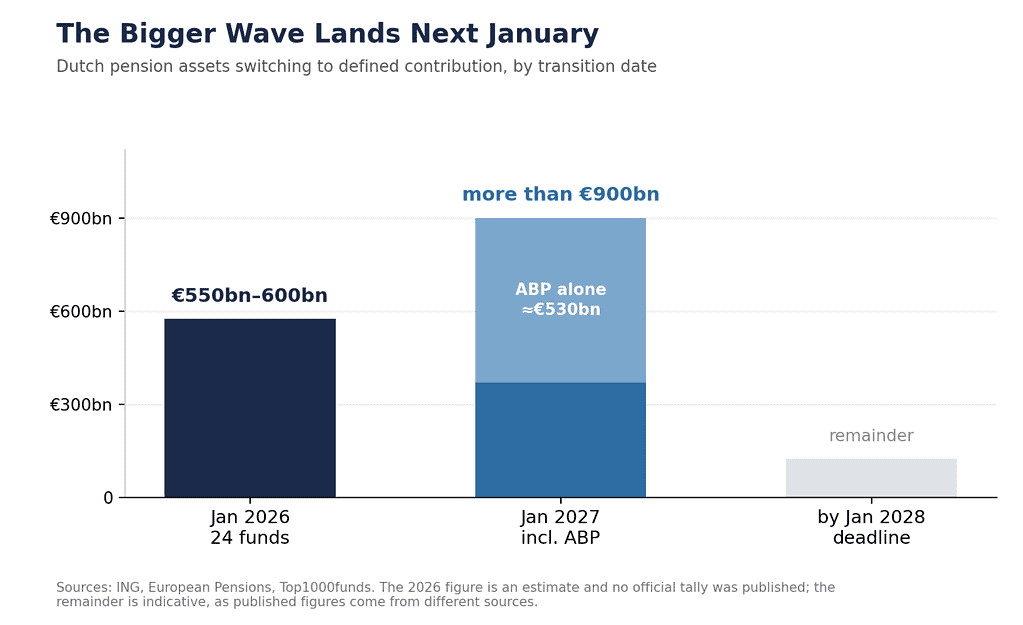
The Netherlands pension system is beginning to reduce one of Europe’s most reliable sources of demand for long-dated debt as a broad regulatory shift changes how Dutch pension funds manage their assets and liabilities. ING Groep NV estimates that nearly €600 billion ($699 billion) of assets have already been affected by the change, with more than €900 billion expected to follow early next year.
Under the old defined-benefit pension system, Dutch funds were required to hedge the interest-rate sensitivity of long-term pension liabilities by using long-dated bonds and swaps to match assets with payments extending decades into the future. Under the new defined-contribution model, which became law in 2023, that liability matching requirement has been significantly reduced, allowing funds to carry less duration and scale back their long-term hedges, resulting in less structural demand for the longest-dated debt and swaps.
For European CFOs, this could mean a higher premium for 20-, 30- and 50-year borrowing as companies and governments compete for a smaller pool of long-duration investors.
The change “should reduce structural demand for long-end duration assets and support curve steepeners over the long-term horizon,” wrote Sara Adjir, senior vice president and portfolio manager, and Jeroen van Bezooijen, account manager, at Pacific Investment Management Co., in a research note. They expect the impact will be mostly concentrated in 50-year swaps, but will also be felt in the demand for 20- and 30-year euro swaps and government bonds, including German and Dutch debt.
The Netherlands runs Europe’s largest pension system, with roughly €1.6 trillion in assets, and every fund must complete the switch by January 2028. Dutch pensions have long dominated the market for European long-dated debt, holding around €88 billion of interest-rate swaps maturing beyond 25 years at the end of last year, roughly a quarter of the total.
The first major wave of the transition came on Jan. 1, when 24 funds converted, among them the healthcare scheme PFZW and the metals scheme PMT, with an estimated €550 billion to €600 billion of pension assets between them. Analysis by the Netherlands central bank shows that Dutch pensions bought almost €34 billion net of swaps maturing inside 25 years while selling more than €12 billion of longer-dated ones.

The bigger test, however, comes when more than €900 billion of pension assets is scheduled to convert on Jan. 1, with the Dutch civil service scheme ABP accounting for about €530 billion of that.
The shift does not mean long-dated Dutch debt is suddenly becoming illiquid or even hard to sell: “Overall, we still see strong demand for our 30-year bond. Remember, we are AAA,” said Saskia van Dun, director of the Dutch State Treasury Agency.
Data indicates that sovereign borrowers are already adjusting to the change.
The share of Netherlands government bonds sold at maturities beyond 10 years fell from 42% at the start of 2025 to 31% by the third quarter, according to the Organization for Economic Co-operation and Development (OECD), which calls the constraint on long tenors structural. The OECD expects eurozone debt agencies to sell a record €1.35 trillion of medium- and long-term bonds this year into that thinner pool of demand.
For European finance chiefs, however, times are changing. For two decades, long-dated bond demand was unusually deep and predictable. As it recedes, the shifting cost of locking in 20 or 30 years of funding could become a live question.
Thomas Monteiro is a contributing writer based in Spain.
07:29, 07 Sep 2026
A mum has blasted the “ridiculous” £170 airport parking fine she received after a five-minute drop-off led to the threat of court. Josie Eccles had travelled to the airport with her husband, 33, to catch a flight to Malta with her mum and three-year-old son.
The 32-year-old claims her husband pulled into the drop-off zone at around 2pm, unloaded their luggage and said goodbye before heading off. But the couple later realised they had forgotten to pay the airport’s £5 drop-off charge within the required 24-hour period.
Josie says they accepted they would have to pay a penalty and even tried checking the airport’s payment portal for the charge – but no fine appeared. “My husband was there for under five minutes,” said Josie, a marketing consultant from Cheshire.
“A couple of days later, I was still in Malta and was speaking to my husband on the phone and asked if he had remembered to pay the charge. I was frustrated that both of us had forgotten to pay within the allocated window, but aware that these things happen and just accepted we would probably have a penalty to pay.
“My husband then checked the payment portal on the website where you usually pay the charge and entered the vehicle details, expecting to see a penalty fine, but nothing was there. I tried again a few days later, and still no charge appeared, so we thought we’d just wait and see if we got a letter in the post.”
But it wasn’t until almost two months later that Josie says she opened a letter from a debt collection firm. The letter claimed she had ignored previous correspondence and said the charge had risen to £170. Josie was given the option of paying the £170 in full or £42.50 over four months, while the letter warned the amount could increase further and potentially lead to court action.
She says she was stunned because she had never received the original parking charge notice. Josie said: “I was very confused, as it had been two months since the airport drop-off and I had received no correspondence at all so to receive a letter from a debt recovery company seemed rather extreme. At this point, I thought it must be a misunderstanding, and I would be able to resolve the issue by speaking with them.”
Josie claims she immediately tried to appeal the charge through Manchester Airport’s car parking operator, APCOA. But she says she received an automated response telling her that she had missed the appeal window and that the matter had already been passed to debt collectors.
She then called the debt recovery firm to explain what had happened. According to Josie, they told her that Manchester Airport had evidence that a letter had been sent to her on June 5. But when she asked whether it had been sent by tracked or recorded delivery, she was allegedly told it hadn’t.
Josie says this left her in an impossible position because the original letter contained the information she needed to pay the penalty. She said: “Not at any point did I try to get out of paying anything. I just wanted the opportunity to pay the initial fine, which would have been £60 if paid within 14 days.
“The only way I would know how to pay the penalty fine was by reading the instructions sent in the letter, so without the letter I had no chance of ever paying the charge before it was handed over to debt recovery. He said my options were to either pay the fine in full, which is £170, or I could seek independent legal advice and email in a dispute that they would look into it.”
In the meantime, Josie says she received two further letters threatening potential court action and warning that the amount could rise to up to £235. Josie claims she contacted the debt firm again and says a member of staff confirmed that her emails had been received but told her the company would not investigate disputes.
She says she was told her choices were to pay £170 or go to court, where the charge could potentially rise. She alleges she was then told that Manchester Airport would be responsible for taking any court action. Josie said: “I completed an online enquiry for Manchester Airport explaining I wanted to pay the £60 fine, detailed my communication with the debt company and reattached the dispute I had submitted to them with all the legal grounds.
“Within 10 seconds of submitting, I had received an AI response stating this had been handed over to debt recovery and I should liaise directly with them. I then forwarded that response along with my online enquiry submission to the complaints department, saying that was not an adequate response and I would like somebody to review the case so I can resolve this and pay the £60 fine.
“I have still not had any response or acknowledgement.”
Josie insists that she accepts responsibility for forgetting to pay the original £5 charge on 30 May but she believes the escalation is unfair because she claims she was never given the opportunity to respond to the original penalty.
She said: “I’m extremely frustrated. I hold my hands up; we forgot to pay the standard £5 charge within the next 24 hours, so a fine was expected, but to increase it to up to £235 was ridiculous. If I had been ignoring communication, it would maybe be justified, but I have responded to every bit of communication I have received, which surely shows I would have responded had I received the initial letter.
“I can afford to pay the fine; it’s not about financial difficulty. It’s about the principle of the system being set up to catch you out and the lack of reason they have. If the letter is so important, surely it would be sent tracked?
“Or at least they would try a few attempts before sending it over to debt collectors.”
She believes airports should introduce a free grace period for motorists who are only at the terminal for a few minutes. Josie added: “I’ve used Manchester Airport many times both before and after this encounter and always paid the drop-off charge on time.
“They’ll have a record of this on their system, which validates the fact I did not intentionally avoid paying. Sometimes people forget and these things happen. Other passengers could easily make the same mistake.
“It’s very easy to forget. There’s no option to pay at a machine or barrier while you’re there, so they are relying on people remembering to pay later on, which, whether you’re the person travelling through the airport or the person doing the drop-off, it’s easy to get distracted.
“I’m sure that’s why they removed the barriers, as they knew it would catch people out. The cars are logged using ANPR on their registration plates, so surely you should be able to pay on the same payment system even if outside the 24-hour window, with an additional penalty charge added.
“I think it’s ridiculous airports charge you for drop-off and pick-up. I think under 10 minutes should be free, but unfortunately all airports in the UK at least charge these days.”
An APCOA spokesperson said: “We have been in contact with the customer and offered the original charge of £60. The customer has since made payment of the £60, and the matter is now resolved.”
Manchester Airport has been contacted for comment.

The Pound is slipping(Image: Cristian Blázquez Martínez via Getty Images)
Experts have urged Brits to buy holiday cash now as the Pound is expected to weaken over this week’s market chaos with a warning that “it’ll hit wallets immediately”. Bond yields have risen sharply, increasing the cost of government borrowing and renewing concerns about whether Britain’s growing public-debt burden is sustainable.
Although higher yields can sometimes support a currency by offering investors better returns, Sterling has weakened as markets focus instead on inflation, rising debt costs and the Government’s limited financial room ahead of the Budget. The Bank of England is expected to hold interest rates at 3.75% this month, leaving it caught between supporting economic growth and preventing higher energy and import costs from fuelling another wave of inflation.
For households, a weaker Pound could mean more expensive holidays, fuel, food and other imported goods. Rising gilt yields can also push up swap rates, placing further pressure on fixed mortgage pricing just as many borrowers prepare to refinance.
Dave Huggett, founder of Lucid Foreign Exchange, said there was no need to be patient when buying your holiday cash.
He added: “Higher gilt yields and worries about debt sustainability tend to weigh on the Pound. Not always straight away and not always by much, but it’s one more thing dragging on sentiment. When investors get nervous about a country’s finances, they usually want more reward to hold that currency, or they just move their money elsewhere.
“So what do you do? Buy it all now, or hold in the hope of a recovery. The answer to that always lies in the need, not the want. If you’re buying currency to go on holiday, you basically get what you’re given. ‘Getting it right’ on a few thousand Pounds still doesn’t really move the dial. But if the numbers are bigger, and the situation can afford a bit more patience, then zooming out and looking at the situation objectively often pays.”
Iain Thompson, director of Evolve Finance, said everything was affected by a weaker Pound.
He added: “A sliding Pound is a quiet inflation tax on everyday households. When the Bank of England holds interest rates down while government borrowing costs climb, currency markets lose confidence, causing Sterling to steadily weaken against the Dollar and Euro. For the average person, this isn’t just an abstract financial chart – it’ll hit wallets immediately.
“A weaker Pound means everything the UK imports, from petrol to supermarket groceries, becomes instantly more expensive, keeping domestic inflation sticky. Holidaymakers will feel the sting the fastest at the exchange bureau. If you have a trip planned over the coming months, waiting and hoping for a sudden Sterling recovery is a high-risk gamble.
“While predicting currency is never guaranteed, the downward pressure is real. If your holiday budget is tight, locking in half of your travel cash now protects you from worst-case rate drops, ensuring a sudden currency dip won’t derail your family holiday budget before you even pack your bags.”
Tony Redondo, founder of Newquay-based Cosmos Currency Exchange, said the Bank of England was between a rock and a hard place.
He added: “Rising UK gilt yields are a double-edged sword for the Pound. At first, they boost Sterling’s appeal, a fatter carry-trade return over rival currencies. But soon markets ask why yields are climbing: borrowing costs rising as investors fret over debt sustainability, with the UK’s debt pile racing toward £3 trillion.
“That leaves the Bank of England boxed in; raise rates to choke off the inflationary wave from Brent crude above $95 or hold rates down to protect growth. My money’s on Sterling grinding lower, toward $1.30 and €1.13 ahead of the 28 October Budget, as fiscal deficits erode investor confidence.
“For consumers, a weaker Pound means pricier holidays abroad and imported inflation with higher supermarket bills, fuel costs, and goods prices. Elevated yields also lift swap rates, pushing fixed mortgage pricing higher. Anyone with confirmed overseas costs should buy currency in tranches now, hedging against further falls without gambling on timing.”
Prem Raja, head of trading floor at Currencies 4 You, said people could save as much as €230.
He added: “The rise in gilt yields is not automatically good news for Sterling. UK 10-year borrowing costs reached 5.29%, their highest since 2007, but the Pound still fell below $1.35. Investors appear more concerned about inflation, debt costs and the Government’s limited room ahead of the October Budget than attracted by higher yields.
“The Bank of England is expected to hold rates at 3.75% this month. If markets scale back expectations of a later rise, Sterling could lose another 1-2% over the coming months. GBP/EUR is around €1.16-€1.17, but €1.15 is realistic if fiscal concerns grow. GBP/USD could retest $1.33-$1.34, although US developments matter too.
“Travellers would notice that: a 2% fall means roughly €230 less when exchanging £10,000. I would not tell everyone to buy everything now, but anyone with a confirmed Euro or Dollar requirement should consider securing part of it and staggering the balance. That limits the risk of further weakness without committing everything at one rate.”
Anita Wright, chartered financial planner at Ribble Wealth Management, said a weaker Pound arrived in people’s shopping baskets within weeks, not months.
She added: “Everyone will watch the Pound against the Dollar and Euro. That’s the wrong yardstick. Those currencies are run by governments with the same problem so the Pound can look stable at the bureau de change while quietly losing purchasing power where it matters the supermarket, the petrol station, the energy bill.
“The real test of a currency is what it buys at home, and on that measure Sterling has been slipping for some time. What’s actually going on is this. The BoE holds bank rate down while the gilt market demands 5% and more. That gap gets filled by the Bank buying gilts, which is printing money by another name.
“More Pounds chasing the same goods. Diesel is already tightening and Britain imports most of its energy and much of its food, so a weaker Pound arrives in your shopping basket within weeks, not months. On holiday money swapping Pounds for Euros just moves you from one leaking boat to another.”
Samuel Mather-Holgate, managing director and IFA at Swindon-based Mather and Murray Financial, said there was no point waiting for the Pound to get stronger.
He added: “Sterling is not staring at an instant cliff edge, but the warning lights are flashing. With 10-year gilt yields around levels last seen in 2008 and the Pound slipping below $1.35, markets are telling Britain the free lunch is over. Higher borrowing costs squeeze the Treasury, unsettle mortgage markets and make imported goods, fuel and holidays more expensive if the Pound weakens further.
“For families, this is felt at the airport exchange desk, in supermarket prices and in the next remortgage quote. I would not tell people to gamble on currencies, but anyone with a known Euro or Dollar cost in the next few months may prefer certainty over trying to outguess a very twitchy market. Waiting for a stronger Pound is starting to look like a heroic assumption.”
Nouran Moustafa, practice principal and IFA at Roxton Wealth, said the weak Pound could be seen in airports.
She added: “The Pound is being squeezed from both sides. UK borrowing costs are rising, but markets still expect the Bank of England to hold Bank Rate at 3.75% this month. Sterling has already slipped to around $1.35 and €1.16. For households, this becomes painfully real at the airport.
“A weaker Pound means your hotel, meals and spending money abroad quietly become more expensive without the price tag changing. But I would not tell somebody to panic-buy thousands of Euros today based on a currency forecast. Nobody can reliably call Sterling over the next few weeks.
“If you know you need €2,000 or $3,000 for a trip, buying it in stages is far more sensible than gambling your entire holiday budget on one exchange-rate prediction. The bigger warning is this: when markets lose confidence in government finances, ordinary people eventually feel it. The bond market may look boring. Its consequences absolutely are not.”