Private credit eyeing piece of JPMorgan’s credit card portfolio: WSJ
Private credit eyeing piece of JPMorgan’s credit card portfolio: WSJ
Source link
Private credit eyeing piece of JPMorgan’s credit card portfolio: WSJ
Source link
In another push to revitalize California’s film and TV industry, Gov. Gavin Newsom on Saturday signed the state’s first standalone post-production tax incentive.
The new incentive is aimed at bringing back jobs for the industry’s editors, sound mixers, composers and visual effects artists. It will allow a 35% to 50% credit on qualified expenses related specifically to post-production work done in California, and unlike the state’s existing film and TV credit, it doesn’t require productions to shoot here.
“This legislation protects the extraordinary people who make this industry possible and makes it unmistakably clear: California is still the future of film and television,” said Gov. Newsom in a statement. “We have the talent. We have the infrastructure.”
The bill, AB 2319, was authored by Assemblymember Nick Schultz (D-Burbank) and introduced earlier this year. It cleared the state Senate 33 to 5 on Aug. 30, and the Assembly approved the final version 72 to 2 the same day. Schultz originally sought $100 million for the program. It is expected to start in January with $10 million, according to the Assemblymember Schulz’s office.
“It’s a historic moment for California’s post-production community. But it’s also just the beginning of what we really need to do to to fight for our industry,” said Marielle Abaunza, president of the California Post Alliance, a group advocating for the bill. She said the group is readying its strategy to get more funding for the program next year.
As Hollywood productions continue chase tax credits to other states and countries, much of the post-production work is going with them. California’s share of U.S. post-production employment has fallen from 53% to 42% over the last 13 years, according to CVL Economics, an economic consulting firm tied to California Post Alliance. The state had about 12,000 post-production jobs last year, per CVL Economics.
Ben Urquhart, 51, spent 18 years as a post-production executive at NBCUniversal. The Culver City resident hasn’t been able to find work in the two and a half years since he was laid off.
“It’s grim and it’s hard. There are jobs, but we have a large amount of extremely qualified people competing for every level of job,” Urquhart said. “When I was a kid, I was a [production assistant] in the 90s, and you could get a job within a couple of weeks. But when I got laid off a couple of years ago, I realized that is certainly not the case at all anymore. It’s been a large-scale transformation.”
Urquhart said the new incentive would help California compete with jurisdictions that already offer these credits and “level the playing field.”
Last year, California expanded its film and TV tax credit program, more than doubling the old $330-million cap to $750 million through June 30, 2030. The existing program already covers post-production, but only if 75% of filming or the overall budget is spent in the state.
Newsom also signed a bill that would strengthen the current tax incentive program overall. In June he revealed a state budget measure that capped how much in tax credits a business can claim each year, a limit industry groups warned would undercut the expanded program. But the new Senate Bill 186 enhances refundability for the industry and exempts independent productions from the credit limits, starting next year.
There’s also been a recent push for a federal film and TV tax incentive. President Trump has previously voiced his support for the effort, and Rep. Laura Friedman (D-Glendale) and Rep. Brian Jack (R-Ga.) are leading a bipartisan effort to draft one.
Investors, though, continue to debate the true cost of owning private credit funds.
This article appears in the September 2026 issue of Global Finance Magazine.
For the first time since the Covid-19 pandemic, private credit’s headline management fees are returning to historical norms.
According to data analytics firm Preqin’s latest fund-terms report, direct-lending funds raised in 2025 charged a mean management fee of 1.42% and a median of 1.50%, essentially matching the asset class’s long-term 2005-2025 averages of 1.43% and 1.50%, respectively.
That marks a sharp reversal from the post-pandemic doldrums, when managers cut prices to compete for a shrinking pool of investor capital amid weak fundraising and slow distributions. The median fee on direct lending funds fell to just 1%, and the mean sank to historic lows of 1.25% to 1.32%.
Now, competition for capital appears to be easing at the top of the market, while headline prices tick higher. However, beneath the headline numbers, what investors are paying is a more complicated matter.
“The headline management fee tells you very little about what investors actually pay,” said Ludovic Phalippou, a professor of financial economics at Oxford University’s Saïd Business School. “I expect the true all-in cost to be very high.”
Chad Timko, senior investment officer at the Los Angeles County Employees Retirement Association (LACERA), one of the largest U.S. public pension funds, valued at $93.9 billion, made a similar point from the practitioner’s perspective: “How a manager pays for performance can be just as important as the performance itself.”
The share of LPAs offering early-investor or large-commitment discounts also fell, from 41% of 2016-2018 vintages to 33% of 2022-2024 vintages. Source: Preqin’s Term Intelligence, data as of March 2025.
The reversal in headline fees isn’t happening evenly. Preqin’s data links it directly to performance. For funds raised between 2015 and 2019, top- and bottom-quartile managers charged nearly identical fees, averaging about 1.42%. For 2020-24 vintages, that changed; top-quartile funds held their fees near 1.42%, while fees in the lower three quartiles fell to between 1.24% and 1.29%.
Behind that split lies a market that has become sharply concentrated among a small number of managers. Two-thirds of all private-credit capital raised in 2024 went to the 20 largest funds, up from less than half in 2020, according to Preqin.
Average fund size has continued to climb for experienced managers, but first-time managers’ fund sizes have remained flat at roughly $120 million for five years. Fee discounts have followed the same pattern; the share of fund agreements offering early-investor or large-commitment discounts fell from 41% for 2016-18 vintages to 33% for the 2022-24 period, and the size of those discounts has also shrunk.
Some investors view the buildup of capital among top managers as a warning sign. Pension money pouring into private credit in recent years has “got out of hand,” loosening underwriting standards across the industry, said Mark Steed, CIO of the $25.8 billion Arizona Public Safety Personnel Retirement System. “There’s going to be a shakeout.”
Investor sentiment has grown more cautious even as realized results tick up. In Preqin’s most recent survey, 35% of institutional investors called private credit assets overvalued, up 16 percentage points year-over-year, and 37% expect performance to soften over the next 12 months, chiefly citing the path of interest rates.
Similarly, PwC’s 2026 global private credit survey identified ongoing fee competition among managers as a top concern heading into this year.
Capital concentration isn’t unique to developed private credit markets, either, though it takes a different shape elsewhere. India’s private credit market grew 35% year over year in 2025, to roughly $12.4 billion.
“Domestic funds represented over 64% of total deal value, pointing to the increasing depth of local capital,” noted Syed Hasan Jafar, vice dean of the School of Business and head of the Department of Finance at Woxsen University.
Despite the recorded uptick in fees, it remains unclear whether investor expenses are moving along with the trend.
Preqin’s figures track the headline contractual management fee rate written into a fund’s limited partnership agreement (LPA) at formation: not fund expenses, fee offsets, transaction and monitoring charges, or, in newer semi-liquid vehicles, fees calculated on NAV rather than committed capital.
“We still do not have a reliable measure of total expense ratios in private credit,” said Oxford’s Phalippou. The problem is structural, he said. “Private credit has essentially inherited the same fee model as private equity, so the transparency problems are very similar. In semi-liquid products, the situation can actually be worse because some fees are calculated based on NAV. That creates additional opportunities for gaming.”
Despite the increase in headline fees, alternative investment adviser and fund manager Cliffwater’s 2025 survey of direct lending funds found total blended costs — management fees plus incentive fees and expenses — roughly flat or lower, not higher. Proskauer’s most recent private credit survey shows that commitment and arrangement fees — a separate one-time charge — continue to fall.
Neither Cliffwater’s nor Proskauer’s findings contradict Preqin’s data; they measure different metrics. Together, they suggest that while the sticker price at the top of the market is rising, what investors pay all-in remains unclear.
Resistance to trading private assets more openly “generally means your fee is above where it’s supposed to be, and you don’t want to shine a light on it,” said Apollo Global Management chairman and CEO Marc Rowan.
Phalippou is skeptical, in any case, that investors have much power to push back, regardless of which way headline fees move.
“The uncomfortable truth is that most LPs have very little negotiating leverage,” he said. “For the vast majority of investors, these are effectively take-it-or-leave-it contracts.” The result, he adds, is that fees persist “not because they have been negotiated, but because the market structure allows them to persist.”
LACERA addresses the problem by measuring “investor profit retention,” the share of investment gains it retains after all fees, rather than fixating on the headline management fee rate, Timko said. Because its capital bears the full risk of loss, LACERA expects “to retain a super-majority of the gains generated,” with manager compensation weighted toward a performance fee that pays out only above a hard hurdle rate of cash plus a spread, rather than a flat charge on committed capital.
It is, in effect, a bet that the real fight over cost in private credit is not about the sticker price but about how gains are split once they materialize.
Thomas Monteiro is a contributing writer based in Spain.

Home  Private Credit Fed Rate Hike Squeezes an Already Stressed Private Credit Sector
Fed rate hikes threaten to further strain direct lenders as private credit default rates hit record highs.
The private credit industry keeps insisting it’s fine. The data keeps suggesting otherwise, and Wednesday’s interest rate hike from the Federal Reserve isn’t going to help the argument.
The Federal Open Market Committee officially raised the federal funds target range by 25 basis points to 3.75%-4.00%. The decision, which was unanimous among the 12 board members, marks the first rate hike since 2023.
“Whenever the Fed increases rates, the pressure on the liability side becomes very high,” David Yahalomi, chief operating officer and co-founder of Tel Aviv-based loan-management platform Hypercore, said in an email.
Companies that borrow through direct lending typically carry floating-rate debt, meaning their interest costs rise automatically whenever the U.S. central bank moves rates. The hike officially pushes up borrowing expenses at a moment when defaults are already climbing to levels not seen before.
“In the event of a prime rate increase, this structure shrinks [private credit portfolio company] margins,” Yahalomi added. And the squeeze is already showing up in the numbers.
A Fitch Ratings report from Monday shows that the U.S. Private Credit Default Rate, or PCDR, hit 6.3% for the 12 months ended in August. That’s up from 6.1% in July. The rate has now held at or above 6.0% since April. Here’s the credit rating agency’s breakdown of the findings:
While the overall PCDR blends middle-market CLO ratings (MCO) and insurer-monitored private ratings (PMR), August’s rise was driven by record stress in MCOs (5.6%), even as PMR rates eased slightly to an elevated 8.5%.

Harvey Tian, head of loan operations at Suntera Fund Services, said a size-weighted view changes how PIK interest should be read as well.
“Once the prime rate goes up, the terms on all the rates will increase, and it will definitely put pressure on the borrower side — the ones paying cash interest,” Tian told Global Finance on a call.
Loans structured with PIK options, however, aren’t paying cash interest at all, he noted. That insulates that particular pool of borrowers from a higher interest rate.
“I don’t see a huge effect on the underlying portfolio of PIK borrowers if it’s a one-time hike,” Tian said of Wednesday’s Fed announcement. A quarter-point increase would phase into the PIK rate structure over time rather than land all at once.
Multiple hikes are a different story, given the inflationary pressures caused by a worsening U.S.-Iran conflict.
Anthony Noto covers corporate finance and private credit. Contact him at anoto@gfmag.com.
A federal film and television tax credit could boost U.S. production spending by $125 billion and add more than 143,000 jobs by 2035, according to a new study commissioned by the Motion Picture Assn.
The analysis, released Tuesday morning, is expected to bolster Hollywood’s push for a federal production incentive, which the industry says is necessary to compete with the generous credits offered abroad. Sixty-five nations now offer them, the study said.
The effort has been quietly building for more than a year. It got a major boost last month when President Trump posted on Truth Social backing a proposed credit.
Details are still being worked out,, but the study assumed a transferable credit with a minimum rate of 20% on qualified spending for U.S. resident labor — broadly what industry groups have supported. It also assumed add-ons of 5% for independent production companies and 5% for labor costs in areas the Federal Emergency Management Agency has declared disasters.
If the incentive took effect Jan. 1, 2027, U.S. production spending would reach $277.5 billion through 2035, the study said, compared with $152.2 billion without it.
A coalition that includes the Motion Picture Assn., industry unions, producers’ groups and small production businesses, along with Democratic and Republican lawmakers, is expected to press the case at a virtual news conference Tuesday.
“A federal incentive would be a gamechanger for our industry,” Charles Rivkin, chairman and chief executive of the Motion Picture Assn., said in a statement. “This study tells us that we can bring more opportunities to life for people in all 50 states who bring great stories to life.”
Hollywood’s film and TV post-production workers took their case directly to Gov. Gavin Newsom on Thursday, urging him to sign a bill that would create the state’s first standalone post-production tax incentive.
Workers such as editors, singers and sound supervisors joined bill author Assemblymember Nick Schultz (D-Burbank) and Mayor Karen Bass at a news conference Thursday morning in front of the Television Academy’s headquarters in North Hollywood.
The bill, AB 2319, is aimed at supporting the industry’s editors, sound mixers, composers and visual effects artists. It passed the state Senate 33 to 5 on Aug. 30, and the Assembly approved the final version 72 to 2 the same day. Newsom, who has not taken a public position on the measure, has until Sept. 30 to sign or veto it.
Bass urged supporters not to let up before then.
“We need our industry in full force,” Bass said. “It’s all a part of making our city more affordable. We know that this is one of the biggest issues in our city, and so having a strong, robust industry helps Angelenos across the board.”
The incentive would allow a 35% to 50% credit on qualified expenses relating specifically to post-production in California. The state’s existing film and TV tax credit program already covers post-production, but only if 75% of filming or the overall budget is spent in the state. The new credit doesn’t require productions to shoot in California.
Even if Newsom signs the bill, the program would start small. Schultz initially proposed $100 million to fund the effort, but the Legislature’s end-of-session budget sets aside $10 million to launch it.
“When you think about production, it’s easy to think about the actors, the directors and the writers; you don’t think about all that happens when the camera stops rolling,” Schultz said. “What’s changed is that they’re now telling their story about the struggles they’re facing.”
For industry veteran Karen Baker Landers, the decline in local post-production work is impossible to overlook. A two-time Oscar-winning supervising sound editor, Baker Landers is vice president of California Post Alliance, the group sponsoring the bill.
“It’s affecting people in huge ways, like losing their health insurance. I get people calling me asking to get just two weeks of work to qualify for coverage,” said Baker Landers. “It’s really difficult.”
Last year, California expanded its film and TV tax credit program, more than doubling the old $330-million cap to $750 million through June 30, 2030. But a state budget measure Newsom signed in June capped how much in tax credits a business can claim each year, a limit industry groups warned would undercut the expanded program. Lawmakers passed a fix on the final day of the legislative session and it is also awaiting the governor’s signature.
Despite the state’s bigger bet on the industry — and this summer’s fight over the cap — L.A. City Councilmember Adrin Nazarian, whose district includes North Hollywood, argued at the press conference that this is the right moment to keep asking for more.
“It’s that exact momentum that we need. When you double down on something, you’re giving more than hope, and you’re saying welcome back. Please come and do your work. Don’t stop doing this,” Nazarian said.
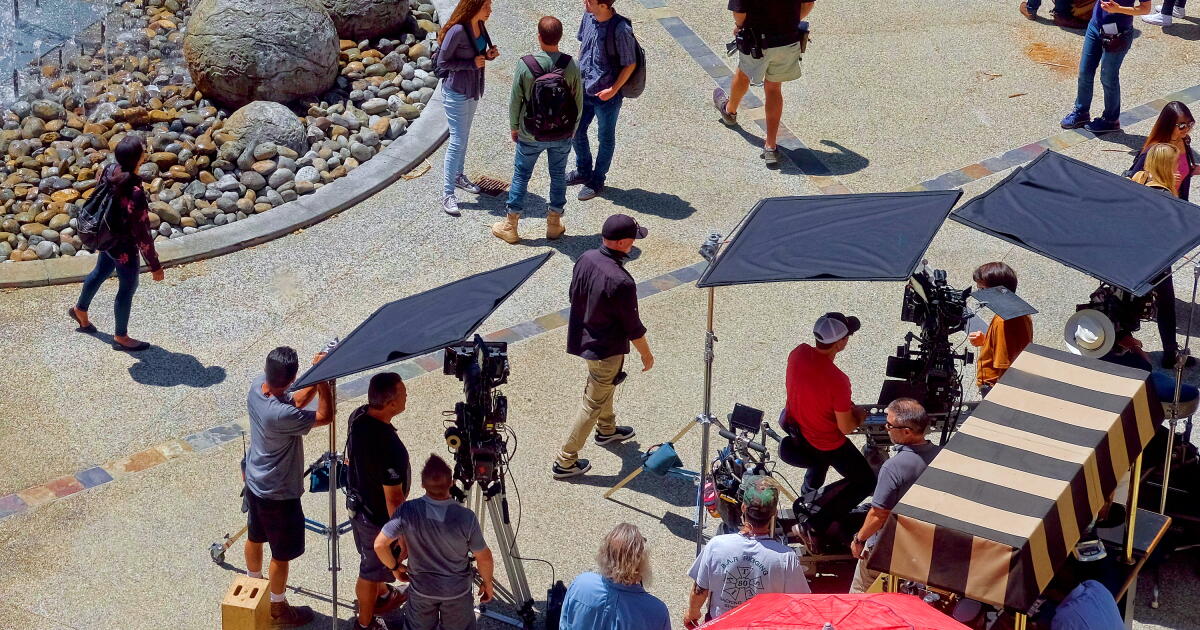
For years, Hollywood has talked about a federal film and television tax credit that could help the industry combat the growing number of productions fleeing overseas.
This week, the entertainment business got a glimmer of hope.
After more than a year of quiet work from California lawmakers, industry lobbyists and Hollywood unions to build a bipartisan coalition, President Trump endorsed the effort in a post on Truth Social, providing a major boost to the issue.
If passed, a federal incentive is expected to help draw some productions back to the Golden State, industry experts and advocates said. While it probably won’t immediately end Southern California’s production crisis — as many states now have established film hubs stocked with experienced crews and more generous tax breaks — an added federal credit could certainly help make California more competitive, they said.
“I will put our crews and our talent against any talent anywhere in the world,” said Rep. Laura Friedman (D-Glendale), a former producer who has been pushing for a national film tax credit. “If we have a level playing field upon which to shoot, where we are not much more expensive than other locations, productions will come back to Los Angeles.”
Trump’s Truth Social post came after a meeting with actor Jon Voight, one of the president’s designated Hollywood ambassadors who has played a key role in lobbying for the film industry and advocating for a federal tax credit. Though Trump has had frosty relations with Hollywood, particularly since many heavyweights did not support his presidential campaign, the industry’s jobs push aligns with his focus on re-shoring work, marking a rare moment of agreement.
Speaking to reporters in the Oval Office, Trump said Wednesday that he has done “a lot of work” in the last week to get something done on federal tax incentives for the film and television industry.
Trump said he has spoken to streaming giant Netflix; Ari Emanuel, chief executive of TKO Group Holdings Inc.; and “many others,” and that he is hopeful there will be a bipartisan push to revive productions in Hollywood with “big subsidies and big credits.”
“We don’t give anything and we should,” Trump said, referring to proposed tax breaks for U.S. productions. He added that he wants legislation to “match” what other countries are offering.
Now, lawmakers must hammer out the details of that legislation.
The bill will have a Republican sponsor from a state known for film and TV production, but Friedman declined to name the person, saying she was waiting for Republicans to make their internal decision about that lead lawmaker.
The bill is likely to go through the House Committee on Ways and Means. While exact provisions are still being negotiated, the expectation is that the credit will be stackable with states’ incentives — similar to how Canada’s tax credit works. A 20% federal tax credit on all labor costs — including for salaries of actors and crew members — is being discussed.
An earlier proposal from Sen. Adam Schiff (D-Calif.) had called for a baseline labor-based tax credit of 15% to 20%, in addition to bonus add-ons for indie productions among others, a Schiff spokesperson said.
Schiff has previously noted that 45% of all U.S. films and scripted TV shows were shot internationally last year, up from about 33% in 2022.
Having Schiff and Trump on the same side of this national tax credit is emblematic of the odd bedfellows the effort has gathered.
The Motion Picture Assn. studio lobbying group has released a statement backing the proposal, as have unions such as the Screen Actors Guild — American Federation of Television and Radio Artists, the Directors Guild of America and the International Alliance of Theatrical Stage Employees.
“I am in strong agreement with the President,” Schiff wrote Monday in a post on X. “Congress should immediately take up and pass a federal film tax incentive to bring back these good-paying jobs that we’ve lost to other countries.”
Production incentive experts say any national film tax credit will need to have a seamless process, one with minimal red tape.
One idea is to make the national production incentive an overlay that’s attached to states’ incentives, so the federal government doesn’t need a separate agency to vet the same criteria, which could slow the process, said Peter Marshall, managing principal of media insurance services at Epic, an insurance broker and consultant.
Parameters will also need to be clear, and the program easy to access, said Kathleen Thompson, vice president of tax incentives at payroll service Cast & Crew.
“There is an excitement and an energy and a hopefulness right now from the production community,” she said. “I’ve certainly gotten notes from clients, potential clients and industry colleagues that are very excited about the possibility of this passing and becoming a reality.”
Stacking a federal tax credit on top of the newly bolstered California production incentives could help give the state an edge when producers are pricing out location shoots.
“California is still the leader in production,” said Joe Chianese, senior vice president at Entertainment Partners, which tracks production incentives worldwide. “Producers would like to stay home if they can, but it boils down to the math.”
But even with the improvements to California’s film and TV tax credits, the state’s program still has limitations.
California has an annual funding cap of $750 million, has designated application windows and does allow the cost of actors’ salaries — a major driver of movie budgets — to be counted toward the tax breaks.
Beyond the program, the Golden State is just more expensive than other U.S. locales, and some filmmakers have criticized the red tape that makes shooting in L.A. more difficult.
“Can we be more competitive with a federal incentive? Absolutely,” Thompson said. “Can it completely turn the tide? I don’t know, but I hope so for our industry and our state.”
Industry stakeholders say they are hoping for quick movement on the issue, particularly since it will probably take more than a year after any tax credit is passed for producers to start making plans to move filming back to the U.S. due to lengthy production timelines for movies and TV shows.
“There is a ticking clock,” said Marshall of Epic. “If something isn’t done by the end of the year or in sight, there will be a further solidification of offshoring.”
For Peter Max-Muller, owner of The Ruby, a North Hollywood contemporary clothing rental business, the loss of film and TV shoots in L.A. is one of many threats his business faces, in addition to the use of AI production.
His sales typically mirror the production data from the nonprofit FilmLA, which recorded a 13% drop in shoot days in L.A. County in the second quarter over the same period a year ago.
The goal of a federal incentive, Max-Muller said, “is that we get that runaway production back.”
It’s why Friedman said she is pushing to get the tax credit legislation done as soon as possible.
“The film industry is deep in the identity of Los Angeles,” she said. “And it’s worth saving.”
Staff writer Ana Ceballos contributed to this report.
Home Private Credit Private Credit Newsletter
We strive to provide essential intelligence to our international audience of senior financial executives. As part of this mission, we have launched the new Private Credit newsletter and have expanded our coverage of Private Credit sector in our print and digital editions.
The Hidden Risks of Payment-in-Kind
BlackRock’s CEO Exit Signals Private Credit Shift
Private Credit Stress Test: What Breaks And What Holds
New Frontier In The Gulf
STAY AHEAD IN PRIVATE CREDIT
Subscribe for our monthly newsletter today.
