

Strattec expects 15%-16% gross margin in fiscal 2027 while targeting $40M operating cash flow (NASDAQ:STRT)
Earnings Call Insights: Strattec Security Corporation (STRT) Q1 fiscal 2027
Management View
-
“Our first quarter results reflect continued progress in transforming Strattec into a more resilient, higher-performing business.” (CEO, President & Director Jennifer Slater)
-
“We generated $10.8 million in cash from
Seeking Alpha’s Disclaimer: This article was automatically generated by an AI tool based on content available on the Seeking Alpha website, and has not been curated or reviewed by humans. Due to inherent limitations in using AI-based tools, the accuracy, completeness, or timeliness of such articles cannot be guaranteed. This article is intended for informational purposes only. Seeking Alpha does not take account of your objectives or your financial situation and does not offer any personalized investment advice. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank.
TotalEnergies signals 2026 cash flow above $42B and authorizes $2.5B quarterly buybacks into Q1 2027 (NYSE:TTE)
Earnings Call Insights: TotalEnergies (TTE) Q3 2026
Management View
-
“TotalEnergies has demonstrated once again, in this quarter, its capacity to achieve an outstanding operational performance and to deliver a very strong set of results and cash flow, clearly reflecting the ability of the
Seeking Alpha’s Disclaimer: This article was automatically generated by an AI tool based on content available on the Seeking Alpha website, and has not been curated or reviewed by humans. Due to inherent limitations in using AI-based tools, the accuracy, completeness, or timeliness of such articles cannot be guaranteed. This article is intended for informational purposes only. Seeking Alpha does not take account of your objectives or your financial situation and does not offer any personalized investment advice. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank.
DBV expects cash runway into Q3 2027 as it advances sequential FDA reviews for VIASKIN Peanut BLAs
DBV expects cash runway into Q3 2027 as it advances sequential FDA reviews for VIASKIN Peanut BLAs
Source link
California Prop. 37: $25 billion down payment assistance explained
Buying a home in California requires a colossal amount of money — and coming up with a 20% cash down payment of $180,000 for a median price home is a staggering hurdle for many would-be buyers.
That down payment amount is based on the statewide median $900,000 price tag for a house, according to recent data from the California Assn. of Realtors. In Los Angeles County, the median price for a single-family home is $935,000. In Orange County, it’s $1.5 million.
Proposition 37 on the Nov. 3 ballot would allow the state to amass a $25 billion down payment assistance program for middle-class households. For perspective on the enormity of the measure before voters, one of the state’s existing down payment programs, California Dream For All, launched several years ago with $500 million, just 2% of the funding involved in Proposition 37.
The ballot measure would allow qualified prospective homebuyers to borrow up to 17% of the sales price of a new home, contributing 3% of the down payment from their own funds.
The program would not be funded by taxpayers, but instead by the interest charged to borrowers on their down payment loans, also referred to as second mortgages. The measure has garnered widespread support, including from Gov. Gavin Newsom, statewide unions and mayors from Santa Monica to San José.
“Prop. 37 is a historic opportunity to expand homeownership opportunities for generations of working families — at zero cost or risk to taxpayers,” Newsom said in a statement.
But Proposition 37 carries a significant caveat: Any home purchased through the program must be new construction, which could limit its potential reach because of the high cost of building, some critics said.
Also, the proposition does not spell out the terms or interest rates on the loans, which would be worked out if the measure is approved. And some have questioned whether there will be sufficiently robust interest from investors to buy the state-issued bonds that will be used to fund the down payment loans.
The concept of down payment assistance is not new. Cities and states, including California, have long offered such programs to low- and middle-income homeowners, either in the form of loans or grants, and there are reportedly more than 2,700 such programs across the country.
Nevada, Connecticut, Massachusetts and New York all have programs to help homebuyers afford a down payment. Since 2021, New York has dispersed $70 million in down payment assistance. In Massachusetts, more than $146 million has been doled out in down payment help to homebuyers since 2020.
How the program would work
Under Proposition 37, down payment loans would work like any other, and would carry an interest rate and payback period — all of which would be determined by the California Housing Finance Agency.
To qualify, borrowers would need to have lived in the state for at least a year and earn no more than 200% of the local median income; in Los Angeles County, for example, that equates to a family of four earning no more than $216,200 a year.
Borrowers don’t have to be first-time homebuyers, which is often a requirement of down payment aid programs. But they would need to live in the home.
The program would restrict the price of qualifying homes, depending on the county where someone is trying to buy. A general estimate, though, is that would-be homebuyers would be limited to houses costing between $1 million and $1.5 million and the homes, more importantly, would need to be new construction.
While Proposition 37 has little opposition, and is supported by unions, chambers of commerce and organizations representing builders, the League of Women Voters opposes the ballot measure, concerned it would saddle residents with too much debt and that the terms of these loans are opaque, the details worked out only after the vote.
New homes only
Only buyers of newly-built homes would be eligible for these loans. That could include existing commercial buildings that had been converted into homes, such as condos or townhomes.
This provision is uncommon as many existing down payment assistance programs don’t strictly limit the type of home someone can buy — only the sale price. Bob Hertzberg, former Senate Majority Leader and the architect of the proposal, said he wanted Proposition 37 to spur new construction.
“The problem is we have to increase supply,” Hertzberg said. The shortage of homes in the state is estimated to range anywhere from 840,000 to upwards of 3 million.
By creating more demand for new homes, he said, the hope is that builders will respond en masse.
But some groups are wary of this logic. One analysis, funded by the Proposition 37 campaign, estimated that this program could result in the building of 190,000 homes in the state, although the report’s author said it was “impossible to know” the true number given the various factors that impact housing.
Matthew Lewis, director of communications for California YIMBY, an organization that advocates making it easier and cheaper to build homes, said high prices make it clear that the demand for homes already exists and that Proposition 37 does little to address a bigger issue: the cost of building.
“In concept, [Proposition 37 is] a great idea,” Lewis said. “The thing we’re concerned about is, California is still way behind on its housing production goals, so there’s the risk of an unintended consequence of instead of having 10 people bidding on a house, now you’ve given a couple folks down payment assistance, and so there’s now 12 people bidding on the same house.”
To drive builders to construct eligible homes, the measure would allow them to opt into a “qualified builder” option. As long as they adhere to price caps, agree to certain labor requirements and fix repairs that arise, they’re protected from lawsuits from buyers concerning defects 10 years after construction of the home.
Homebuilders say even given some relief from litigation, they aren’t sure Proposition 37 would push construction into overdrive.
“There are so many more things the state, city and county could do to help add more supply [of homes],” said Paul Schon, a developer who builds apartments in L.A. County. He said tackling permitting times and red tape involved in building would have a greater impact. “This is minor,” he said.
Interest rates could be a tough sell
Many down payment assistance programs offer interest-free loans to homebuyers, including an existing program run by CalHFA.
But in order to be self-funding, the fixed-rate loans offered through Proposition 37 would carry interest. If passed, the state would issue revenue bonds, selling them to investors and using that money to issue loans to homebuyers. The investors are repaid with the interest paid on the loans.
According to the Legislative Analyst’s Office, CalHFA would decide the total amount of bonds to issue and over what period of time.
Revenue bonds are generally viewed as riskier than other types of government bonds, in part because they’re backed by the promise of revenue from a specific project — in this case, payment by individual borrowers. That means interest rates on these loans could be higher than borrowers might like or be able to afford.
Hertzberg said he’s talked to investors who may be willing to buy these bonds at cheaper rates, given the crushing issue the funding is trying to solve. This would keep interest rates down for borrowers. He said he’s appealing to foundations and socially-minded tech leaders.
One of the biggest financial backers of the measure is the political nonprofit Building a Better California, which has been fighting the billionaire’s tax with help from wealthy donors, including Google co-founder Sergey Brin.
Hertzberg, for his part, refused to name any organization or person who may be interested in buying the bonds that would fund this program.
This article is part of The Times’ equity reporting initiative, funded by the James Irvine Foundation, exploring the challenges facing low-income workers and the efforts being made to address California’s economic divide.
Iraq devalues dinar to ease cash crunch, leaving traders in limbo | Business and Economy News
Baghdad, Iraq – Sitting anxiously in his small office in Jameela market, one of Baghdad’s main wholesale markets, food trader Hamza al-Rudayni is waiting to see what the coming days will bring.
A decision by the Iraqi government to devalue the country’s currency, the dinar, against the US dollar has left traders like him facing sudden losses and uncertainty over the prices they should charge for their goods.
Recommended Stories
list of 3 itemsend of list
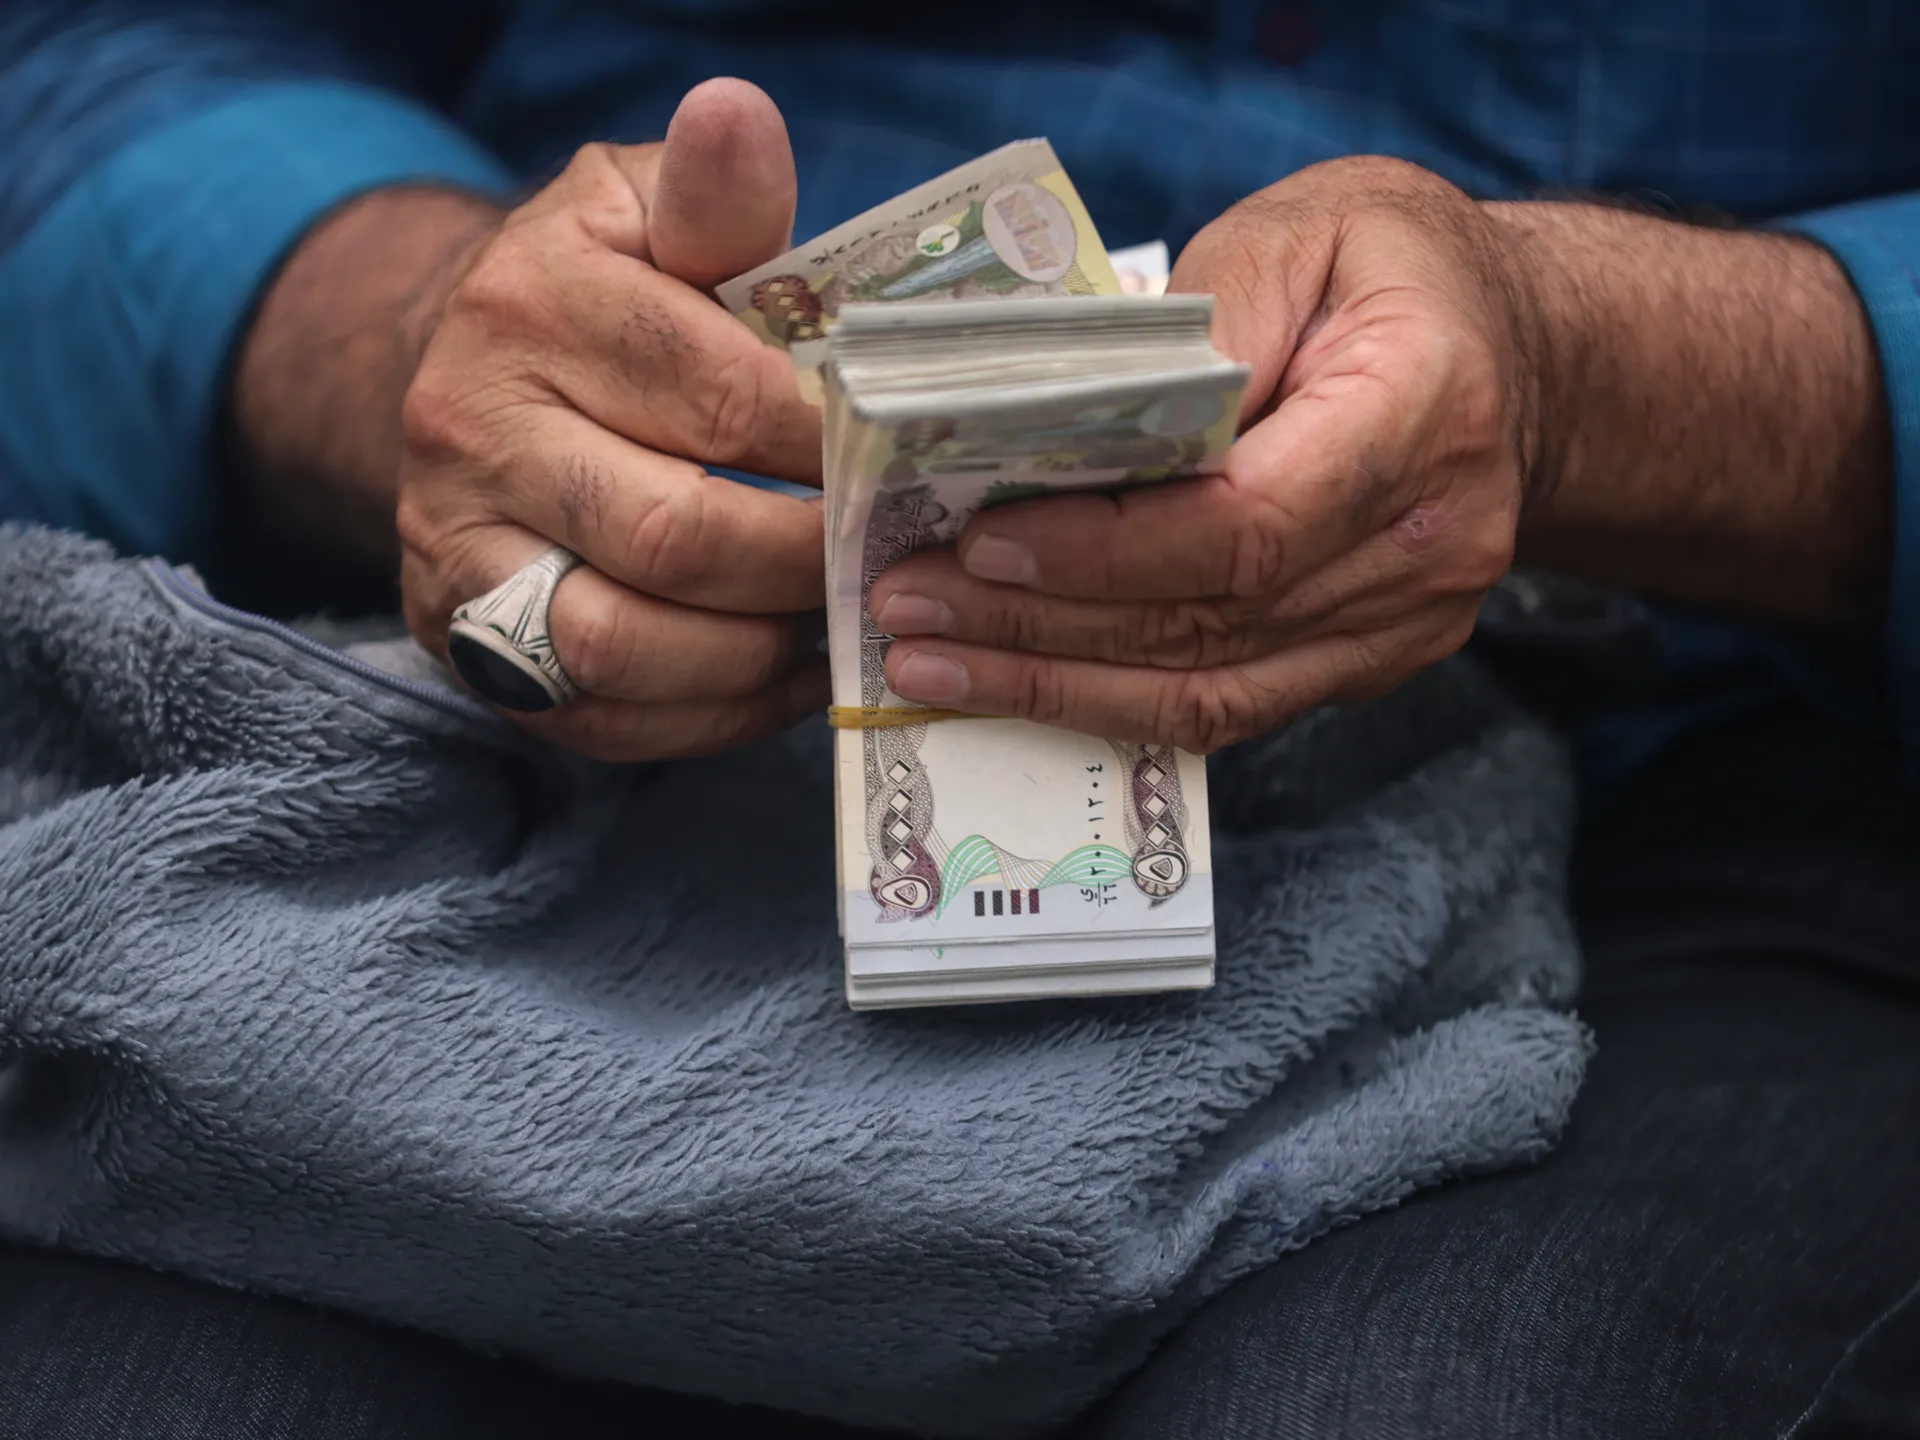
“I don’t know what to do,” al-Rudayni told Al Jazeera after the devaluation reduced the dollar value of his dinar holdings, leaving him with less money to purchase imported goods.
“All I know is I woke up a few days ago to discover that I had lost 25 million Iraqi dinars (roughly $16,500 at the new exchange rate) because of this decision, while larger merchants lost billions,” he said.
Al-Rudayni entered the wholesale trade market last year after losing his previous job at a private Iraqi bank that he says was sanctioned by the United States Treasury. He sold his car and used his savings to start trading with a larger merchant before recently launching his own business.
With exchange-rate fluctuations making prices unpredictable, al-Rudayni said he and many other traders have chosen to suspend buying and selling until the situation stabilises.
“Market activity has ground to a halt,” al-Rudayni said. “Traders buy goods in dollars but sell them in dinars, as regulations prohibit them from selling in dollars.”
That is the root of the problem for traders: A weaker dinar means they have to pay more in local currency for goods imported in dollars, while making it harder to determine the right price they should charge customers for goods they already have in stock.
Why devalue?
On October 7, the Iraqi government introduced a new official exchange rate against the US dollar, in an attempt to ease a financial crisis triggered by the US-Israeli war on Iran and the disruption of oil exports through the Strait of Hormuz.
Before the war, Iraq exported around 3.5 million barrels of oil per day through the Strait of Hormuz, accounting for 90 percent of Iraq’s government revenue.
The Central Bank of Iraq decision set the rate at 1,520 dinars per US dollar for cash sales to the public. It was previously set at 1,320 dinars per dollar.
Devaluing the Iraqi dinar by almost 15 percent against the dollar allows the government to receive more local currency for every dollar of oil revenue it converts, helping it cover public spending, including government employee salaries.
“It is my decision and I am responsible for it,” Iraqi Prime Minister Ali al-Zaidi said during a meeting with parliamentary leaders on Thursday.
“I was facing three challenging options to cover salaries and other mandatory expenditures,” al-Zaidi added. “The first is to cut salaries by 35 percent … the second is to pay the salaries every 45 days … while the third is to resort to foreign loans.”
Al-Zaidi, a former banker, also said that his government had inherited public debt exceeding 208 trillion Iraqi dinars ($139bn at the new rate) when it took office in May. He said the government needed approximately 10 trillion dinars ($6.7bn) each month to cover salaries and other essential expenditure.
A shortage of liquidity
The crisis in the Strait of Hormuz had caused a severe financial squeeze for the Iraqi government.
Although the situation has eased somewhat in recent weeks after Iraq’s oil exports partially recovered, they have yet to return to their pre-war levels.
Mudher Mohammed Salih, the Iraqi prime minister’s financial adviser, said in August that the Central Bank of Iraq’s foreign currency reserves had declined from $106bn to approximately $80bn.
To make up for the loss of revenue, the Iraqi government has also turned to borrowing from domestic banks to cover salaries and other expenses.
A Finance Ministry official told Al Jazeera that ensuring salaries were paid on time remained the government’s main priority, describing this issue as a matter of domestic economic stability.
“Our hands are tied regarding the revenue and how to maintain enough money to ensure that we can pay the salaries,” the official, who asked to remain anonymous because he was not authorised to speak publicly, said.
Economists have warned that while adjusting the exchange rate could ease some immediate fiscal pressures, it would not address the deeper weaknesses in Iraq’s economy.
“Nothing in economics is sacred, including the exchange rate,” said Nabil al-Marsoumi, professor of economics at Al Maaqal University in Basra. “It can be adjusted, but only after all other options have been exhausted.”
“In any case, the exchange rate shouldn’t be used as a cover-up for failures in the state’s economic and fiscal policies,” he added.