Banks

Standard Bank’s Rajesh Ramsundhar on Africa’s Growth in Payments and Trade

Produced in partnership with Standard Bank, this video features Rajesh Ramsundhar, Head of Investor Services & Financial Institutions, Corporate and Investment Banking at Standard Bank, speaking with Global Finance at Sibos.

Rajesh Ramsundhar, Head of Investor Services & Financial Institutions, Corporate and Investment Banking at Standard Bank, speaks with Global Finance at Sibos. Content produced in partnership with Standard Bank.

Ramsundhar explains why Standard Bank is firmly bullish on Africa’s long-term growth runway; how payments and trade sit as the bank’s core transaction banking priorities; and how its technology agenda — building on the bank’s legacy of innovation, deploying technology to enter new markets, and applying data and AI to sharpen efficiency and client service — is positioning the bank for what comes next.

Source link

Banks expect tax increase in Healey’s first Budget

Senior banking executives have told the BBC they expect the sector to be “on the menu” when the chancellor announces his Budget in two weeks’ time.

John Healey has described the banks as part of “the crown jewels” of the UK economy, yet has refused to rule out a raid on the sector.

The biggest four banks collectively made around £15bn profit in the first six months of this year, leading to calls from trade unions and others for additional taxes.

However, the banking sector trade body, UK Finance, warned that “further increases in bank taxes would weaken competitiveness, discourage investment and job creation, and work against the government’s ambition to deliver growth in every postcode”.

The UK’s biggest banks and building societies currently pay a surcharge of 3% on top of the baseline 25% rate of corporation tax, plus a levy on the assets held on their balance sheets.

The sector contributed nearly £40bn to the Treasury last year, if income tax on employees is factored in.

The bank levy generated £1.4bn last year and the surcharge a further £1.2bn.

There are a number of ways the chancellor could extract more money from the sector.

The 3% surcharge was reduced from 8% under Rishi Sunak when he was chancellor, at the same time as he raised corporation tax from 19% to 25%. Returning the surcharge to its previous level could raise around £2bn a year.

The bank levy currently charges 0.1% on outstanding short-term loans and 0.05% on longer-dated loans, although mortgages are excluded from the calculation.

In the past banks have successfully argued that higher taxes would risk making the UK uncompetitive with other jurisdictions and would reduce their ability to lend, and therefore be anti-growth.

In truth, banks were pleasantly surprised they were not hit at the last Budget, given the large profits they have been making in recent years. Rising interest rates have expanded the margin between the rate at which they lend to customers and the rate they pay savers.

There is another option that has been discussed with Treasury officials. Currently banks can use losses from the past to offset against profits – thereby reducing their tax bill in any given year. Lloyds in particular has been a beneficiary of this policy, as large losses from the financial crisis have been used to lower tax bills ever since.

Some analysts and bank executives have pushed the idea of a moratorium on this practice for a few years, which would yield an estimated extra £1bn per year for the Treasury. That would provide a windfall while being “a lot more bearable”, in the words of one bank executive.

It would also spare foreign banks from an additional hit, including JP Morgan, whose chief executive Jamie Dimon has warned that the UK already has one of the highest tax burdens on banks in the world. He warned that adding further sector-specific taxes could discourage investment and damage competitiveness.

However, industry leaders say any form of tax rise that hits UK banks and exempts foreign banks’ operations in the UK would be hard to square with the government’s push to back British business.

Whatever form it takes, banks believe the chancellor now has much more of an appetite to take a larger slice of their pie.

Source link

U.S. Banks’ Urge to Merge

This article appears in the October issue of Global Finance Magazine.

U.S. banks are merging again as a rare combination of a friendlier regulatory environment, excess capital among the bigger players, and the rising cost of competing in artificial intelligence continues to drive broad industry consolidation.

S&P Global Market Intelligence data shows that 81 banking deals were announced in the U.S. in the first half of 2026, the largest first-half tally since 2021.

The resurgence in banking mergers and acquisitions follows a regulatory shift that began in May 2025, when the Office of the Comptroller of the Currency restored expedited review and a streamlined application process for the industry’s mergers. Two months later, the Federal Deposit Insurance Corp. rescinded its 2024 policy statement on bank mergers and returned to its earlier guidelines, broadening the regulatory overhaul.

The practical effect has been a shorter path from announcement to completion: Median deal time fell from 187 days in 2024 to 134 days in 2025 and 94 days so far this year, according to S&P Global.

Bankers responded with a series of deals, including Huntington Bancshares’ acquisitions of Veritex and Cadence Bank and PNC’s purchase of FirstBank. By the fourth quarter of 2025, bank deal value had reached $26.3 billion, the highest quarterly total since early 2019.

“If you are a bank looking ahead at succession planning or at the technology investments to compete as you get bigger, there is this window within this administration,” said Catherine Mealor, a Keefe, Bruyette & Woods managing director. “If you think you might want to sell within the next three or four years, you might as well go now. You can get it closed quickly.”

According to PwC research, five banking deals worth more than $5 billion were announced in the latest four-quarter period, pushing aggregate deal value to roughly the same level as the previous four quarters despite a lower volume of transactions.

The consolidation pressure is also coming from the capital side of the equation. Recent research by Bain & Co. found that 17 U.S. lenders each held more than $10 billion in excess capital at the end of June, with seven above $20 billion.

The same research also found that deals combining scale with new capabilities delivered total shareholder returns 14 to 18 percentage points above scale-only transactions over the past two years, as banks face rising costs to build and maintain technology and artificial intelligence capabilities.

Bigger Deals Become the Norm

That appetite for scale is visible in this year’s largest transactions. Santander’s $12.2 billion acquisition of Webster Financial created a $327 billion-asset bank, while Fifth Third’s $10.9 billion purchase of Comerica produced the ninth-largest U.S. bank. Pinnacle Financial Partners’ merger with Synovus created another institution with more than $120 billion in assets.

Sellers, though, may not agree with buyers regarding a franchise’s worth. The median price paid for a bank seller is about 141% of tangible book value, according to Piper Sandler, while 68% of banks surveyed by Bank Director say they would require at least 175% to sell.

Thomas Monteiro is a contributing writer based in Spain.

The post U.S. Banks’ Urge to Merge appeared first on Global Finance Magazine.

Source link

US inflation rises before midterm elections, fuelling rate hike fears | Inflation News

Economists divided on Fed rate hike as inflation creates uncertainty in run-up to US midterm elections in a tense market.

United States consumer prices jumped in September in the final inflation report before the midterm elections, increasing chances of an interest rate hike later this month.

Annual inflation accelerated to 3.7 percent, up from 3.4 percent in August. On a monthly basis, prices rose by 0.6 percent, according to the Consumer Price Index report released by the Labor Department’s Bureau of Labor Statistics (BLS) on Wednesday.

Recommended Stories

list of 4 itemsend of list

Petrol prices led the surge as tensions between the US and Iran, as well as Russia and Ukraine, weighed on global energy prices. Petrol prices rose 9.1 percent in September, accounting for more than half of the CPI monthly increase, according to the BLS. They were up 34.2 percent from the same time a year ago.

“The directionless war in Iran continues to disrupt global supply chains, driving up the prices of food and fuel,” Kyle Moore, chief economist at The Century Foundation, an economic think tank, said in a statement provided to Al Jazeera.

Petrol prices have continued to climb. The average price for a gallon of petrol is $4.33 ($1.14 per litre), compared with $4.31 a month ago, according to the American Automobile Association (AAA), which tracks daily petrol prices. Diesel prices are higher, at $6.29 per gallon (1.66 per litre), compared with $6.23 a month ago.

In a post on X, Patrick DeHaan, head of petroleum analysis for GasBuddy, said, “2026 has now seen more days with average gas prices over $4/gal than any year before: 158 days.”

Shelter costs also jumped 0.4 percent from the previous month, following a 0.3 percent increase in August. Food costs were a bright spot in the report, remaining unchanged overall.

Food away from home, including restaurant meals, rose 0.2 percent, but that increase was offset by a 0.1 percent decline in food-at-home prices, which track grocery costs.

At the grocery store, poultry prices jumped 0.7 percent, fruit and vegetable prices rose 0.5 percent, and juice prices increased 1.1 percent. However, milk prices dropped 2.1 percent and beef prices fell 0.9 percent.

Amid heavy investment in AI infrastructure, prices for computer software and accessories have jumped 28 percent from the same time last year.

“The AI boom is playing a huge part, and we have all read about the hundreds of billions being poured into data centers, AI firms, and models,” Rami Cassis, principal of Parabellum Investment, said in comments provided to Al Jazeera.

Fed pressures

The inflation data comes days before the US Federal Reserve’s interest rate decision later this month. Last month, the US central bank raised rates by 25 basis points, bringing the target range to 3.75–4.00 percent, the first hike in three years.

Economists are divided over whether the Fed will raise rates again or hold them steady. According to CME FedWatch, which tracks the likelihood of monetary policy decisions, there is a 52.9 percent chance that rates will remain in the 3.75–4.00 percent range, while a 47.1 percent chance of a quarter of a percentage point hike that would bring them to 4.00–4.25 percent.

The inflation data puts pressure on Republicans before the midterm elections on November 3. A recent Reuters/Ipsos poll showed that about 78 percent of Americans blamed US President Donald Trump’s policies for price increases.

US markets trended downward following the inflation report. The Nasdaq fell 0.8 percent and the S&P 500 dropped 0.6 percent, while the Dow Jones Industrial Average was roughly flat in midday trading.

Source link

US fines Bank of America $1.2bn for money laundering, sanctions violations | Banks News

The second-largest US bank faces record penalties for failing to comply with sanctions and money laundering laws.

The US Treasury Department has imposed more than $1.21 billion in penalties against Bank of America, the second-largest bank in the US, for violating anti-money laundering and sanctions laws.

The fines announced on Tuesday include the third-largest penalty in the department’s history, the US Treasury said in a statement.

Recommended Stories

list of 4 itemsend of list

“When a bank of this size fails to meet its anti-money laundering and sanctions obligations, the consequences extend far beyond its own walls, exposing the entire US financial system to significant illicit finance risks,” US Treasury Secretary Scott Bessent said.

He added that these “actions send a clear message that even the biggest financial institutions are not above the law”.

Enforcement actions

According to the Treasury Department, the Financial Crimes Enforcement Network (FinCEN) assessed a $1.2 billion penalty over the bank’s failure to mitigate and report “priority national security risks, including Chinese Money Laundering Networks and illicit finance along the southwest border”.

The failures identified by FinCEN involved deficiencies related to the bank’s suspicious transaction identification and reporting and customer due diligence processes. According to the statement, “the Bank effectively outsourced to third parties a substantial portion of its proactive detection and reporting obligations”.

“Bank of America failed to timely report to FinCEN over $5 billion dollars in suspicious transactions”, the Treasury said in the statement.

The Office of the Comptroller of the Currency (OCC) assessed a $750 million fine, the largest in its history, for the bank’s deficient and ineffective anti-money laundering compliance programme. FinCEN’s $1.2 billion penalty includes credit for the OCC fine.

The Office of Foreign Assets Control (OFAC) also announced an $11.6 million settlement agreement over apparent violations of numerous sanctions programmes, including on Iran, Russia, narcotics and global terrorism.

Bank of America agreed to settle 475 apparent violations of multiple sanctions programmes, and the settlement includes “significant compliance commitments regarding training, testing and audit, and future communication and cooperation with OFAC”.

In the statement, the Treasury said the actions “underscore the importance of effectively complying” with US anti-money laundering and sanctions requirements.

In response, Bank of America said in a statement: “Financial crime compliance is serious, and we are responsible for getting it right.”

“We have invested billions of dollars in technology and dedicated thousands of employees to combat financial crime, and our team is far along with and committed to completing the work required to address the issues raised by our regulators.”

Source link

How the Banco Master scandal injected chaos into Brazil’s presidential race | Elections News

A historic collapse

One factor in the widespread disillusionment has been the Banco Master scandal. The financial imbroglio has delivered a black eye to both ends of Brazil’s political spectrum.

A range of business leaders, political figures, regulators and judges have been swept up in the scandal.

A mid-sized lender, Banco Master grew aggressively over the last decade by selling high-yield deposit certificates. Some of those certificates offered returns of up to 140 percent relative to Brazil’s benchmark interbank rate.

But Banco Master did not have the assets needed to sustain that output.

It lacked the money to pay back its risky loans, and what assets it did have were diverted to shell accounts, according to prosecutors.

Brazil’s Central Bank ultimately liquidated Banco Master in 2025, as the lender faced a major funding squeeze.

Its owner, Daniel Vorcaro, was subsequently arrested, accused of an array of financial crimes, including money laundering and fraud.

The collapse of Banco Master triggered a nearly $7.7bn payout from Brazil’s Credit Guarantee Fund, the largest disbursement in the nonprofit insurance’s history.

Investigators have suggested that Vorcaro protected his fraud scheme by cultivating influence among power brokers among Brazil’s elite.

Among those implicated in the scandal is Senator Flavio Bolsonaro, the presidential candidate.

Last month, the Supreme Court unsealed documents showing he is under investigation for alleged corruption and money laundering in connection with Vorcaro.

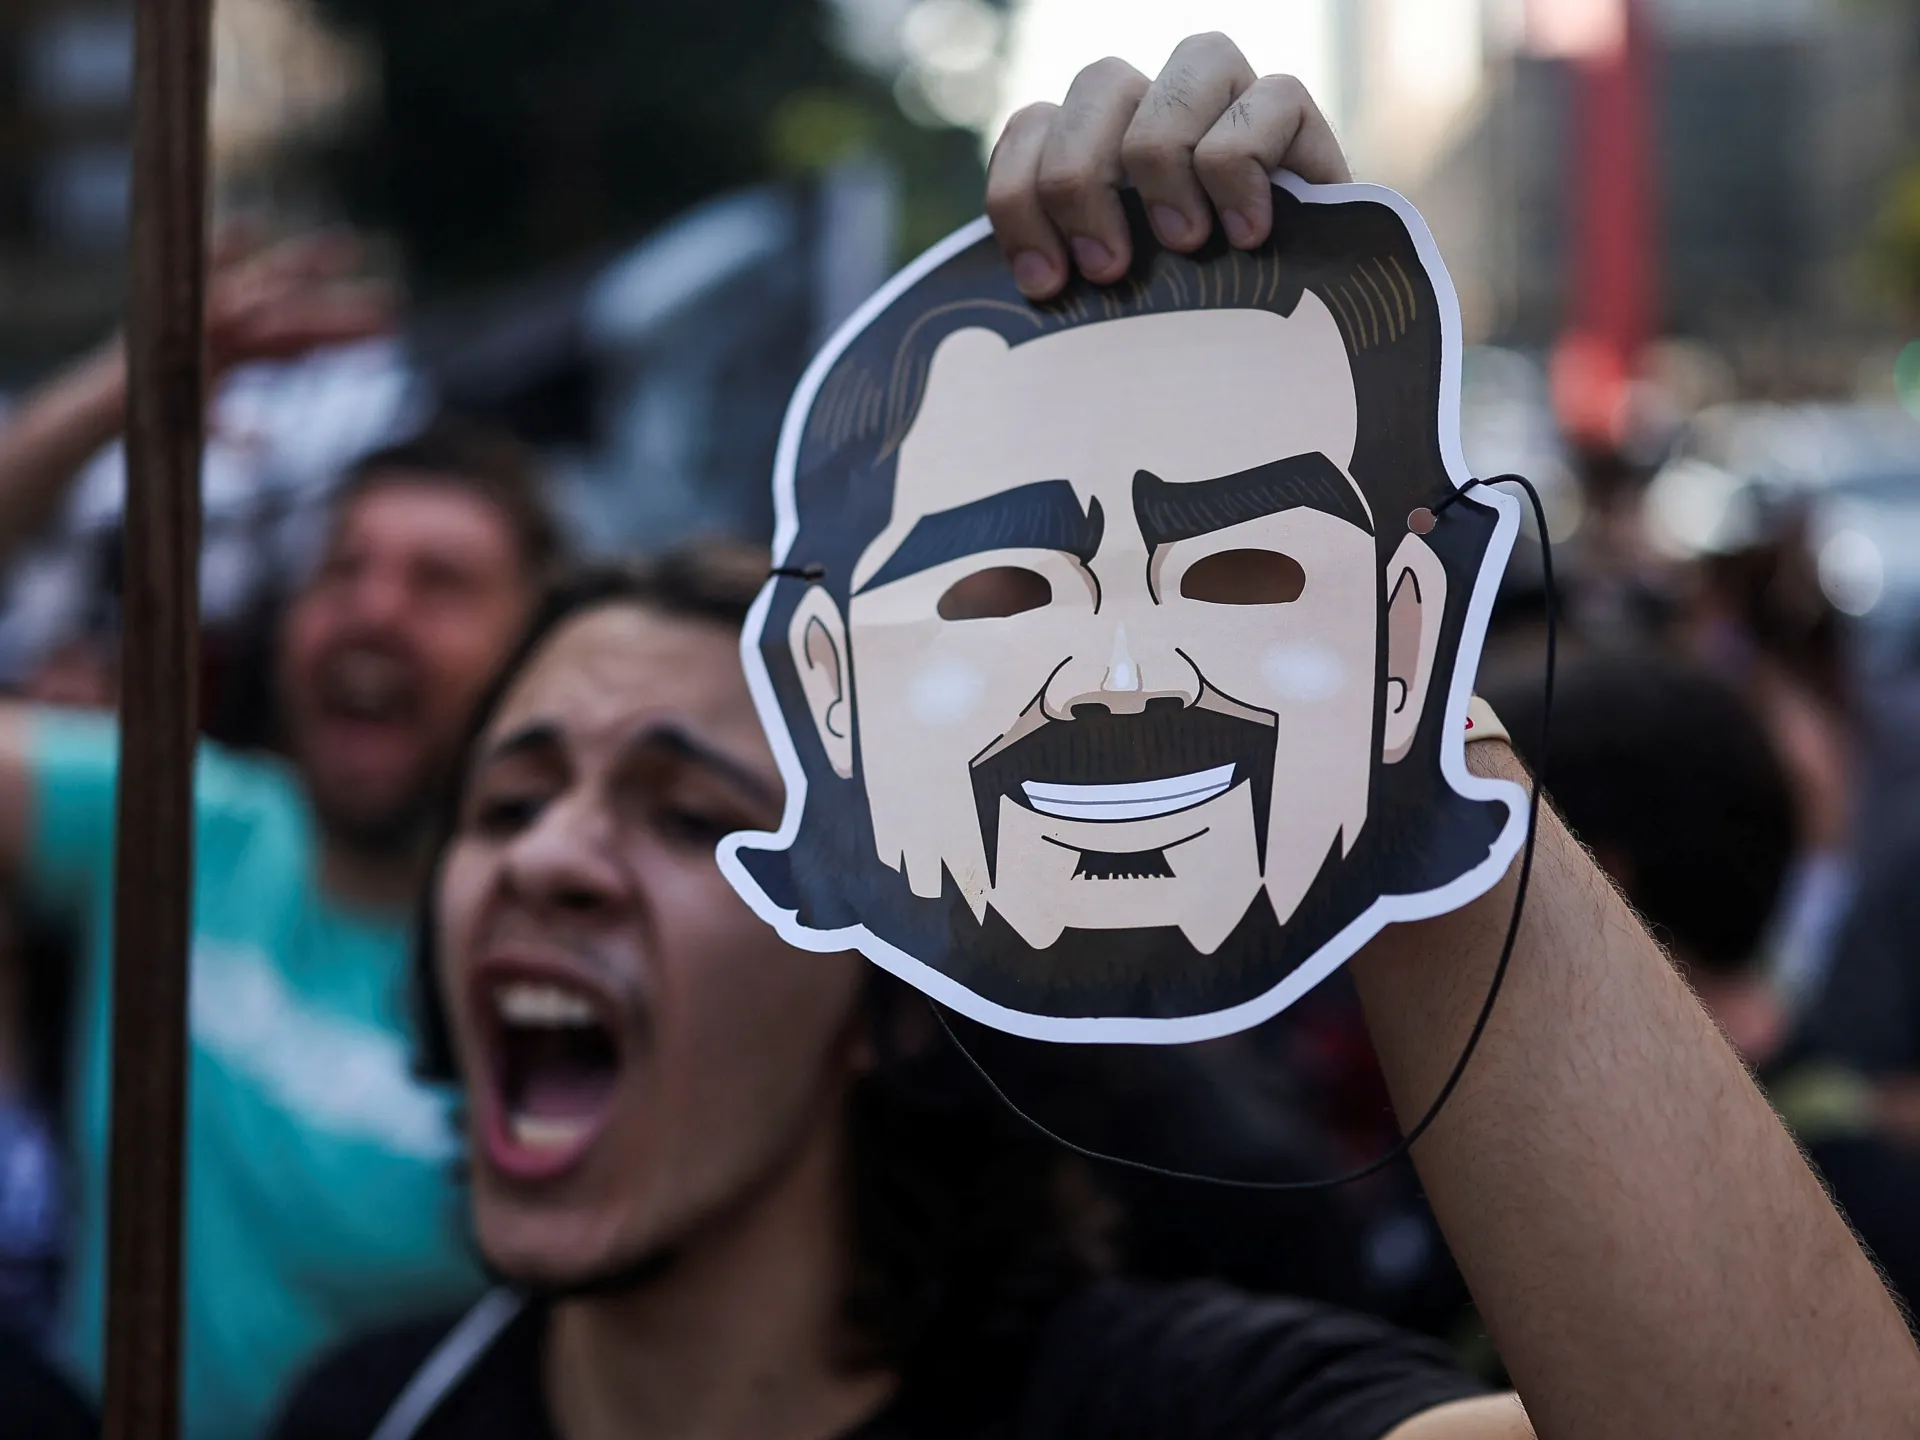
Audio recordings have also surfaced, appearing to show Bolsonaro soliciting the disgraced bank leader for millions in funding. The money was slated as financing for Dark Horse, a film about his imprisoned father, Jair Bolsonaro.

Flavio Bolsonaro has denied any wrongdoing. He described the interaction as a private sponsorship opportunity, unrelated to the Banco Master scandal.

Source link

Caribbean Central Banks Ditch CBDCs

As CBDCs struggle with low adoption, the Caribbean is pivoting to instant payment systems to boost trade and financial integration.

This article appears in the October issue of Global Finance Magazine.

The Caribbean was at the vanguard of adopting central bank digital currencies with the Bahamas’ SandDollar, one of the world’s earliest retail pilots in 2020. A year later, the Eastern Caribbean Central Bank followed suit with its DCash.

With take-up rates low, DCash has since been discontinued as central banks pivot to instant payment systems. The aim is to provide a resilient and flexible system in an area prone to natural disasters and reliant on tourism and remittances as economic drivers.

“These central bank digital currencies had quite poor uptakes. They never really took off,” said Caribbean economist Dalano DaSouza. “Barbados went the route of doing a fast payment system [BiMPay launched on June 12] and the ECCB is embarking on the same journey because they believe that’s where the transformation lies in terms of digital payments.”

The fact that DCash had an outage in 2022 that stopped new transactions for two months did not help consumer confidence and the project was discontinued in February. Jamaica’s Jam-Dex gave the first 100,000 users who signed up a J$2,500 bonus ($15.69), which accounted for about 0.09% of currency in circulation. The 310,443 registered users represent approximately 11% of Jamaica’s population. 

“The lessons learned are that full integration with the banking system is vital. A fast payment system will still be sending and accepting digital payments, but it will be done from the client’s bank account,” DaSouza said. 

WiPay, Lynk and Trinidad and Tobago adopting India’s UIP interface shows a region keen on integrating and expanding its trade opportunities. This includes the possibility of being incorporated into the African Continental Free Trade Area. This would be accomplished via the Caribbean Community’s CAPSS payment system, which is itself based on Africa’s Pan African Payment System platform.

Dalano DaSouza,
Economist

A pilot scheme to harness the Caribbean and African payment systems is underway, involving Barbados, ECCB and the Trinidad and Tobago central banks. The African Export-Import Bank (Afreximbank has been at the forefront of moves to bring the two regions together. The idea that Caribbean countries can join AfCFTA opens a market of 54 countries with 1.3 to 1.4 billion consumers with a combined GDP of approximately $3.4 trillion. 

“Potentially, by using the system to make an instant payment from the Caribbean to a vendor in Africa, you would be bypassing correspondent banks, and you would be bypassing the U.S. and their banks,” DaSouza said.

This removes a barrier to African integration, which is the current issue in the history of payments and having to use correspondent banks in the U.S., England, or Europe.

Digital trade and paperless trade systems reached 73% implementation in 2025, according to the United Nations Economic Commission for Latin America and the Caribbean. 

With the Caribbean piloting the next stage of instant payments, the hope is that this can lead to greater business opportunities, not just regionally but globally. CBDCs arguably started the digitalization of the Caribbean financial system, but now it seems time for instant payments.

“Digital payments will be critical to opening new markets and streamlining old ones,” DaSouza said.

Nic Wirtz is a contributing writer based in Guatemala.

Source link

Revolut’s CEO Says US Banks Are ‘Out of Step’ With Global Consumers | Global Finance Magazine Revolut US Bank Expansion: CEO Cetin Duransoy Interview

Home Banking Revolut’s CEO Says US Banks Are ‘Out of Step’ With Global Consumers

Revolut US CEO Cetin Duransoy reveals plans to target globally minded and “underbanked” Americans as it builds toward becoming a primary bank.

After receiving conditional approval from the U.S. Office of the Comptroller of the Currency for a national bank charter, Revolut Technologies Inc. appears ready to launch a full-scale challenge to traditional banks and fintechs in the United States.

After relatively quick growth in France, Spain, and Italy, Revolut aims to bring its superapp model to the U.S., where it doesn’t exist in quite the same form.

Revolut’s U.S. CEO, Cetin Duransoy, who has held senior roles at Raisin, Fundbox, Visa, and Capital One, spoke with Global Finance about Revolut’s plans for the American market. 

Global Finance: In the US, banks, fintechs, brokerages, travel products and payment apps are mostly separate. Does that surprise you? Do you see a genuine hole in the U.S. market for a company that combines all those relationships in one place?

Duransoy: It’s not surprising, given how complex these products are and how crowded and fragmented the U.S. market is. Layer on the regulatory process, and combining all these product suites—banking, brokerage, FX, crypto, travel, and more—into a single company or app becomes genuinely difficult and, for most companies, not worth the effort.

We believe you need a genuinely differentiated product to succeed in this market, and we have identified an opportunity here. By bringing all these products into one platform, we can remove the friction customers typically experience when cobbling together services from multiple providers.

GF: People often say, “The U.S. banking market is different.” Different how, exactly? And how might those differences affect Revolut?

Duransoy: The US’s fragmented, charter-based regulation can be more cumbersome than the EU’s passporting model, and U.S. customers tend to rely more on credit than their European counterparts. But the U.S. provides certain advantages, including the U.S. card network and interchange system, which subsidize rewards; FDIC insurance; and consumer-protection laws, which create a trust threshold.

Our broad product offering, 80-million-user global network, and strong global brand allow U.S. to cater to the distinct challenges of the U.S. market and understand the challenges of U.S. distribution costs. By obtaining a national bank charter, we will be on par with traditional banks, with direct Fedwire/ACH access and lending capability.

GF: When Revolut enters the U.S. market more aggressively, should Americans expect something close to the European Revolut experience—or will the U.S. product necessarily look much more like a traditional American bank competing on deposits, credit cards and lending?

Duransoy: We are always focused on product-market fit for our customers, and the U.S. will be no different. We’ve publicly shared that we will bring the best of what Revolut offers and provide the products U.S. customers want most, including checking accounts, credit cards, installment loans, FX, and stablecoins. We’ll continue innovating to deliver a distinct, more productive experience for U.S. customers.

GF: One of the things that makes Revolut unusual in Europe is that it sits at the intersection of finance, travel and lifestyle. Is that model central to how you think about the US, or is America more of a banking opportunity?

Duransoy: Yes. Combining our lifestyle products with the financial services that have made Revolut so popular remains central to our thinking. And they’re a key differentiator in many of our markets. We expect these offerings to help make us a top-of-wallet card and strengthen customer retention.

GF: Why should someone with Chase, Amex, Venmo, Robinhood, and a good travel card move meaningful parts of their financial life to Revolut? What can you offer that those companies, individually or collectively, do not?

Duransoy: We recognize that inertia is a strong force when it comes to financial services and that a customer’s bank holds critical parts of their financial life, such as their mortgage or direct deposit.

What we offer is the ability to consolidate multiple products and services into a single interface and remove the friction our customers find frustrating with other services. Revolut’s broad-based platform allows customers to seamlessly access multi-currency spending without foreign transaction fees, instant global P2P, a combined debit/credit product, budgeting, digital assets, and investing, all without transferring funds between platforms or managing multiple accounts. That’s especially valuable for people who travel internationally, have cross-border family ties, or are underserved by traditional credit underwriting.

GF: Which types of lending will Revolut prioritize in the US?

Duransoy: We intend to initially prioritize unsecured and secured credit cards and installment loans.

GF: What does Revolut understand about the consumer relationship that you think many American banks and fintechs still lack?

Duransoy: We treat our global app as the product. We iterate quickly, aim for gamified engagement, and offer frequent feature releases, in contrast to most U.S. bank apps, which have slower release cycles.

We also build for financial lives that span borders and currencies, rather than assuming a single-currency, single-country customer. American banks were largely built for a domestic customer, and that assumption is increasingly out of step with a more mobile, globally connected population.

GF: Do you think Revolut is underestimated in the US? If so, why? Among those who are aware, what do people in the U.S. most commonly misunderstand about Revolut right now?

Duransoy: “Underestimated” is probably right now, largely because our independent U.S. bank doesn’t exist yet. So we’re still seen as a “European neobank” by most Americans. That undersells what we’ll be once we have a full national charter, FDIC insurance, and our full lending capabilities live.

The most common misunderstanding among those who do know the brand is that we’re simply a fintech or a travel debit card, rather than a company with an 80-million-user global base—including 1.4M in the US—and banking licenses now spanning the UK, France, Australia, Mexico, and more.

GF: Are you coming to the U.S. to compete for a small slice of the market, or do you ultimately believe Revolut can change what Americans expect from a bank?

Duransoy: In the US, our near-term goal is to compete for market share. No new entrant can reshape what an entire country expects from a bank on day one. That takes years of trust-building, especially post-charter, when FDIC insurance and regulatory scrutiny are new territory for us.

What we’re looking to do is win the demographics best suited to us, namely the internationally minded, underbanked-by-incumbents, and digitally native users.

GF: On the corporate side, what are Revolut’s corporate banking plans?

Duransoy: Revolut Business exists—and is a core focus for us—in the U.S. We expect this to continue and are excited to launch merchant acquiring within the first years of becoming a bank.

GF: If we revisit this in three years, what would need to be true for you to say that Revolut has successfully become a major U.S. bank?

Duransoy: Within three years, we expect to be a fully operating bank with real momentum. We won’t share specific customer or product numbers today, but we’re building for scale and a sizable U.S. customer base that treats us as their primary bank, not a secondary account. That’s the bar we’re setting for ourselves.

Source link

More Trillion-Dollar US Banks Expected as Consolidation Accelerates

Lighter regulation and excess capital are setting up the biggest U.S. banking wave since the 2008 crisis.

The U.S. banking industry is bracing for its most significant wave of consolidation since the 2008 financial crisis, according to a new Bain & Co. analysis.

The firm expects the number of trillion-dollar U.S. banks to grow from the “Big Four” — JPMorgan Chase & Co., Bank of America Corp., Citigroup Inc., and Wells Fargo & Co. — to as many as seven by 2030. Key drivers include lighter regulation, burgeoning tech and 17 global banks holding over $10 billion each in excess capital. That capital cushion, Bain argues, will lead to a spike in M&A activity.

Banco Santander SA’s August acquisition of Webster Financial Corp. serves as an early example of what could be in store for U.S. banking giants. For Joe Lischwe, a partner in Bain’s financial services and customer strategy practice, the deal illustrates how capital-rich banks are leveraging eased regulatory conditions to combine geographic scale with targeted scope. In this scenario, Santander gets Webster’s health savings account franchise.

“We think there’s a window within this current [Trump] administration over the next two to three years where this will continue to be accelerating,” Lischwe told Global Finance on a call. “You will see more consolidation over the next few years.”

A Capital-Rich Setup

Seventeen U.S. banks currently hold more than $10 billion in excess capital — a figure Lischwe said Bain compiled from a mix of public quarterly filings and third-party data sources, including Refinitiv.

Bain also found that total bank M&A deal value rose 19% in 2025 and is up another 7% so far this year.

“There’s been an uptick in the actual deal value that has been occurring,” Lischwe added. “But I think, probably, the biggest tailwind is from a regulatory perspective.”

The Trump administration continues to move on multiple fronts that matter most to M&A-hungry banks, the latest being on Sept. 17 when the Federal Deposit Insurance Corporation’s (FDIC) proposed new guidelines to make bank mergers easier and faster to approve.

Scale vs. Scope

Not all acquisitions are created equal, according to Bain’s framework, which sorts bank deals into two categories. “Scale” deals expand a bank’s existing footprint — deposits, branches and geographic reach — and generate value primarily through cost synergies.

“Scope” deals, meanwhile, bring in capabilities the acquirer doesn’t already have. Bain predicts that these blended scale-and-scope deals will emerge as the standouts. Capital One Financial Corp.’s acquisition of Discover, which gave Capital One a payments network it previously lacked, produced outsized total shareholder returns on a two-year basis, Lischwe said.

Fifth Third Bancorp’s purchase of Comerica, by contrast, was a more traditional scale play — consolidating similar deposit and branch businesses — without adding new capabilities.

“In general, we were seeing that blended deals, on average, performed better,” Lischwe said. “That’s not to say that scale deals don’t do well.”

The Fintech Integration Trap

Bain’s advice to bank executives is to first conduct a rigorous self-assessment across six dimensions — financial scale, geographic density, business mix, product capability, technology and liquidity — before approaching an acquisition target.

“The answer is not to buy more fintechs,” Lischwe said. “The answer is to know your gaps, diligence those gaps, and then consider every asset that helps you close those gaps.”

Nowadays, fintechs tend to outpace incumbent banks in artificial intelligence, data, payments, blockchain and digital assets — areas that could tempt banks to leapfrog years of in-house development. But evaluating those targets is harder than buying a similar-sized bank, Lischwe said. A fintech operating in an unfamiliar capability area is more difficult to underwrite than a competitor running the same core business.

That complexity introduces significant execution risk for buyers looking to acquire growth quickly.

Winners, Losers, and the Case for Consumers

Jeff Barrington, Windsor Drake Managing Director
Jeff Barrington,
Windsor Drake

Jeff Barrington, Managing Director at tech and payments sell-side advisory firm Windsor Drake, cautions that banks frequently misjudge these acquisitions on several fronts.

“Banks buying fintechs tend to get tripped up in four ways: they pay a growth multiple for revenue that was acquisition cost-fuelled and doesn’t survive inside the bank, they underestimate the cost of bolting a modern stack onto a legacy core, they lose the founders and engineers once the earnout vests, and they misprice the regulatory and partner bank risk that comes attached,” Barrington said. “The recurring error is buying what looks like a growth company and ending up with a bank-owned product that stops growing.”

There’s also the risk of a more concentrated banking landscape: fewer banks means higher fees and diminished access to the kind of relationship-based banking that small towns and entrepreneurs rely on.

Barrington added that while scale can fund improved pricing and technology for users, “consolidation consistently narrows choice, closes branches and thins out relationship lending.

Yes, but …

Banks that fail to acquire or build the AI, data and digital capabilities that are currently reshaping the industry risk falling behind competitively.

“Those [banks] that will be successful are those that will be really ruthless about what are our capability gaps, what can we close inorganically, doing the proper diligence and then properly integrating it,” Lischwe added.

Capital One-Discover, Fifth Third-Comerica and Santander-Webster are recent deals that, so far, have held up. Whether pricier, more speculative targets — he cited digital banking upstart Revolut as an example of an asset banks are watching, despite its rich valuation — get bought will depend on whether acquirers can underwrite a clear strategic fit and value-creation case.

As for whether a change in political control in Washington could derail the trend, Lischwe remains skeptical.

“The regulatory tailwind is going to last,” he said, “through this administration and even into the next one.”

Anthony Noto covers corporate finance and private credit. Contact him at anoto@gfmag.com

Source link