Discovery+, one of Skydance’s new streaming assets, will now cost $6.99 a month for its ad-supported tier, up $1. Its ad-free tier is also up $2, costing viewers $11.99 a month. The prices take effect immediately for new subscribers. Existing subscribers will get 30 days’ notice and see the higher rates on bills dated on or after Nov. 12.
Skydance did not immediately respond to a request for comment.
The platform first launched in 2021, at $4.99 a month for its ad-supported tier and $6.99 for ad-free. Nearly six years later, the price of the cheapest tier has risen roughly 40%, and the ad-free tier has jumped about 72%. This is the service’s second price hike since January 2025.
The standalone streaming service features tens of thousands of TV episodes from cable networks like HGTV, Food Network and TLC.
Before the merger, each company maintained its own streaming services, with HBO Max and Discovery+ under Warner Bros. Discovery and Paramount+ under Paramount Skydance. The services are currently operating as separate entities. But David Ellison, Skydance’s chairman and chief executive, has said he plans to merge the two platforms into one streaming service. It’s unclear when that might happen, what it would cost, or where Discovery+ fits in. The company has not publicly laid out plans for the service.
Prices for HBO Max currently range between $10.99 and $22.99 monthly. Paramount+ costs between $8.99 and $13.99 a month.
Streaming is one of the biggest open questions for Skydance as it enters a new era. The company is carrying roughly $80 billion in debt and is targeting more than $6 billion in cost savings over three years. Skydance has said those savings will come primarily from technology, procurement, marketing and real estate, and Ellison has said the bulk won’t come from layoffs. Industry observers expect that debt load to add pressure for more price increases across Skydance’s streaming lineup.
This price increase also comes at a time when many streaming platforms are similarly hiking their prices — in part to cover the rising cost of programming and talent. Discovery+ joins platforms like Netflix, Apple TV, Hulu and Disney+ which have all raised their subscription fees in the last year. Prime Video raised the cost of its ad-free add-on in April.
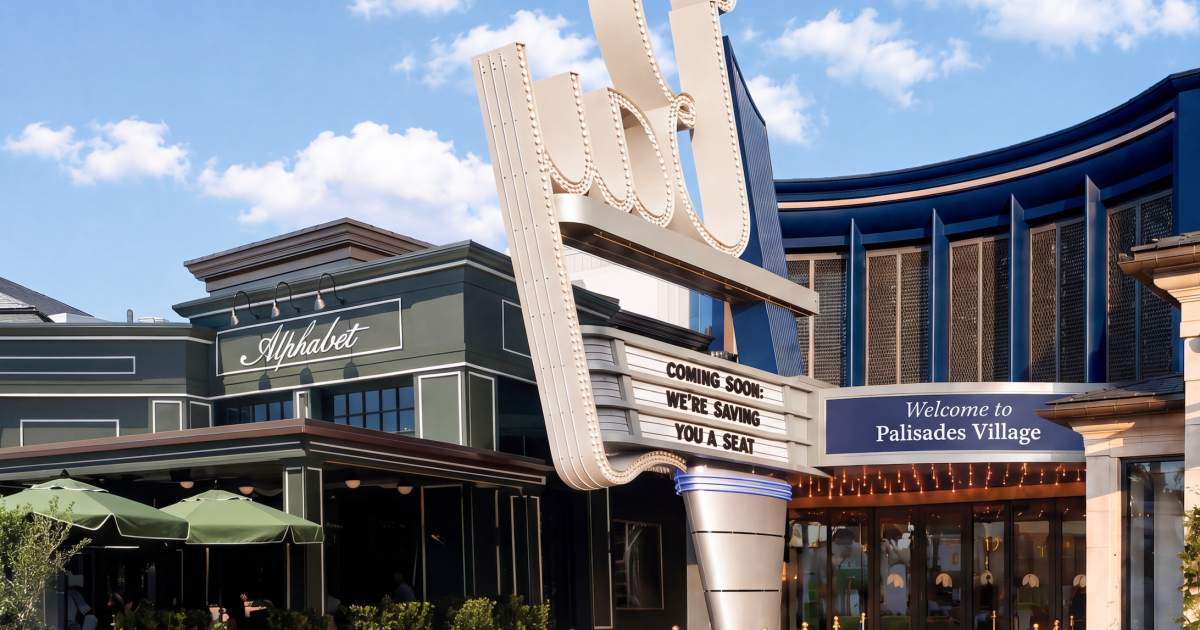
Skydance-owned Paramount Pictures has taken over the lease for the Bay Theater in Pacific Palisades and intends to reopen the cinema, which has been closed since the January 2025 Palisades fire last year.
Paramount plans to upgrade the theater with state-of-the-art projection systems and in-seat food and drink service, Rick Caruso, whose company owns the Palisades Village shopping center where the Bay Theater is located, said in an interview. Caruso is founder and executive chairman of the real estate firm Caruso.
Paramount plans to show first-run theatrical movies from all studios. The theater will be operated by The Lot, a La Jolla-based luxury dine-in theater chain with four locations in California. The theater is expected to reopen later this year, Caruso said.
“The comeback of this movie theater is a great signal for all of L.A.,” he said. “Los Angeles is resilient, and we’re going to show the country that Los Angeles can bounce back from a terrible, terrible disaster, and the comeback is going to be much greater than the setback.”
Palisades Village reopened in August after more than $100 million in renovations, including major infrastructure work. The upscale outdoor mall survived the Palisades fire, but needed refurbishment to eliminate any potential contaminants from the blaze.
Caruso declined to share terms of Paramount’s lease agreement, saying only that it was long-term. Paramount declined to comment on the size of its investment in the theater.
Caruso said he brought up the Bay Theater over lunch last year with David Ellison, chief executive of Skydance, who was then working to acquire Paramount. The two were discussing that deal and Ellison’s belief in the importance of the movie theater business to the industry.
“Together with Caruso, we are proud to help bring the Bay back to life as a place for the Pacific Palisades community to gather around the shared experience of cinema,” Ellison said in a statement. “This theater has always meant more than movies alone — it’s woven into the fabric of this neighborhood, and helping restore it is a privilege.”
The Bay Theater was previously leased by Netflix, which took it over in 2021. The company used the theater to host special events, screen classic films and showcase its own original theatrical movies.
Caruso described Netflix and company Chief Executive Ted Sarandos as “incredible stewards” of the theater, adding that Sarandos was “very much a gentleman” in having the discussion about Paramount stepping in at the theater.
Ellison has long extolled his love of movies and appeared at the CinemaCon movie theater owners convention earlier this year to reiterate his commitment to theatrical releases.
Studios were barred from owning theaters for decades under the Paramount consent decrees, which a federal judge terminated in 2020. Netflix has since operated the Egyptian Theatre in Hollywood and the Paris Theater in New York.
“Through our curated offering and dedicated hospitality, we look forward to welcoming the Pacific Palisades community back to the movies, the way they were intended to be shared,” Adolfo Fastlicht, founder and chief executive of The Lot, said in a statement.
David Zaslav, the longtime TV executive who created Warner Bros. Discovery Inc. but ultimately failed to keep it going as an independent company, made about $600 million on the sale of the business to Paramount Skydance Corp. this week.
Much of Zaslav’s compensation came in the form of stock options. Warner Bros. stockholders received $31 a share in cash in the sale, a nearly 25% increase from when the stock first began trading in April of 2022. The Standard & Poor’s 500 rose 76% over that period.
Many other Warner executives received large paydays, including streaming boss JB Perrette and strategy chief Bruce Campbell. A spokesperson said Zaslav doubled the number of employees overall who received stock awards.
The new company, now called Skydance Corp. and led by technology scion David Ellison, is one of the largest media businesses in the world, comprising the century-old Paramount and Warner Bros. movie studios, dozens of TV networks, like CBS and CNN, as well as the Paramount+ and HBO Max streaming services.
Christopher Palmeri and Dylan Sloan report for Bloomberg.
Tech scion David Ellison spent three years doggedly pursuing his dream: acquiring Paramount, then Warner Bros. Discovery.
Ellison pulled off his bold feat this week by completing Paramount’s $111-billion takeover of Warner Bros., uniting two industry pioneers and a wealth of cherished properties — Batman, Bugs Bunny, Harry Potter and Maverick of “Top Gun,” as well as CBS, HBO, Comedy Central and CNN. All will be tucked under a corporate umbrella that Ellison is calling Skydance — the name of the studio he formed two decades ago.
The mogul and his lieutenants celebrated their victory in style, ringing the New York Stock Exchange opening bell on Thursday, capping a bruising battle to secure approval of a deal that had sparked protests across Hollywood over fears of looming job cuts.
Ellison and his team must braid together two huge film studios (housing nine film labels), four streaming services, three TV production studios, three animation units and more than 50 television networks, including two prominent news organizations. That could be a daunting task, particularly based on how previous Hollywood mergers have fared.
“Now, the real work begins,” David G. Fubini, a Harvard Business School senior lecturer, said in an interview.
Anxieties were evident Tuesday — the day the deal closed — when Ellison held a town hall meeting at Warner Bros., which drew nearly 500 employees.
During the session, CNN’s Anderson Cooper quizzed his new bosses, including about anticipated layoffs and news independence.
“Do you stand with CNN and our effort to completely restore access to covering President Trump?” Cooper asked, referring to CNN’s legal fight alongside MS Now and Politico to reverse the president’s ban on the three organizations.
“Of course,” Ellison replied.
CNN news anchor Anderson Cooper, pictured here in 2021, quizzed his bosses at a Burbank town hall.
(Evan Agostini / Invision / Associated Press)
Hours later, Ellison parried with reporters in Paramount’s darkened Stage 3, recently revamped with laser projection capabilities to simulate fantastical and far-flung settings for TV shows, such as the streets of New York.
“This was a turbulent process, and, at times, a really ugly process, to actually get this deal over the finish line,” Ellison acknowledged to reporters. “What I want to be able to do now is turn the page, and actually make sure that we are in the business of rebuilding trust.”
To do that, Ellison intends to make more movies and TV shows than rivals. He wants to ensure the Warner Bros. and Paramount studios, which will be kept separate for now, remain talent-friendly destinations.
Ellison has taken an opposing view from his predecessors who confronted crumbling industry economics by cutting expenditures to boost their corporate bottom lines.
The 43-year-old executive, son of Oracle co-founder Larry Ellison, proudly views his family as “owner-operators,” unshackled by quarterly earnings expectations or the need to dole out dividends to keep investors happy. The Ellison family controls the company’s voting stock, allowing David Ellison to take a long-term view as he charts Skydance’s course.
The goal is to “win in storytelling,” Skydance said in an investor presentation. It intends to build the media industry’s most “technologically capable” firm, which uses artificial intelligence to speed work flows. Skydance plans to spend at least $30 billion a year on film, television and video game content.
Skydance co-CEO Ynon Kreiz, Sarah Ellison, CEO David Ellison and investor Gerry Cardinale of RedBird Capital Partners on the floor of the New York Stock Exchange on Thursday.
(Yuki Iwamura / Associated Press)
The realities of Ellison’s big swing will soon sink in as he and his team turn their focus to integrating the myriad operations and about 55,000 employees.
In some ways, Ellison is behind the curve.
Most major mergers are consummated after executives have dedicated months to quietly drafting detailed operational plans and organizational hierarchies. Ellison, in contrast, has spent the last nine months in a pitched battle for Warner Bros. — ultimately vanquishing Netflix, hundreds of vocal merger opponents, and California Atty. Gen. Rob Bonta and his coalition of 11 other state attorneys general who filed an antitrust lawsuit in July in an attempt to derail the deal.
Ellison and Bonta resolved their legal fight Sept. 21. A week later, a federal judge cleared the way for the merger to close.
The lawsuit settlement with Bonta requires that the combined company produce at least 30 movies a year for five years. It also must maintain the studio facilities in Los Angeles, making “reasonable efforts to operate the lots in a manner consistent with past practices,” according to the agreement.
Skydance has committed to maintaining operations on the Warner Bros. lot, pictured here, and at Paramount Pictures in Hollywood.
(Eric Thayer / Los Angeles Times)
Ynon Kreiz, former chief executive of Mattel toys in El Segundo, has been tasked with leading the integration. The 61-year-old executive joined Ellison at Skydance as his co-CEO earlier this week. Day One of the combined company marked Kreiz’s second day on the job.
“They have a whole new management team that will be expected to immediately lead this massive integration,” Fubini, a former partner at consulting firm McKinsey, said. “The clouds have cleared, and they are at the base camp of Mt. Everest facing this enormous undertaking.”
In a report this week, TD Cowen Global Research maintained its “hold” rating on the newly constituted Skydance, expressing some doubts about Ellison and his team’s ability to “avoid integration and execution problems that have bedeviled other major media mergers.”
Hollywood has had a history of failed mergers, including Discovery’s 2022 takeover of WarnerMedia from AT&T, which led to years of cost cuts that ultimately seeded the ground for Ellison’s takeover. AT&T’s purchase of the same assets in 2018 also quickly unraveled, some 20 years after the epic failure of AOL Time Warner.
Ellison now must grapple with the hefty acquisition costs for Warner Bros., which climbed as the deal was delayed. The company emerged from the transaction with $86.8 billion in total debt; with most of that going toward buying out Warner Bros. Discovery’s stockholders at $31.17 a share.
The debt burden also includes more than $18 billion in obligations leftover from past mergers. Skydance has nearly $7 billion in cash on hand.
Oracle’s Larry Ellison and executive producer David Ellison arrive at the L.A. premiere of “Star Trek Into Darkness” at the Dolby Theatre in 2013.
(Eric Charbonneau / Getty Images for the Hollywood Reporter)
The Ellison family brought in foreign investors, including royal families of Saudi Arabia, Qatar and Abu Dhabi as passive owners, to contribute equity to the deal. Gerald Cardinale’s RedBird Capital Partners, a longtime Skydance stakeholder, added $4 billion, bringing its total investment in Skydance deals to $6 billion.
The deal’s financial terms pose deep challenges, analysts said. Fitch Ratings this week downgraded Skydance credit, citing “materially higher leverage after the acquisition and significant execution and integration risks,” according to its report.
“Interest rate increases made financing this transaction far more expensive than anyone anticipated,” said Eric Talley, a professor at Columbia Law School. “Those lenders are going to start expecting their interest payments — Skydance executives won’t have the luxury of time.”
The company could struggle, Talley said, to “generate the cash flow needed to easily service that debt unless they can significantly cut costs.”
Skydance has promised investors that it will make $6 billion in cost cuts over three years. It anticipates $2 billion in reductions within a year, with the bulk of the rest occurring in the second year of the merger.
“They are going to be firing a lot of people,” TD Cowen Global Research media analyst Doug Creutz said.
During the press briefing, Kreiz sought to downplay the expected workforce toll, saying Skydance would achieve savings by combining technologies that support streaming services and marketing expenditures. It plans to save costs on real estate by locating employees at Skydance-owned properties in Santa Monica, Hollywood and Burbank.
Ellison and Kreiz said they would jointly manage the new colossus.
“Where David will focus on creative, technology, long-term strategy, including especially as it relates to the creative part of the business, I will focus more on the operations and the day-to-day management of the business,” Kreiz said.
Kreiz was named to Skydance‘s expanded board this week along with Laurene Powell Jobs, founder of the Emerson Collective; and Bobby Kotick, former CEO of Activision.
The new leaders expressed confidence they could expand and integrate their two major streaming services to drive growth. HBO Max and Paramount+ combined will reach more than 200 million subscribers.
The plan, they said, is to combine the two streamers within a couple of years, but the company may offer subscribers a bundle with the two offerings sooner.
Skydance, according to sources, also expects to bolster its free, ad-supported service Pluto TV, which offers more than 200 channels. The service hasn’t had much corporate attention in recent years amid the cuts and deal-making.
The executives have not disclosed which teams would soon be affected or how they will structure overlapping business units.
For example, the company’s three TV studios each have their own leader: Channing Dungey runs the largest, Warner Bros. Television; David Stapf has long managed CBS Studios; and Skydance executive Matt Thunell has been president of Paramount Television Studios since last year.
Integrating CNN and CBS
Anxiety over whether CNN and CBS News would be mashed together was quelled, at least for now.
Skydance announced that it was retaining CNN Worldwide Chairman Mark Thompson as head of the larger news organization. CNN journalists had worried that CBS News Editor in Chief Bari Weiss, who has presided over a year of turmoil at the network, would be put in charge of both.
Any news consolidation could take years, in part, because CBS News is largely unionized while CNN is a non-union shop.
“We are going to spend the next several months basically getting under the hood,” Ellison said.
CBS News Editor in Chief Bari Weiss, pictured here in 2023 in Los Angeles, has had a turbulent tenure at CBS.
(Francine Orr / Los Angeles Times)
Another challenge will be stabilizing the Warner Bros. film unit, which has had a rough year at the box office. This month, the top two Warner Bros. film executives, Mike DeLuca and Pam Abdy, exited abruptly, clearing the way for longtime Ellison lieutenants Dana Goldberg and Josh Greenstein to oversee both film studios. The co-heads of DC Comics, James Gunn and Peter Safran, segued to the new Skydance.
Skydance also will have to deal with the NFL, which could demand substantially higher fees for CBS to keep its Sunday games.
The current contract allows the league to reopen negotiations because of the ownership change. Skydance is hoping it can wait three years until the contracts of other broadcasters also are up for discussion.
Skydance will be a major player in sports. Last year, Paramount agreed to spend $7.7 billion for UFC fights. The combined company also has rights to professional golf, including the Masters tournament; National Hockey League; Major League Baseball and NCAA basketball, including March Madness, as well as European rights to televise the Olympics.
“Until you actually get inside the company, there are things you won’t know,” Creutz said. “But they are going to have to come up with answers pretty quick.”