money

$200 million-plus spent fighting and supporting billionaire tax

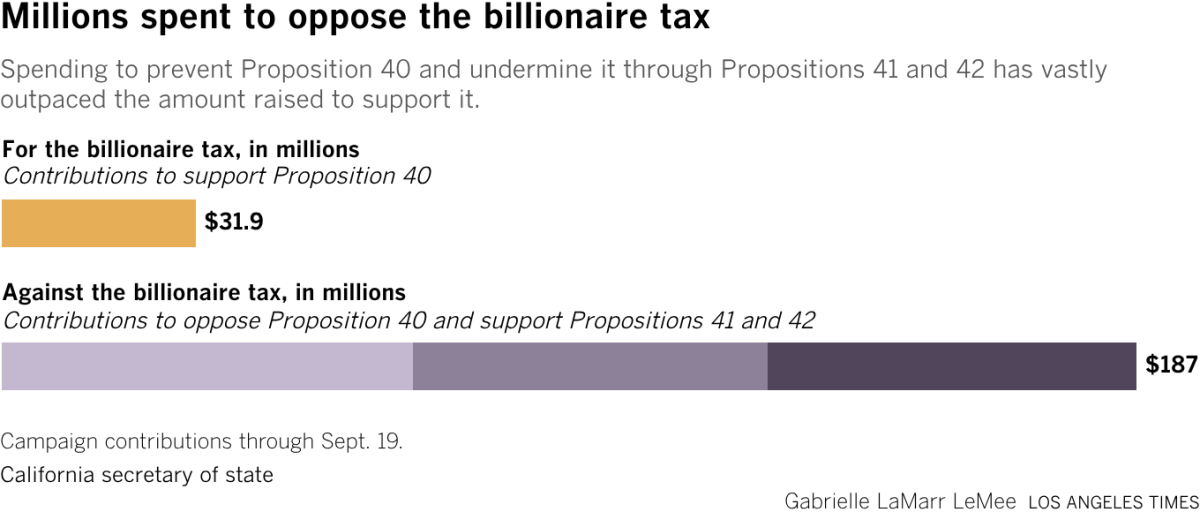
Opponents of the billionaire tax on the November ballot have vastly outraised the proposal’s supporters, with the anti-Proposition 40 effort and the backers of two other ballot measures crafted to nullify it raising $187 million compared to the $32 million raised by boosters of the wealth tax, according to campaign finance documents filed with the state.

The reports, filed Thursday, account for donations through Sept. 19 and do not include several million dollars that have poured into campaign coffers in recent days. The numbers are expected to vastly increase before the Nov. 3 election.

The bulk of the money raised by the proponents of Proposition 40, which would enact a one-time 5% tax on California billionaires’ assets, appears to have been spent on gathering signatures to qualify the measure for the November ballot. The campaign had only $207,000 in the bank, according to the latest campaign finance reports.

A leader of the union that crafted the proposal accused wealthy Californians who are spending heavily against the measure of lying to voters. The measure is designed to offset $100 billion in impending federal healthcare funding cuts expected to impacts millions of Californians.

“The billionaires take and take — tax break after tax break — and now they’re spending that money to deceive voters and avoid paying their fair share,” said Suzanne Jimenez, the chief of staff of the Service Employees International Union-United Healthcare Workers West. “Voters want their money back from the billionaires and want local emergency rooms to stay open. California does not need more tax breaks for billionaires. California needs emergency rooms for patients, hospitals that stay open, and healthcare people can access and afford.”

Opponents of the billionaire tax argue that it would do more harm than good.

“The more Californians learn, the more they see Proposition 40 for what it is — a harmful tax scheme that permanently damages the state’s budget and economy with zero accountability or safeguards to ensure funding actually improves care or lowers costs for patients,” said California Medical Assn. President Dr. René Bravo, the leader of one of the groups opposing the billionaire tax.

Proposition 41 would nullify the billionaire tax if, in the event that both measures are approved, it receives more “yes” votes. Proposition 41 would prohibit any new state tax from being excluded from a voter-approved cap that restricts how much tax revenue the state can spend each year.

“Californians deserve better results for their hard-earned tax dollars,” said Molly Weedn, a spokesperson for the Proposition 41 campaign.

Proposition 42 would prohibit new taxes on personal property, intellectual property, retirement accounts and other assets, and would limit situations in which a ballot measure or state lawmakers can impose or raise taxes retroactively — both of which are essential parts of Proposition 40. If both measures pass and Proposition 42 receives more “yes” votes, it would nullify the wealth tax.

The proposed billionaire tax has divided California Democrats, with Gov. Gavin Newsom opposing it while the state Democratic party supports it.

In recent polling, a majority of likely voters did not support any of the three proposals.

While 45% of likely voters supported the billionaire tax, 42% opposed it, according to a poll released Friday by UC Berkeley’s Institute of Governmental Studies and co-sponsored by the Los Angeles Times. Voters also are torn about the two ballot measures designed to nullify it.

The other measure receiving great attention, Proposition 39, which would require voters to show government-issued ID to cast ballots, faces a similar financial disparity. Opponents to the measure have raised $39.3 million compared to $15.6 million garnered by supporters.

Fifty-two percent of likely California voters oppose the voter ID proposal, while 39% support it and 9% are undecided, according to the Berkeley poll.

In the race to replace Newsom, Democratic former Biden cabinet member Xavier Becerra has raised $35.8 million, while his GOP rival, conservative strategist and television commentator Steve Hilton, has raised $22.3 million.

Becerra remains the front-runner in the governor’s race, which is not surprising since Democratic voters outnumber Republicans nearly 2 to 1. In last week’s Berkeley poll, the Democrat had the support of 58% of likely voters, while 33% backed the Republican.

Source link

More Trillion-Dollar US Banks Expected as Consolidation Accelerates

Lighter regulation and excess capital are setting up the biggest U.S. banking wave since the 2008 crisis.

The U.S. banking industry is bracing for its most significant wave of consolidation since the 2008 financial crisis, according to a new Bain & Co. analysis.

The firm expects the number of trillion-dollar U.S. banks to grow from the “Big Four” — JPMorgan Chase & Co., Bank of America Corp., Citigroup Inc., and Wells Fargo & Co. — to as many as seven by 2030. Key drivers include lighter regulation, burgeoning tech and 17 global banks holding over $10 billion each in excess capital. That capital cushion, Bain argues, will lead to a spike in M&A activity.

Banco Santander SA’s August acquisition of Webster Financial Corp. serves as an early example of what could be in store for U.S. banking giants. For Joe Lischwe, a partner in Bain’s financial services and customer strategy practice, the deal illustrates how capital-rich banks are leveraging eased regulatory conditions to combine geographic scale with targeted scope. In this scenario, Santander gets Webster’s health savings account franchise.

“We think there’s a window within this current [Trump] administration over the next two to three years where this will continue to be accelerating,” Lischwe told Global Finance on a call. “You will see more consolidation over the next few years.”

A Capital-Rich Setup

Seventeen U.S. banks currently hold more than $10 billion in excess capital — a figure Lischwe said Bain compiled from a mix of public quarterly filings and third-party data sources, including Refinitiv.

Bain also found that total bank M&A deal value rose 19% in 2025 and is up another 7% so far this year.

“There’s been an uptick in the actual deal value that has been occurring,” Lischwe added. “But I think, probably, the biggest tailwind is from a regulatory perspective.”

The Trump administration continues to move on multiple fronts that matter most to M&A-hungry banks, the latest being on Sept. 17 when the Federal Deposit Insurance Corporation’s (FDIC) proposed new guidelines to make bank mergers easier and faster to approve.

Scale vs. Scope

Not all acquisitions are created equal, according to Bain’s framework, which sorts bank deals into two categories. “Scale” deals expand a bank’s existing footprint — deposits, branches and geographic reach — and generate value primarily through cost synergies.

“Scope” deals, meanwhile, bring in capabilities the acquirer doesn’t already have. Bain predicts that these blended scale-and-scope deals will emerge as the standouts. Capital One Financial Corp.’s acquisition of Discover, which gave Capital One a payments network it previously lacked, produced outsized total shareholder returns on a two-year basis, Lischwe said.

Fifth Third Bancorp’s purchase of Comerica, by contrast, was a more traditional scale play — consolidating similar deposit and branch businesses — without adding new capabilities.

“In general, we were seeing that blended deals, on average, performed better,” Lischwe said. “That’s not to say that scale deals don’t do well.”

The Fintech Integration Trap

Bain’s advice to bank executives is to first conduct a rigorous self-assessment across six dimensions — financial scale, geographic density, business mix, product capability, technology and liquidity — before approaching an acquisition target.

“The answer is not to buy more fintechs,” Lischwe said. “The answer is to know your gaps, diligence those gaps, and then consider every asset that helps you close those gaps.”

Nowadays, fintechs tend to outpace incumbent banks in artificial intelligence, data, payments, blockchain and digital assets — areas that could tempt banks to leapfrog years of in-house development. But evaluating those targets is harder than buying a similar-sized bank, Lischwe said. A fintech operating in an unfamiliar capability area is more difficult to underwrite than a competitor running the same core business.

That complexity introduces significant execution risk for buyers looking to acquire growth quickly.

Winners, Losers, and the Case for Consumers

Jeff Barrington, Windsor Drake Managing Director
Jeff Barrington,
Windsor Drake

Jeff Barrington, Managing Director at tech and payments sell-side advisory firm Windsor Drake, cautions that banks frequently misjudge these acquisitions on several fronts.

“Banks buying fintechs tend to get tripped up in four ways: they pay a growth multiple for revenue that was acquisition cost-fuelled and doesn’t survive inside the bank, they underestimate the cost of bolting a modern stack onto a legacy core, they lose the founders and engineers once the earnout vests, and they misprice the regulatory and partner bank risk that comes attached,” Barrington said. “The recurring error is buying what looks like a growth company and ending up with a bank-owned product that stops growing.”

There’s also the risk of a more concentrated banking landscape: fewer banks means higher fees and diminished access to the kind of relationship-based banking that small towns and entrepreneurs rely on.

Barrington added that while scale can fund improved pricing and technology for users, “consolidation consistently narrows choice, closes branches and thins out relationship lending.

Yes, but …

Banks that fail to acquire or build the AI, data and digital capabilities that are currently reshaping the industry risk falling behind competitively.

“Those [banks] that will be successful are those that will be really ruthless about what are our capability gaps, what can we close inorganically, doing the proper diligence and then properly integrating it,” Lischwe added.

Capital One-Discover, Fifth Third-Comerica and Santander-Webster are recent deals that, so far, have held up. Whether pricier, more speculative targets — he cited digital banking upstart Revolut as an example of an asset banks are watching, despite its rich valuation — get bought will depend on whether acquirers can underwrite a clear strategic fit and value-creation case.

As for whether a change in political control in Washington could derail the trend, Lischwe remains skeptical.

“The regulatory tailwind is going to last,” he said, “through this administration and even into the next one.”

Anthony Noto covers corporate finance and private credit. Contact him at anoto@gfmag.com

Source link