Magazine

Anna Holmes reflects on Jezebel’s legacy, moving to L.A., her new book

On the Shelf

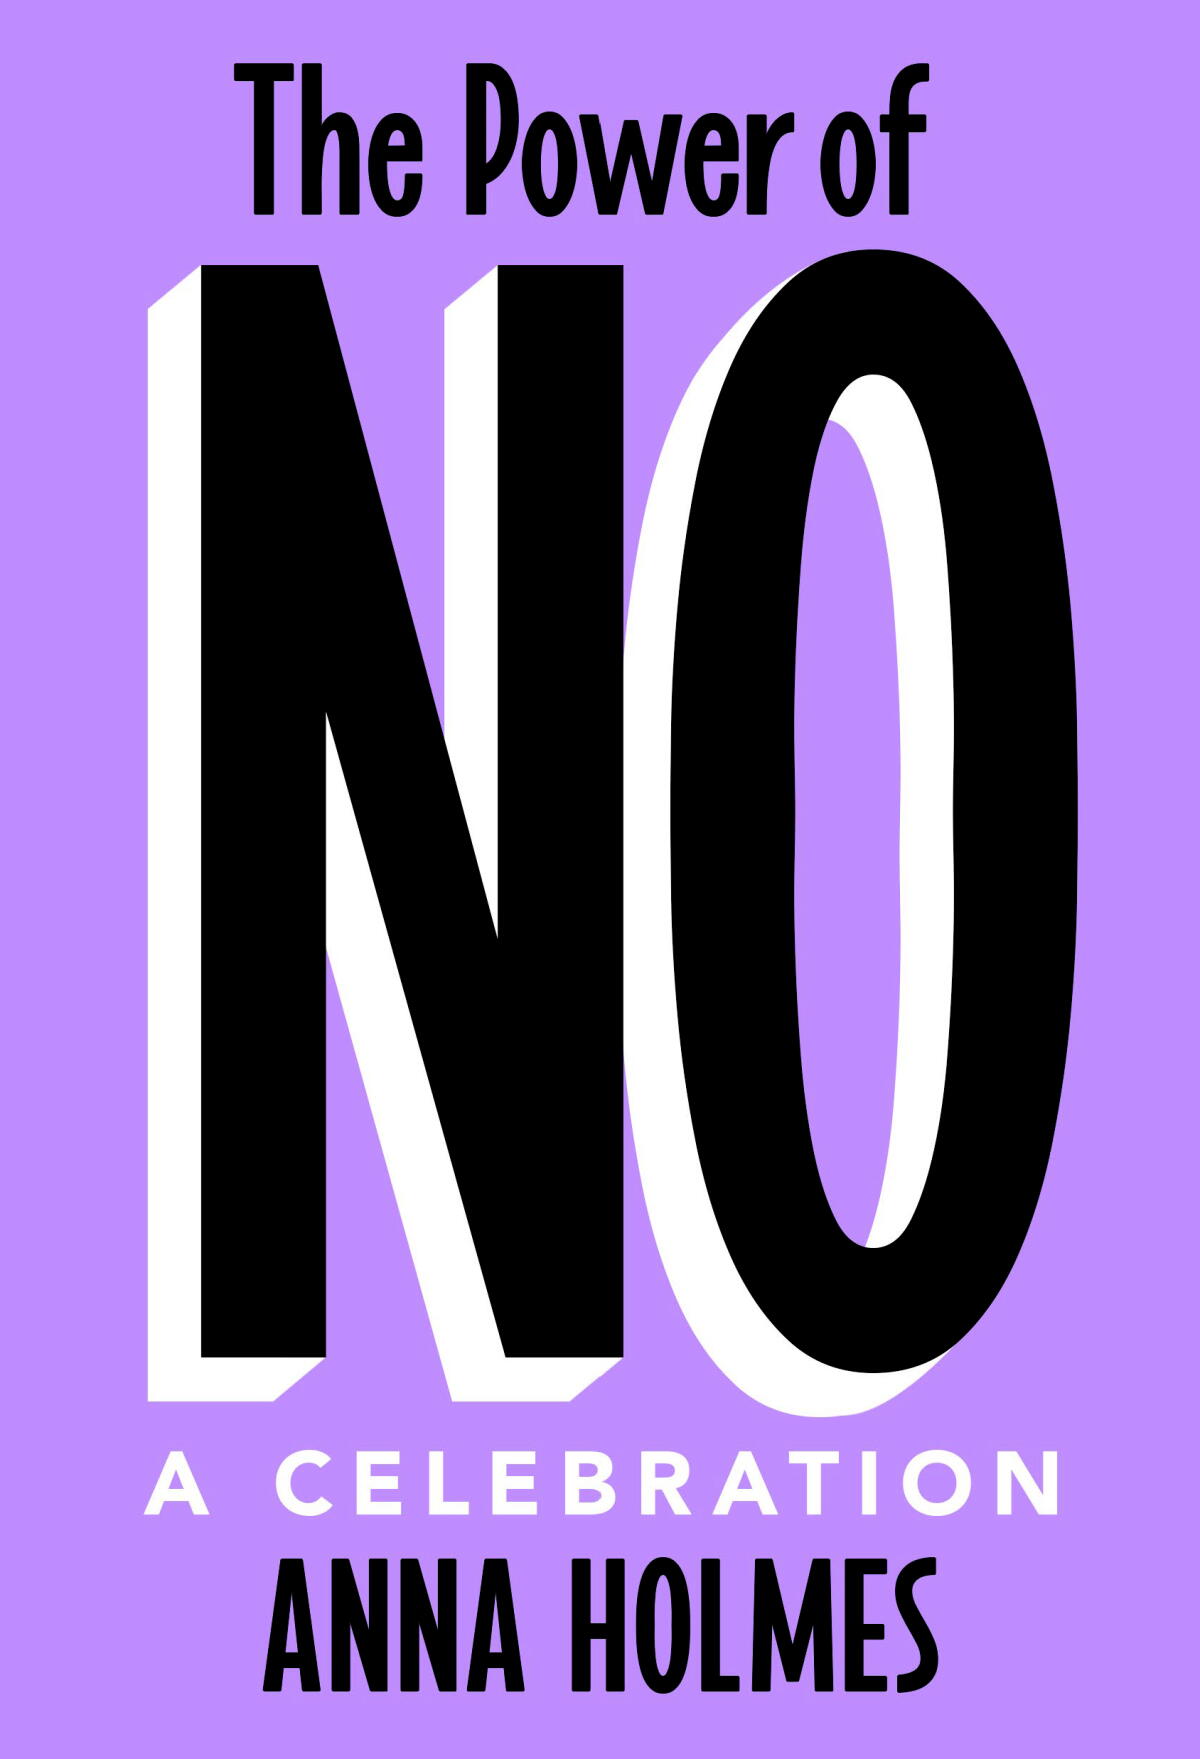
The Power of No: A Celebration

By Anna Holmes
Knopf: 160 pages, $24

If you buy books linked on our site, The Times may earn a commission from Bookshop.org, whose fees support independent bookstores.

On a blazing hot Silver Lake morning, ushering in yet another heatwave day, Anna Holmes and I say “no” to a steamy sidewalk table at Millie’s Cafe, opting instead for an indoor, air-conditioned spot. Our server reads our order back to us, shaking his head in theatrical disbelief. “Pancakes. French toast. Biscuit. Waffle with whipped cream.” He glances from one of us to the other. “No protein?” he asks. “Just the carbs?”

“I guess I’ll have some egg whites, too,” I cave. Not so my brunch companion who confirms, “Just the carbs.” Holmes grins, “I’m not a fan of fad diets that make women hate ourselves.”

In fact, Holmes has built a career of saying “no” to woman-hating of all kinds — starting in 2007, when she founded the boundary-pushing feminist website Jezebel, the sister site of the notoriously provocative Gawker. “I decided that NO would be our mantra of sorts,” she writes in her new book, “The Power of No: A Celebration.” “‘No’ to diet tips, ‘no’ to sexist gossip, ‘no’ to conspicuous consumption. We drove the point home again and again … creating new definitions and examples of what it means to be female.”

Raised in a biracial, working-class family in Davis, Calif., Holmes escaped to New York at 18, chasing her writer’s dream. “Davis was a safe, homogenous little town,” she tells me, spearing one of the sliced strawberries fanned prettily across her waffle. “Being Black, I wasn’t one of the homogenies. I couldn’t wait to get out.”

"The Power of No: A Celebration" by Anna Holmes

“The Power of No: A Celebration” by Anna Holmes

(Crown)

Accepted by several top universities, Holmes said ‘yes’ to New York University. “They gave me money,” she explains. “And they had a journalism school.” After graduating, Holmes grabbed a rung on the media ladder and started climbing: writing and editing for Glamour, InStyle and Entertainment Weekly. Holmes published her first book, “Hell Hath No Fury: Women’s Letters from the End of the Affair,” featuring a collection of breakup letters from the likes of Anaïs Nin, Charlotte Brontë and Sylvia Plath, in 2002.

“So, you’ve always been a slacker,” I say.

Holmes laughs. “I come by my drive honestly. It stems from my fear of failure. And growing up lower-middle class, without the kinds of connections the wealthier kids had.”

Next came the breakthrough media success of Jezebel. Her project quickly reached 10 million monthly views, exceeding Gawker’s. But the bold irreverence that drew droves of devoted readers to Jezebel brought contention, too. In June 2010, Jezebel reported that women’s exclusion from senior positions at “The Daily Show” — which the article called a “boys’ club” — was “frustrating and alienating” for women. The story earned an on-air mention by Jon Stewart, who announced “Jezebel thinks I’m a sexist prick” — and an open letter signed by more than 30 female “Daily Show” employees, refuting Jezebel’s allegations.

Author Anna Holmes.

Author Anna Holmes.

(Annie Noelker / For The Times)

Weeks later, under the header “How feminist blogs like Jezebel gin up page views by exploiting women’s worst tendencies,” former Gawker employee Emily Gould wrote in Slate, “When Jezebel was founded, it proposed itself as an explicit alternative to traditional women’s magazines … but the easiest way for Jezebel writers to be provocative is to stoke readers’ insecurities — just in a different way.”

Holmes says some Jezebel haters were anti-feminist or far-right. “Others were politically aligned with Jezebel, but felt we were too pop-culture-focused. Some accused us of being snarky to other women,” she adds.

After three years, Holmes resigned. “I’d done what I went to Jezebel to do,” she says. “Also, the 14-hour workdays were threatening my marriage, my sanity and my health. I was smoking too much. Drinking too much. Gaining weight.”

Holmes said a final goodbye to her creation in 2013 by publishing “The Book of Jezebel: An Illustrated Encyclopedia of Lady Things.” Despite — and because of — having founded one of the internet’s most provocative publications, she helped lift up journalists, and journalism, in her wake.

“I would follow Anna off of a cliff, professionally and personally,” says Reyhan Harmanci, Wired’s editorial director, who reported to Holmes at Topic magazine a decade ago. “She channels her curiosity in a way that opens the world to readers.”

Former Gawker editor A.J. Daulerio also lights up at the mention of Holmes’ name. “If you look back at Anna’s history of finding and developing talent, you can see her impact. Writers who’ve worked with and for her can be found on podcasts, on mastheads at major publications and on bestseller lists.” Meanwhile, New York magazine’s Emily Gould, who wrote the biting Slate critique of Jezebel in 2010, has come to admire Holmes. “Nobody’s right 100% of the time,” Gould says, “especially when publishing around the clock and reacting to news as it unfolds. My current sense of Anna is that she’s genuinely brave, clear-sighted and wise. I’m eager to read her new book.”

Post-Jezebel, Holmes wrote the “Bookends” column for the New York Times Book Review. Her byline grew a few picas when she replaced Roxane Gay as editor of the Times’ popular “Work Friend” column. Having “made it there,” Holmes decided to leave New York.

“I never considered myself a New Yorker,” she says, stirring a foam flower into her latte. “When people asked, I’d say, ‘I’m from California but I live in New York.’”

While deliberating about where to go next, Holmes says, “I got a job offer with the Obamas’ production company in L.A.”

“The Obamas?” I blurt. Holmes nods. “I was tired of New York. And wanting to be closer to my elderly mom.” In the first week of the COVID shutdown, Holmes packed her two hissing black cats, donned an N95 mask and flew to LAX. Six years later, after several moves around town, she shares the upper half of a sun-splashed 1920s duplex with Ewok and Harriet.

“I didn’t have a writing community in New York and I don’t have one here,” Holmes says about her L.A. move. “I had a media community in New York. If that exists here, I’m not invited to those parties.” She cocks her head. “Every once in a while, I wonder, ‘Does Susan Orlean have regular salons? And if so, can I please go?’”

Holmes continues to settle into a slower, more domestic groove. “I’m 53 now,” she says. “I don’t want to go out all the time. I like going to bed early. All the cliches are true of me: moving from NYC to L.A. and ending up in Silver Lake — with a Volvo, no less. In my defense, I dress like a tomboy, I don’t have tattoos and I’ve never been to Bar Stella.”

Since her big move, Holmes has written “The Power of No” and is finishing up her fourth book, a sexual memoir. Her articles on wildly divergent topics continue to appear in the New York Times, the New Yorker, the Atlantic and L.A. Material.

“The Power of No” is a slim but impactful guide to the human dance between yes and no; vulnerability and ambition. The book consists of readily digestible yet smart, sophisticated bits, including quotes from luminaries, research findings, anecdotes from Holmes’ own life and others, practical tips, and lists like “Ways to Say No” (which is especially helpful to have on hand during the upcoming holiday season).

“No,” Holmes writes on Page 1: “As uttered by a woman, a provocation. Has there ever been a more fraught relationship between women and word?” By way of example, she cites what she calls “my biggest NO, my strongest rejection of what was expected of me as a woman: founding Jezebel.”

“Has writing about ‘no’ made you better at saying it?” I ask Holmes.

“I don’t purport to be good at it,” she answers. “But I’m more cognizant now of wanting to say it, at least.”

Maran, author of “The New Old Me” and other books, lives in Silver Lake.
Source link

CFOs Sing the Blues | Global Finance Magazine

European CFOs face mounting economic uncertainty, shifting priorities toward cost discipline and resilience.

A Deloitte CFO survey conducted in April showed that 48% of respondents are less optimistic about their companies’ prospects than they were six months earlier. Their pessimism in autumn 2025 was limited to 25%.

Economic uncertainties explain that state of mind: 76% of respondents put energy shocks, inflation, the conflict in the Middle East, and disruption of the supply chain at the top of their risk list.

“CFOs across Europe are entering the second half of 2026 with a noticeably more cautious outlook,” said Richard Muschamp, Deloitte EMEA CFO program leader, attributing their pessimism to “a more challenging operating environment.” EY’s CEO Outlook found similar concerns, with 60% of these respondents citing geopolitical tensions as a near-term risk.

“The real question is, What are you doing about it?” said Myles Corson, EY global finance leader. “CFOs need to build resilience into their organization.” In the short term, that means localizing the supply chain, with a focus on energy security and energy pricing. “Leaders are increasingly prioritizing resilience, productivity and cost discipline over expansion and risk-taking” he said.

According to the Deloitte survey, only 26% of CFOs expect to increase capital expenditures over the next 12 months, and 36% anticipate workforce reduction. Consumer goods sectors, impacted by the slowdown of demand, are at the forefront of the workforce adjustment. Unilever PLC declared a hiring freeze that would last at least three months. In Germany, luxury car maker Porsche AG announced one in five job cuts by 2035, and Deutsche Lufthansa AG said it will eliminate 4,000 white-collar roles by 2030.

In France, executives at the industrial engineering firm Fives Group see no immediate need to downsize. Defense and aeronautic clients, warehouses in need of automatization, industries looking for decarbonization, keep Fives busy. Still “10% of our activities have been impacted,” said Suresh Abye, the finance director. “We are very vigilant about our costs structure. In that sector we stopped recruiting and transferred some employees to different activities.”

Fives has clients in a dozen countries, including France, Germany, Italy, China, Japan, and America. “Compared to America and Asia, Europe is the most impacted by inflation, unemployment, and tepid demand,” added Abye. “The regulatory framework is too laborious and there is no policy favoring local producers.”

Nevertheless, Europe also has a few tricks up its sleeve. Corson highlighted the “quality of its talent pool, the diversity of the market, and its focus on sustainability.”

To take full advantage of these strengths, the EY finance leader suggested maintaining investments in artificial intelligence. “Companies will be able to identify where opportunities are, they will adjust quicker and be able to repurpose their people” said Corson, an eager advocate of cost optimization.

Caroline Crosdale is a contributing writer to Global Finance.  

Source link

Central America’s Trade Squeeze | Global Finance Magazine

Deeper integration could attract more nearshoring, but governments will have to step up, too.

This article appears in the October issue of Global Finance Magazine.

With Panama joining Mercosur and Costa Rica wrapping up negotiations to join the Trans-Pacific Partnership, the rest of Spanish-speaking Central America risks being left behind.

Regional integration efforts have hitherto focused on custom unions, stock market interoperability, the Central American Integration System (SICA), the Central American Parliament, and the Central American Free Trade Agreement (FAUCA). 

“Panama’s accession to Mercosur as an associate state creates competitive pressure on the rest of Central America,” said Costa Rica-based financial analyst Daniel Suchar. “This could divert foreign direct investment that traditionally viewed Central America as a gateway to the Americas, forcing the other countries in the region to accelerate their own trade agreements to avoid falling behind.”

As a Mercosur member, Panama gains access to a market of 260 million people as well as value chains in Brazil, Argentina, and Uruguay, notably in logistics, financial services, and agribusiness. This opens the door to negotiations for a Central American bloc to join Mercosur, using Panama as a bridge.

“From a business perspective, the more connected, competitive, and open to trade Central America is, the greater the possibilities for developing regional value chains and attracting investment,” said Rosmer Jurado, president of the Union of Panamanian Industrialists.

Daniel Suchar Zomer,
Financial Analyst

Since last year, talk of a renegotiation of the Dominican Republic-Central America-United States Free Trade Agreement (CAFTA-DR) has been circulating among governments in the region. Should talks begin—the Dominican Republic is pushing hard for a trade deal—they would likely include proposals for further integration and increased rules and regulations. 

“A new agreement would be expected to include chapters on the digital economy, SMEs, resilient supply chains, and more stringent labor and environmental standards,” said Suchar. “A modernized CAFTA-DR should also address trade facilitation and regional cumulation of origin so that Central America can sell as a bloc and not as six separate countries.”

Opportunities in Nearshoring

Central America remains a diverse region, however, both politically and economically, which makes further integration challenging. Nicaragua is in danger of being frozen out of US trade after effectively banning elections, and Costa Rica has historically prioritized market diversification over Central American integration. Forging closer ties with the U.K. is part of its strategy to insert itself into high-value global production chains, particularly in medical devices, services, and technology.

The future of the Northern Triangle states—Guatemala, Honduras and El Salvador—is likely to be conditioned by their capacity to attract nearshoring and reduce non-trade costs. If they improve legal security, infrastructure, and energy, Suchar said, they can position themselves as alternatives for light manufacturing and textiles for companies leaving Asia. 

Nearshoring has been hailed as the region’s magic bullet; a 2024 report by the Center for Strategic and International Studies suggested that U.S. nearshoring alone could add at least $3.3 billion a year to Central American exports. But this is where governments will have to step up, Jurado noted. “Central America can take advantage of nearshoring,” he said, “but the opportunity will not automatically arise simply because of our location. The region must transform its proximity to the U.S. and its strategic position into concrete advantages: better infrastructure, lower logistics costs, specialized talent, competitive energy, trade facilitation, and clear rules for investment.”

Trade agreements, supply chain conditions, and geopolitical risk will all play a role. “Trade agreements are no longer just about tariffs,” said Suchar. “They focus on supply chain resilience, ESG standards, and geopolitics.”

Nic Wirtz is a contributing writer based in Guatemala.

Source link

Revolut’s CEO Says US Banks Are ‘Out of Step’ With Global Consumers | Global Finance Magazine Revolut US Bank Expansion: CEO Cetin Duransoy Interview

Home Banking Revolut’s CEO Says US Banks Are ‘Out of Step’ With Global Consumers

Revolut US CEO Cetin Duransoy reveals plans to target globally minded and “underbanked” Americans as it builds toward becoming a primary bank.

After receiving conditional approval from the U.S. Office of the Comptroller of the Currency for a national bank charter, Revolut Technologies Inc. appears ready to launch a full-scale challenge to traditional banks and fintechs in the United States.

After relatively quick growth in France, Spain, and Italy, Revolut aims to bring its superapp model to the U.S., where it doesn’t exist in quite the same form.

Revolut’s U.S. CEO, Cetin Duransoy, who has held senior roles at Raisin, Fundbox, Visa, and Capital One, spoke with Global Finance about Revolut’s plans for the American market. 

Global Finance: In the US, banks, fintechs, brokerages, travel products and payment apps are mostly separate. Does that surprise you? Do you see a genuine hole in the U.S. market for a company that combines all those relationships in one place?

Duransoy: It’s not surprising, given how complex these products are and how crowded and fragmented the U.S. market is. Layer on the regulatory process, and combining all these product suites—banking, brokerage, FX, crypto, travel, and more—into a single company or app becomes genuinely difficult and, for most companies, not worth the effort.

We believe you need a genuinely differentiated product to succeed in this market, and we have identified an opportunity here. By bringing all these products into one platform, we can remove the friction customers typically experience when cobbling together services from multiple providers.

GF: People often say, “The U.S. banking market is different.” Different how, exactly? And how might those differences affect Revolut?

Duransoy: The US’s fragmented, charter-based regulation can be more cumbersome than the EU’s passporting model, and U.S. customers tend to rely more on credit than their European counterparts. But the U.S. provides certain advantages, including the U.S. card network and interchange system, which subsidize rewards; FDIC insurance; and consumer-protection laws, which create a trust threshold.

Our broad product offering, 80-million-user global network, and strong global brand allow U.S. to cater to the distinct challenges of the U.S. market and understand the challenges of U.S. distribution costs. By obtaining a national bank charter, we will be on par with traditional banks, with direct Fedwire/ACH access and lending capability.

GF: When Revolut enters the U.S. market more aggressively, should Americans expect something close to the European Revolut experience—or will the U.S. product necessarily look much more like a traditional American bank competing on deposits, credit cards and lending?

Duransoy: We are always focused on product-market fit for our customers, and the U.S. will be no different. We’ve publicly shared that we will bring the best of what Revolut offers and provide the products U.S. customers want most, including checking accounts, credit cards, installment loans, FX, and stablecoins. We’ll continue innovating to deliver a distinct, more productive experience for U.S. customers.

GF: One of the things that makes Revolut unusual in Europe is that it sits at the intersection of finance, travel and lifestyle. Is that model central to how you think about the US, or is America more of a banking opportunity?

Duransoy: Yes. Combining our lifestyle products with the financial services that have made Revolut so popular remains central to our thinking. And they’re a key differentiator in many of our markets. We expect these offerings to help make us a top-of-wallet card and strengthen customer retention.

GF: Why should someone with Chase, Amex, Venmo, Robinhood, and a good travel card move meaningful parts of their financial life to Revolut? What can you offer that those companies, individually or collectively, do not?

Duransoy: We recognize that inertia is a strong force when it comes to financial services and that a customer’s bank holds critical parts of their financial life, such as their mortgage or direct deposit.

What we offer is the ability to consolidate multiple products and services into a single interface and remove the friction our customers find frustrating with other services. Revolut’s broad-based platform allows customers to seamlessly access multi-currency spending without foreign transaction fees, instant global P2P, a combined debit/credit product, budgeting, digital assets, and investing, all without transferring funds between platforms or managing multiple accounts. That’s especially valuable for people who travel internationally, have cross-border family ties, or are underserved by traditional credit underwriting.

GF: Which types of lending will Revolut prioritize in the US?

Duransoy: We intend to initially prioritize unsecured and secured credit cards and installment loans.

GF: What does Revolut understand about the consumer relationship that you think many American banks and fintechs still lack?

Duransoy: We treat our global app as the product. We iterate quickly, aim for gamified engagement, and offer frequent feature releases, in contrast to most U.S. bank apps, which have slower release cycles.

We also build for financial lives that span borders and currencies, rather than assuming a single-currency, single-country customer. American banks were largely built for a domestic customer, and that assumption is increasingly out of step with a more mobile, globally connected population.

GF: Do you think Revolut is underestimated in the US? If so, why? Among those who are aware, what do people in the U.S. most commonly misunderstand about Revolut right now?

Duransoy: “Underestimated” is probably right now, largely because our independent U.S. bank doesn’t exist yet. So we’re still seen as a “European neobank” by most Americans. That undersells what we’ll be once we have a full national charter, FDIC insurance, and our full lending capabilities live.

The most common misunderstanding among those who do know the brand is that we’re simply a fintech or a travel debit card, rather than a company with an 80-million-user global base—including 1.4M in the US—and banking licenses now spanning the UK, France, Australia, Mexico, and more.

GF: Are you coming to the U.S. to compete for a small slice of the market, or do you ultimately believe Revolut can change what Americans expect from a bank?

Duransoy: In the US, our near-term goal is to compete for market share. No new entrant can reshape what an entire country expects from a bank on day one. That takes years of trust-building, especially post-charter, when FDIC insurance and regulatory scrutiny are new territory for us.

What we’re looking to do is win the demographics best suited to us, namely the internationally minded, underbanked-by-incumbents, and digitally native users.

GF: On the corporate side, what are Revolut’s corporate banking plans?

Duransoy: Revolut Business exists—and is a core focus for us—in the U.S. We expect this to continue and are excited to launch merchant acquiring within the first years of becoming a bank.

GF: If we revisit this in three years, what would need to be true for you to say that Revolut has successfully become a major U.S. bank?

Duransoy: Within three years, we expect to be a fully operating bank with real momentum. We won’t share specific customer or product numbers today, but we’re building for scale and a sizable U.S. customer base that treats us as their primary bank, not a secondary account. That’s the bar we’re setting for ourselves.

Source link