After federal subpoenas, Mark Walter tapped a Magic Johnson-linked firm for billions in loans
In February, after getting served with subpoenas in a federal criminal investigation, the billionaire sports mogul Mark Walter’s insurance companies abruptly stopped lending to him.
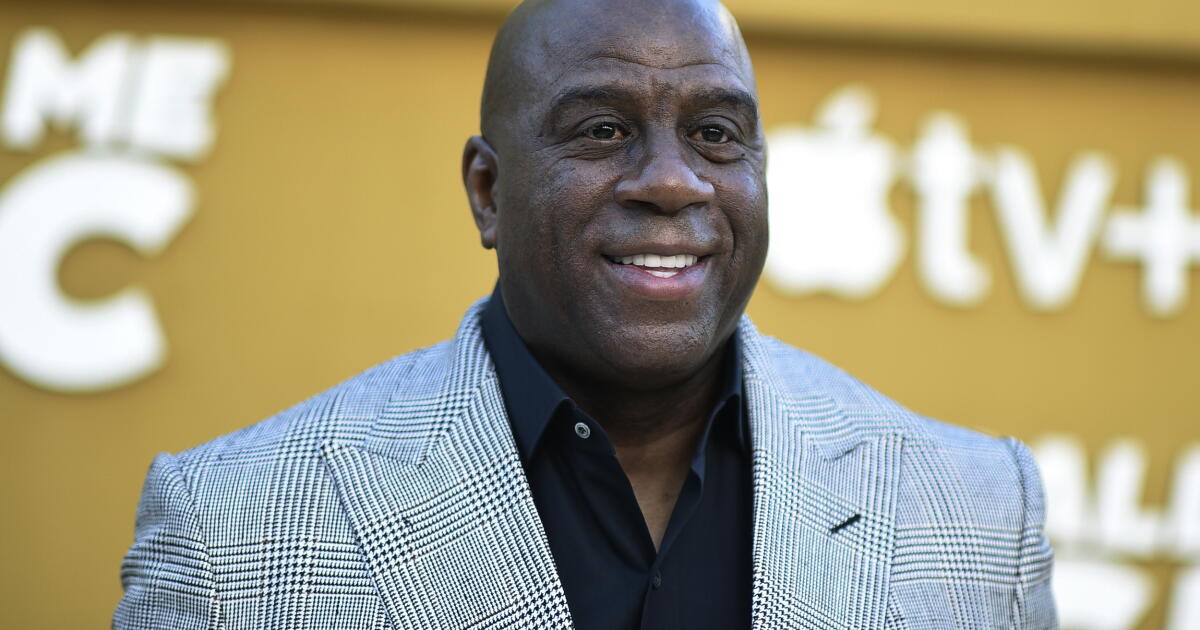
But within weeks, new loans started rolling in from a different source: a financial firm whose owners include his business protege, basketball legend Earvin “Magic” Johnson.
Amistad Financial Group, a holding company that counts Johnson as a board member and minority shareholder, loaned about $1.26 billion to Walter’s companies between March and June of this year, according to a Bloomberg News review of business records and a person with knowledge of the activity who asked not to be identified discussing sensitive matters. Another $1.06 billion went to intermediaries that routinely serve as conduits for loans to Walter.
The combined $2.31 billion of lending, which hasn’t been reported previously, highlights the way Walter relies on debt to fund his business empire, and Amistad’s role. Even before this year, the firm’s insurance units had provided billions of dollars of loans to Walter affiliates, filings show. It also acted as an intermediary to help him tap loans from his own insurers, Bloomberg reported previously – transactions that are now part of the federal investigation.
Walter himself owns a single-digit voting stake in Amistad but doesn’t control it, participate in its management or sit on its board, according to a person familiar with its operations.
Representatives for Walter’s TWG Global holding company and for Johnson did not respond to messages seeking comment.
A former point guard who led the Los Angeles Lakers to five National Basketball Association championships, Johnson has described Walter as a business mentor. They have done deals with each other for more than a decade, including Johnson’s participation in the Walter-led purchase of the Los Angeles Dodgers baseball team. Johnson doesn’t serve on Amistad’s three-person executive committee, and it’s unclear whether he was involved in or aware of the lending decisions. Some of Amistad’s insurance units are led by Eric Holoman, Johnson’s former business manager.
The federal investigation, being pursued in parallel by the U.S. Department of Justice and the Securities and Exchange Commission, focuses on Walter’s insurance companies’ failure to disclose that more than $20 billion of loans on their books went to his other businesses.
The recent lending came from two Amistad subsidiaries, Equitrust Life Insurance Co. and Heritage Life Insurance Co. It’s unclear whether Amistad executives were aware of the investigation when the loans were made. Walter’s insurers disclosed the subpoena in a regulatory filing on June 26, but the filing did not get much attention until Bloomberg News reported on it in July. Information about lending activity after June 30 won’t be disclosed until next month.
Walter is now scrambling to reduce debts to his own insurance companies, Delaware Life Insurance Co. and Clear Spring Life and Annuity Co., in part to assuage concerns from ratings agencies about the scale of affiliated lending. He has agreed to sell the Lakers at a $12.5 billion valuation to free up cash and proposed a $6.5 billion debt swap with Delaware Life. This week, the insurer said it had regulatory approval to proceed with part of that, swapping $3.8 billion.
Because he doesn’t legally control Amistad, Walter is under no such pressure to reduce his reliance on its money.
His ties to Amistad are deep. Its official corporate address is the Chicago office suite that houses Walter’s family office. Walter’s financial firm, Guggenheim Partners, serves as an investment manager for both Equitrust and Heritage Life.
Walter’s brother-in-law serves as president of Heritage Life. Walter used to control Equitrust when it was owned by Guggenheim. He sold it to Johnson in 2015, and Johnson sold it to Amistad last year.
Recipients of the new Amistad loans include a company through which Walter holds his stake in used-car seller Carvana Co., and another containing his interest in the Billie Jean King Cup, the women’s tennis competition that he has backed since 2023. The destination for most of the money wasn’t clear from regulatory filings.
New LLCs
The federal investigations revolve around how Walter’s insurers came to lend so much money to his other businesses without disclosing the arrangement to their regulator, the Delaware Department of Insurance, as required. As of the end of last year, the amount of money they had invested in affiliates was $24 billion, or about 45% of the companies’ total invested assets.
Much of the money was routed to loans for newly created limited liability companies with no public profile. These LLCs were created by Amistad and other intermediaries, which in turn sent the money back to Walter.
In January and early February of this year, that lending arrangement continued, with Delaware Life loaning $730 million to newly formed LLCs that then sent the money to Walter’s other businesses, regulatory filings show. That stopped after the U.S. Attorney’s Office in Manhattan sent the grand jury subpoenas.
But in March, Amistad’s Equitrust sent $500 million to 10 LLCs. These borrowers had been formed days earlier by Federico Hermida, a Miami-based executive at ABS Capital Co., a longtime business partner of Walter’s that has often served as an intermediary in deals between Walter and his insurers. In June, Amistad’s Heritage Life sent $303 million to a subset of the Hermida borrowers. A representative of ABS declined to comment.
Heritage Life also sent about $253 million to LLCs set up by two other intermediaries that Walter has used for loans in the past: the real estate firm Bradford Allen and Hudson Trading, both based in Chicago. Representatives of Bradford Allen didn’t respond to requests for comment, and Hudson Trading declined to comment.
The remaining $1.3 billion of loans were made to companies that are known to be part of Walter’s business empire, or that were formed by a Walter employee, or were confirmed by the person with knowledge of the matter.
Most of the loans carried interest rates of 8 percent or more, and were due to mature in September or earlier. The insurers won’t have to disclose whether those loans were repaid, extended or replaced with new debt until they file their next quarterly financial reports next month.
Despite the borrowing from Amistad, Walter had not significantly reduced his debt to his own insurance companies by June 30, the date of the most recent regulatory filings. After climbing from $24 billion to $25 billion through March, the amount of affiliated investments dropped to about $24 billion as of June.
Mider and Li write for Bloomberg.