loan

First Business outlines ~10% annual loan growth and sees NIM staying above 3.60%–3.65% long-term range (NASDAQ:FBIZ)

Earnings Call Insights: First Business Financial Services (FBIZ) Q3 2026

Management view

  • “We produced record pretax pre-provision and bottom line earnings” (President, CEO & Director David Seiler), and “these outcomes were driven by strong operating fundamentals as reflected in pretax pre-provision earnings that grew 13% year-over-year and

Seeking Alpha’s Disclaimer: This article was automatically generated by an AI tool based on content available on the Seeking Alpha website, and has not been curated or reviewed by humans. Due to inherent limitations in using AI-based tools, the accuracy, completeness, or timeliness of such articles cannot be guaranteed. This article is intended for informational purposes only. Seeking Alpha does not take account of your objectives or your financial situation and does not offer any personalized investment advice. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank.

Source link

California Prop. 37: $25 billion down payment assistance explained

Buying a home in California requires a colossal amount of money — and coming up with a 20% cash down payment of $180,000 for a median price home is a staggering hurdle for many would-be buyers.

That down payment amount is based on the statewide median $900,000 price tag for a house, according to recent data from the California Assn. of Realtors. In Los Angeles County, the median price for a single-family home is $935,000. In Orange County, it’s $1.5 million.

Proposition 37 on the Nov. 3 ballot would allow the state to amass a $25 billion down payment assistance program for middle-class households. For perspective on the enormity of the measure before voters, one of the state’s existing down payment programs, California Dream For All, launched several years ago with $500 million, just 2% of the funding involved in Proposition 37.

The ballot measure would allow qualified prospective homebuyers to borrow up to 17% of the sales price of a new home, contributing 3% of the down payment from their own funds.

The program would not be funded by taxpayers, but instead by the interest charged to borrowers on their down payment loans, also referred to as second mortgages. The measure has garnered widespread support, including from Gov. Gavin Newsom, statewide unions and mayors from Santa Monica to San José.

“Prop. 37 is a historic opportunity to expand homeownership opportunities for generations of working families — at zero cost or risk to taxpayers,” Newsom said in a statement.

But Proposition 37 carries a significant caveat: Any home purchased through the program must be new construction, which could limit its potential reach because of the high cost of building, some critics said.

Also, the proposition does not spell out the terms or interest rates on the loans, which would be worked out if the measure is approved. And some have questioned whether there will be sufficiently robust interest from investors to buy the state-issued bonds that will be used to fund the down payment loans.

The concept of down payment assistance is not new. Cities and states, including California, have long offered such programs to low- and middle-income homeowners, either in the form of loans or grants, and there are reportedly more than 2,700 such programs across the country.

Nevada, Connecticut, Massachusetts and New York all have programs to help homebuyers afford a down payment. Since 2021, New York has dispersed $70 million in down payment assistance. In Massachusetts, more than $146 million has been doled out in down payment help to homebuyers since 2020.

How the program would work

Under Proposition 37, down payment loans would work like any other, and would carry an interest rate and payback period — all of which would be determined by the California Housing Finance Agency.

To qualify, borrowers would need to have lived in the state for at least a year and earn no more than 200% of the local median income; in Los Angeles County, for example, that equates to a family of four earning no more than $216,200 a year.

Borrowers don’t have to be first-time homebuyers, which is often a requirement of down payment aid programs. But they would need to live in the home.

The program would restrict the price of qualifying homes, depending on the county where someone is trying to buy. A general estimate, though, is that would-be homebuyers would be limited to houses costing between $1 million and $1.5 million and the homes, more importantly, would need to be new construction.

While Proposition 37 has little opposition, and is supported by unions, chambers of commerce and organizations representing builders, the League of Women Voters opposes the ballot measure, concerned it would saddle residents with too much debt and that the terms of these loans are opaque, the details worked out only after the vote.

New homes only

Only buyers of newly-built homes would be eligible for these loans. That could include existing commercial buildings that had been converted into homes, such as condos or townhomes.

This provision is uncommon as many existing down payment assistance programs don’t strictly limit the type of home someone can buy — only the sale price. Bob Hertzberg, former Senate Majority Leader and the architect of the proposal, said he wanted Proposition 37 to spur new construction.

“The problem is we have to increase supply,” Hertzberg said. The shortage of homes in the state is estimated to range anywhere from 840,000 to upwards of 3 million.

By creating more demand for new homes, he said, the hope is that builders will respond en masse.

But some groups are wary of this logic. One analysis, funded by the Proposition 37 campaign, estimated that this program could result in the building of 190,000 homes in the state, although the report’s author said it was “impossible to know” the true number given the various factors that impact housing.

Matthew Lewis, director of communications for California YIMBY, an organization that advocates making it easier and cheaper to build homes, said high prices make it clear that the demand for homes already exists and that Proposition 37 does little to address a bigger issue: the cost of building.

“In concept, [Proposition 37 is] a great idea,” Lewis said. “The thing we’re concerned about is, California is still way behind on its housing production goals, so there’s the risk of an unintended consequence of instead of having 10 people bidding on a house, now you’ve given a couple folks down payment assistance, and so there’s now 12 people bidding on the same house.”

To drive builders to construct eligible homes, the measure would allow them to opt into a “qualified builder” option. As long as they adhere to price caps, agree to certain labor requirements and fix repairs that arise, they’re protected from lawsuits from buyers concerning defects 10 years after construction of the home.

Homebuilders say even given some relief from litigation, they aren’t sure Proposition 37 would push construction into overdrive.

“There are so many more things the state, city and county could do to help add more supply [of homes],” said Paul Schon, a developer who builds apartments in L.A. County. He said tackling permitting times and red tape involved in building would have a greater impact. “This is minor,” he said.

Interest rates could be a tough sell

Many down payment assistance programs offer interest-free loans to homebuyers, including an existing program run by CalHFA.

But in order to be self-funding, the fixed-rate loans offered through Proposition 37 would carry interest. If passed, the state would issue revenue bonds, selling them to investors and using that money to issue loans to homebuyers. The investors are repaid with the interest paid on the loans.

According to the Legislative Analyst’s Office, CalHFA would decide the total amount of bonds to issue and over what period of time.

Revenue bonds are generally viewed as riskier than other types of government bonds, in part because they’re backed by the promise of revenue from a specific project — in this case, payment by individual borrowers. That means interest rates on these loans could be higher than borrowers might like or be able to afford.

Hertzberg said he’s talked to investors who may be willing to buy these bonds at cheaper rates, given the crushing issue the funding is trying to solve. This would keep interest rates down for borrowers. He said he’s appealing to foundations and socially-minded tech leaders.

One of the biggest financial backers of the measure is the political nonprofit Building a Better California, which has been fighting the billionaire’s tax with help from wealthy donors, including Google co-founder Sergey Brin.

Hertzberg, for his part, refused to name any organization or person who may be interested in buying the bonds that would fund this program.

This article is part of The Times’ equity reporting initiative, funded by the James Irvine Foundation, exploring the challenges facing low-income workers and the efforts being made to address California’s economic divide.

Source link

After federal subpoenas, Mark Walter tapped a Magic Johnson-linked firm for billions in loans

In February, after getting served with subpoenas in a federal criminal investigation, the billionaire sports mogul Mark Walter’s insurance companies abruptly stopped lending to him.

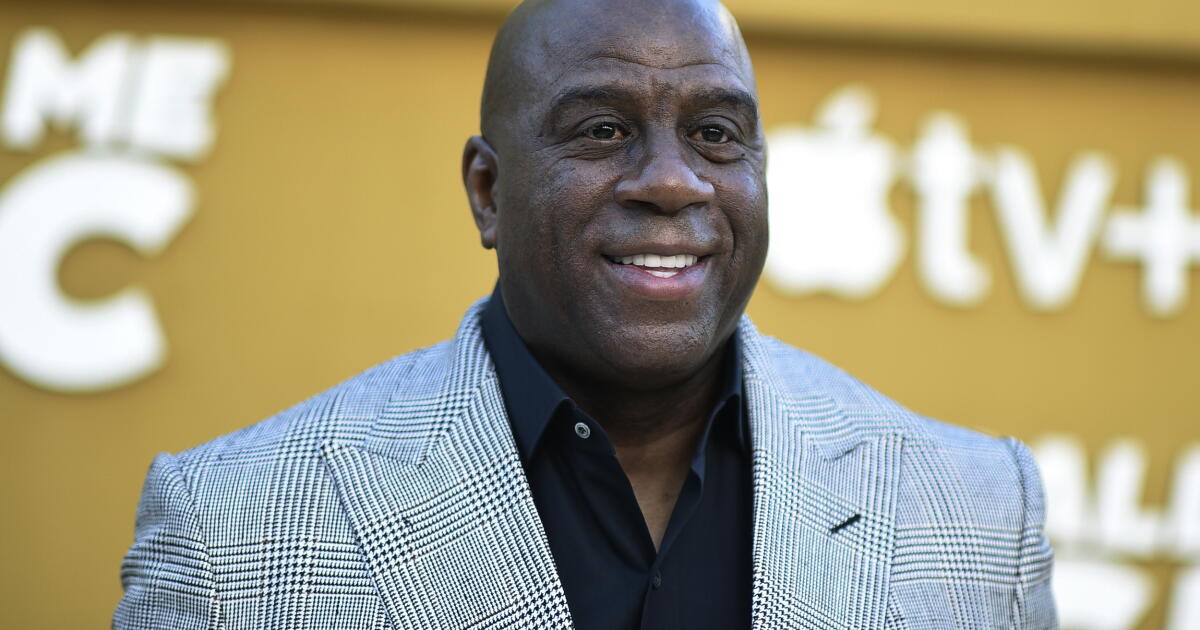
But within weeks, new loans started rolling in from a different source: a financial firm whose owners include his business protege, basketball legend Earvin “Magic” Johnson.

Amistad Financial Group, a holding company that counts Johnson as a board member and minority shareholder, loaned about $1.26 billion to Walter’s companies between March and June of this year, according to a Bloomberg News review of business records and a person with knowledge of the activity who asked not to be identified discussing sensitive matters. Another $1.06 billion went to intermediaries that routinely serve as conduits for loans to Walter.

The combined $2.31 billion of lending, which hasn’t been reported previously, highlights the way Walter relies on debt to fund his business empire, and Amistad’s role. Even before this year, the firm’s insurance units had provided billions of dollars of loans to Walter affiliates, filings show. It also acted as an intermediary to help him tap loans from his own insurers, Bloomberg reported previously – transactions that are now part of the federal investigation.

Walter himself owns a single-digit voting stake in Amistad but doesn’t control it, participate in its management or sit on its board, according to a person familiar with its operations.

Representatives for Walter’s TWG Global holding company and for Johnson did not respond to messages seeking comment.

A former point guard who led the Los Angeles Lakers to five National Basketball Association championships, Johnson has described Walter as a business mentor. They have done deals with each other for more than a decade, including Johnson’s participation in the Walter-led purchase of the Los Angeles Dodgers baseball team. Johnson doesn’t serve on Amistad’s three-person executive committee, and it’s unclear whether he was involved in or aware of the lending decisions. Some of Amistad’s insurance units are led by Eric Holoman, Johnson’s former business manager.

The federal investigation, being pursued in parallel by the U.S. Department of Justice and the Securities and Exchange Commission, focuses on Walter’s insurance companies’ failure to disclose that more than $20 billion of loans on their books went to his other businesses.

The recent lending came from two Amistad subsidiaries, Equitrust Life Insurance Co. and Heritage Life Insurance Co. It’s unclear whether Amistad executives were aware of the investigation when the loans were made. Walter’s insurers disclosed the subpoena in a regulatory filing on June 26, but the filing did not get much attention until Bloomberg News reported on it in July. Information about lending activity after June 30 won’t be disclosed until next month.

Walter is now scrambling to reduce debts to his own insurance companies, Delaware Life Insurance Co. and Clear Spring Life and Annuity Co., in part to assuage concerns from ratings agencies about the scale of affiliated lending. He has agreed to sell the Lakers at a $12.5 billion valuation to free up cash and proposed a $6.5 billion debt swap with Delaware Life. This week, the insurer said it had regulatory approval to proceed with part of that, swapping $3.8 billion.

Because he doesn’t legally control Amistad, Walter is under no such pressure to reduce his reliance on its money.

His ties to Amistad are deep. Its official corporate address is the Chicago office suite that houses Walter’s family office. Walter’s financial firm, Guggenheim Partners, serves as an investment manager for both Equitrust and Heritage Life.

Walter’s brother-in-law serves as president of Heritage Life. Walter used to control Equitrust when it was owned by Guggenheim. He sold it to Johnson in 2015, and Johnson sold it to Amistad last year.

Recipients of the new Amistad loans include a company through which Walter holds his stake in used-car seller Carvana Co., and another containing his interest in the Billie Jean King Cup, the women’s tennis competition that he has backed since 2023. The destination for most of the money wasn’t clear from regulatory filings.

New LLCs

The federal investigations revolve around how Walter’s insurers came to lend so much money to his other businesses without disclosing the arrangement to their regulator, the Delaware Department of Insurance, as required. As of the end of last year, the amount of money they had invested in affiliates was $24 billion, or about 45% of the companies’ total invested assets.

Much of the money was routed to loans for newly created limited liability companies with no public profile. These LLCs were created by Amistad and other intermediaries, which in turn sent the money back to Walter.

In January and early February of this year, that lending arrangement continued, with Delaware Life loaning $730 million to newly formed LLCs that then sent the money to Walter’s other businesses, regulatory filings show. That stopped after the U.S. Attorney’s Office in Manhattan sent the grand jury subpoenas.

But in March, Amistad’s Equitrust sent $500 million to 10 LLCs. These borrowers had been formed days earlier by Federico Hermida, a Miami-based executive at ABS Capital Co., a longtime business partner of Walter’s that has often served as an intermediary in deals between Walter and his insurers. In June, Amistad’s Heritage Life sent $303 million to a subset of the Hermida borrowers. A representative of ABS declined to comment.

Heritage Life also sent about $253 million to LLCs set up by two other intermediaries that Walter has used for loans in the past: the real estate firm Bradford Allen and Hudson Trading, both based in Chicago. Representatives of Bradford Allen didn’t respond to requests for comment, and Hudson Trading declined to comment.

The remaining $1.3 billion of loans were made to companies that are known to be part of Walter’s business empire, or that were formed by a Walter employee, or were confirmed by the person with knowledge of the matter.

Most of the loans carried interest rates of 8 percent or more, and were due to mature in September or earlier. The insurers won’t have to disclose whether those loans were repaid, extended or replaced with new debt until they file their next quarterly financial reports next month.

Despite the borrowing from Amistad, Walter had not significantly reduced his debt to his own insurance companies by June 30, the date of the most recent regulatory filings. After climbing from $24 billion to $25 billion through March, the amount of affiliated investments dropped to about $24 billion as of June.

Mider and Li write for Bloomberg.

Source link

First Hawaiian outlines 1%-2% full-year loan growth as it expects Q4 NIM of 3.34%-3.35% (NASDAQ:FHB)

Earnings Call Insights: First Hawaiian (FHB) Q3 2026

Management view

  • “I’ll start by providing an update on the acquisition. … we’re making good progress obtaining the necessary regulatory and shareholder approvals… Integration planning is going well, and we continue to expect to close this

Seeking Alpha’s Disclaimer: This article was automatically generated by an AI tool based on content available on the Seeking Alpha website, and has not been curated or reviewed by humans. Due to inherent limitations in using AI-based tools, the accuracy, completeness, or timeliness of such articles cannot be guaranteed. This article is intended for informational purposes only. Seeking Alpha does not take account of your objectives or your financial situation and does not offer any personalized investment advice. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank.

Source link

Leo Walta scores for LAFC in draw with New York City

Andres Perea scored a goal and Matt Freese had two saves for New York City FC on Saturday night in a 1-1 tie with LAFC.

Perea slammed home a header off a corner kick played in by Nicolás Fernández to make it 1-1 in the 59th minute.

NYCFC (8-12-10) is winless, with three losses, in its last five games.

Leo Walta, acquired Aug. 31 by LAFC on loan, scored his first career MLS goal in his fourth appearance. The 23-year-old midfielder put away a straightaway free kick from 30 yards out to open the scoring in first-half stoppage time.

Hugo Lloris had three saves for LAFC (12-9-10).

Up next for LAFC: Hosts the Galaxy on Oct. 25.

Source link