fintech

‘Creative’ Laws Underpin LatAm’s Fintech Expansion

Strong regulation and dynamic regulators are helping nurture a fintech boom across the region.

This article appears in the October issue of Global Finance Magazine.

The number of fintech startups in Latin America has grown by 340% over the past six years as these companies take a leading position in areas such as financial inclusion, cross-border payments, and instant payments. 

Nubank reached a milestone in January, becoming the largest private bank in Brazil with over 112 million users, according to the Central Bank of Brazil. The instant payment system Pix now accounts for more than half of transactions in the country and has some 170 million users, with 80% to 95% of the country using the service.

“Creative laws are not always good laws. So you can have very creative regulation that is not necessarily very good regulation,” said Eduardo de Los Heros, legal manager at Bitso, a Mexican cryptocurrency trading service and fintech. “Brazil has very advanced regulation for digital payments, and El Salvador has made Bitcoin its calling card to position itself as the crypto regional hub.”

Brazil, Colombia, and Mexico account for about 57% of all Latin American fintechs, with remittances, loans, and financial management the main segments. In Mexico, the arrival of Mercado Libre and its subsidiary Mercado Pago, as well as Nubank, has forced traditional banks to offer their own digital alternatives.

“Mexico and Brazil, as the biggest economies, are pushing towards regulation. El Salvador is small but dynamic and has a fantastic regulatory sandbox,” said Daniel Leiva, partner at Torres Legal in El Salvador. “Then there are countries that are also pushing forward, like Colombia and Argentina. Argentina is fighting to integrate fintechs into the economy.” 

With a Fintech 2.0 Law due in Mexico, the market is starting to mature as adoption of digital banks and payment schemes increases across the region. Mexico now has over 1,000 fintech companies, second in the region only to Brazil. 

“This famous law has the objective to develop open finance as well as public access to user data of Mexican financial projects,” said de Los Heros, “creating clear regulations for virtual actors, tokenization, and stable coins.”

That would not be a minute too soon, as Mexico’s rapid fintech expansion has outstripped the Comisión Nacional Bancaria y de Valores (CNBV)’s ability to regulate, Leiva said.

De Los Heros does not believe the law will be ready this year; there is no publicly available draft of the law, nor is a draft bill before Congress or the Senate. Yet, speaking at the Fintech Festival 2026 in February, CNBV President Ángel Cabrera claimed that Mexico was technologically ready for Fintech 2.0, adding, “The CNBV’s vision is to build an ecosystem of digitally born entities that generate value where cash still predominates today.” 

Leiva points to El Salvador as another example of dynamism in the industry. 

With one regulator, the National Commission of Digital Assets (CNAD), working in tandem with the Central Bank of El Salvador, the focus has been on neutral laws; CNAD regulates certain types of activities, like crypto, without marrying the law to specific technologies. A broader scope allows for quicker adoption and avoids delays in achieving regulatory consensus on specific blockchain models, for example. This enables distributed technologies and similar models to be regulated more effectively. 


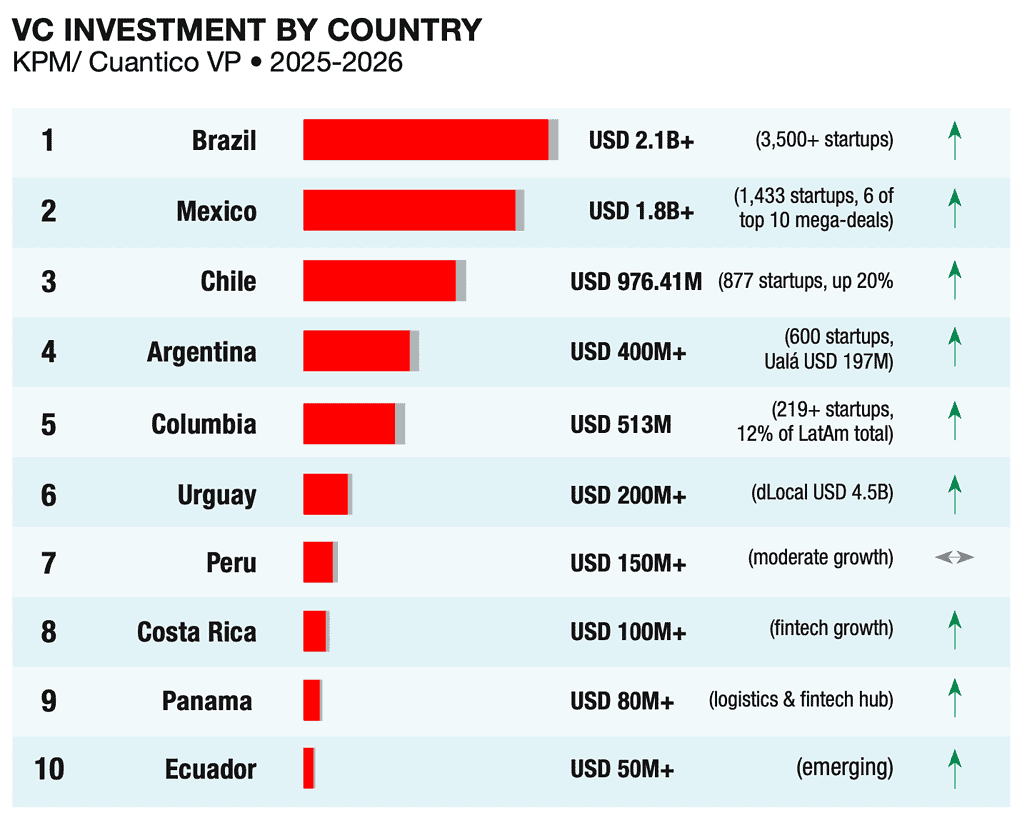
Brazil and Mexico concentrated 78.5% of all regional VC in 2025. Fintech captures 61% of capital. 
Source: KPMG, Cuantico VP, StartupBlink • 2025-2026
(Brazil and Mexico concentrated 78.5% of all regional VC in 2025. Fintech captures 61% of capital.
Source: KPMG, Cuantico VP, StartupBlink • 2025-2026)

From Sandboxes to Standards

Colombia’s instant payment system, Bre-B, was launched by the Banco de la República last October. Bre-B aims to connect traditional banks, fintechs, and digital wallets through a single public digital platform. By August, it had recorded 1.51 billion transactions and more than 35 million users; 171 financial institutions had integrated by then. Those numbers could be even better if the bank had been less passive and restrictive over the past couple of years, according to Leiva. 

Eduardo De Los Heros,
Bitso
Eduardo De Los Heros,
Bitso

That said, Colombia’s fintech sector is at a crossroads, with rapid uptake butting up against a new regulatory framework. The Banco de la República and the Superintendencia Financiera de Colombia have instituted new regulations to protect consumers, ensure financial stability, and combat money laundering. Fintechs now have to adhere to the same standards as traditional banks, including rigorous know-your-customer protocols.

“I am not convinced that excessive regulation is the ideal mechanism for the financial services users,” says de Los Heros. “But in regions like Latin America, where there’s not always advanced banking options, it can be that regulation brings positive effects, at least because it protects users against possible abusive practices by stock markets, financial entities, or virtual service providers.”

Peru’s attempts to integrate banks, fintechs, and users on a single inter-platform payment system under one legislative umbrella are also attracting attention. The Andean nation has “a high index of unbanked people,” de Los Heros said, and in theory, having a unified system with a single platform could speed mass adoption. “We have to see how an interactive interbanking and inter-platform payment system could be adopted region-wise. It’s more important to have an interbanking system that works than an inter-platform system that is not adopted.”

In the medium term, both de Los Heros and Leiva foresee a maturing market with heightened regulatory scrutiny. More regulation does not necessarily mean a more restrictive environment in a region where institutions have been praised for creativity and dynamism, and where central banks responded to the Covid-19 pandemic in ways that avoided the inflationary pressures other countries endured.

Daniel Leiva,
Torres Legal
Daniel Leiva,
Torres Legal

“Powerhouses like Nubank or Mercado Libre didn’t exist 25 years ago, so creating regulation for them is complex,” Leiva said. “I firmly believe the big actors like Nubank will move into other regions. They will go global. We’re going to have to implement new regulatory mechanisms, like allowing a banking license to be used across Central America.”

Latin America can build on its reputation for forward thinking and dynamic legislation, he added.

“Through new mechanisms of payment, like Pix, [Brazil, Mexico, and El Salvador] are the three regional pillars of legislative development,” he said. “Very interesting things are coming, and you could say Latin America is the lungs of fintech laws globally.”

Not everything is rosy, and de Los Heros is particularly concerned with the implications of AI and how to regulate it.

“AI causes me to lose sleep,” he said. “I really doubt that the industry has all the controls needed. To protect financial systems and society against the unmeasured use of AI and its consequences, we might have to start from zero to establish a lot of norms that we haven’t even thought about yet.”

Nic Wirtz is a contributing writer based in Guatemala.
Source link

Arab News | Saudi fintech barq closes $329.5m series A funding round

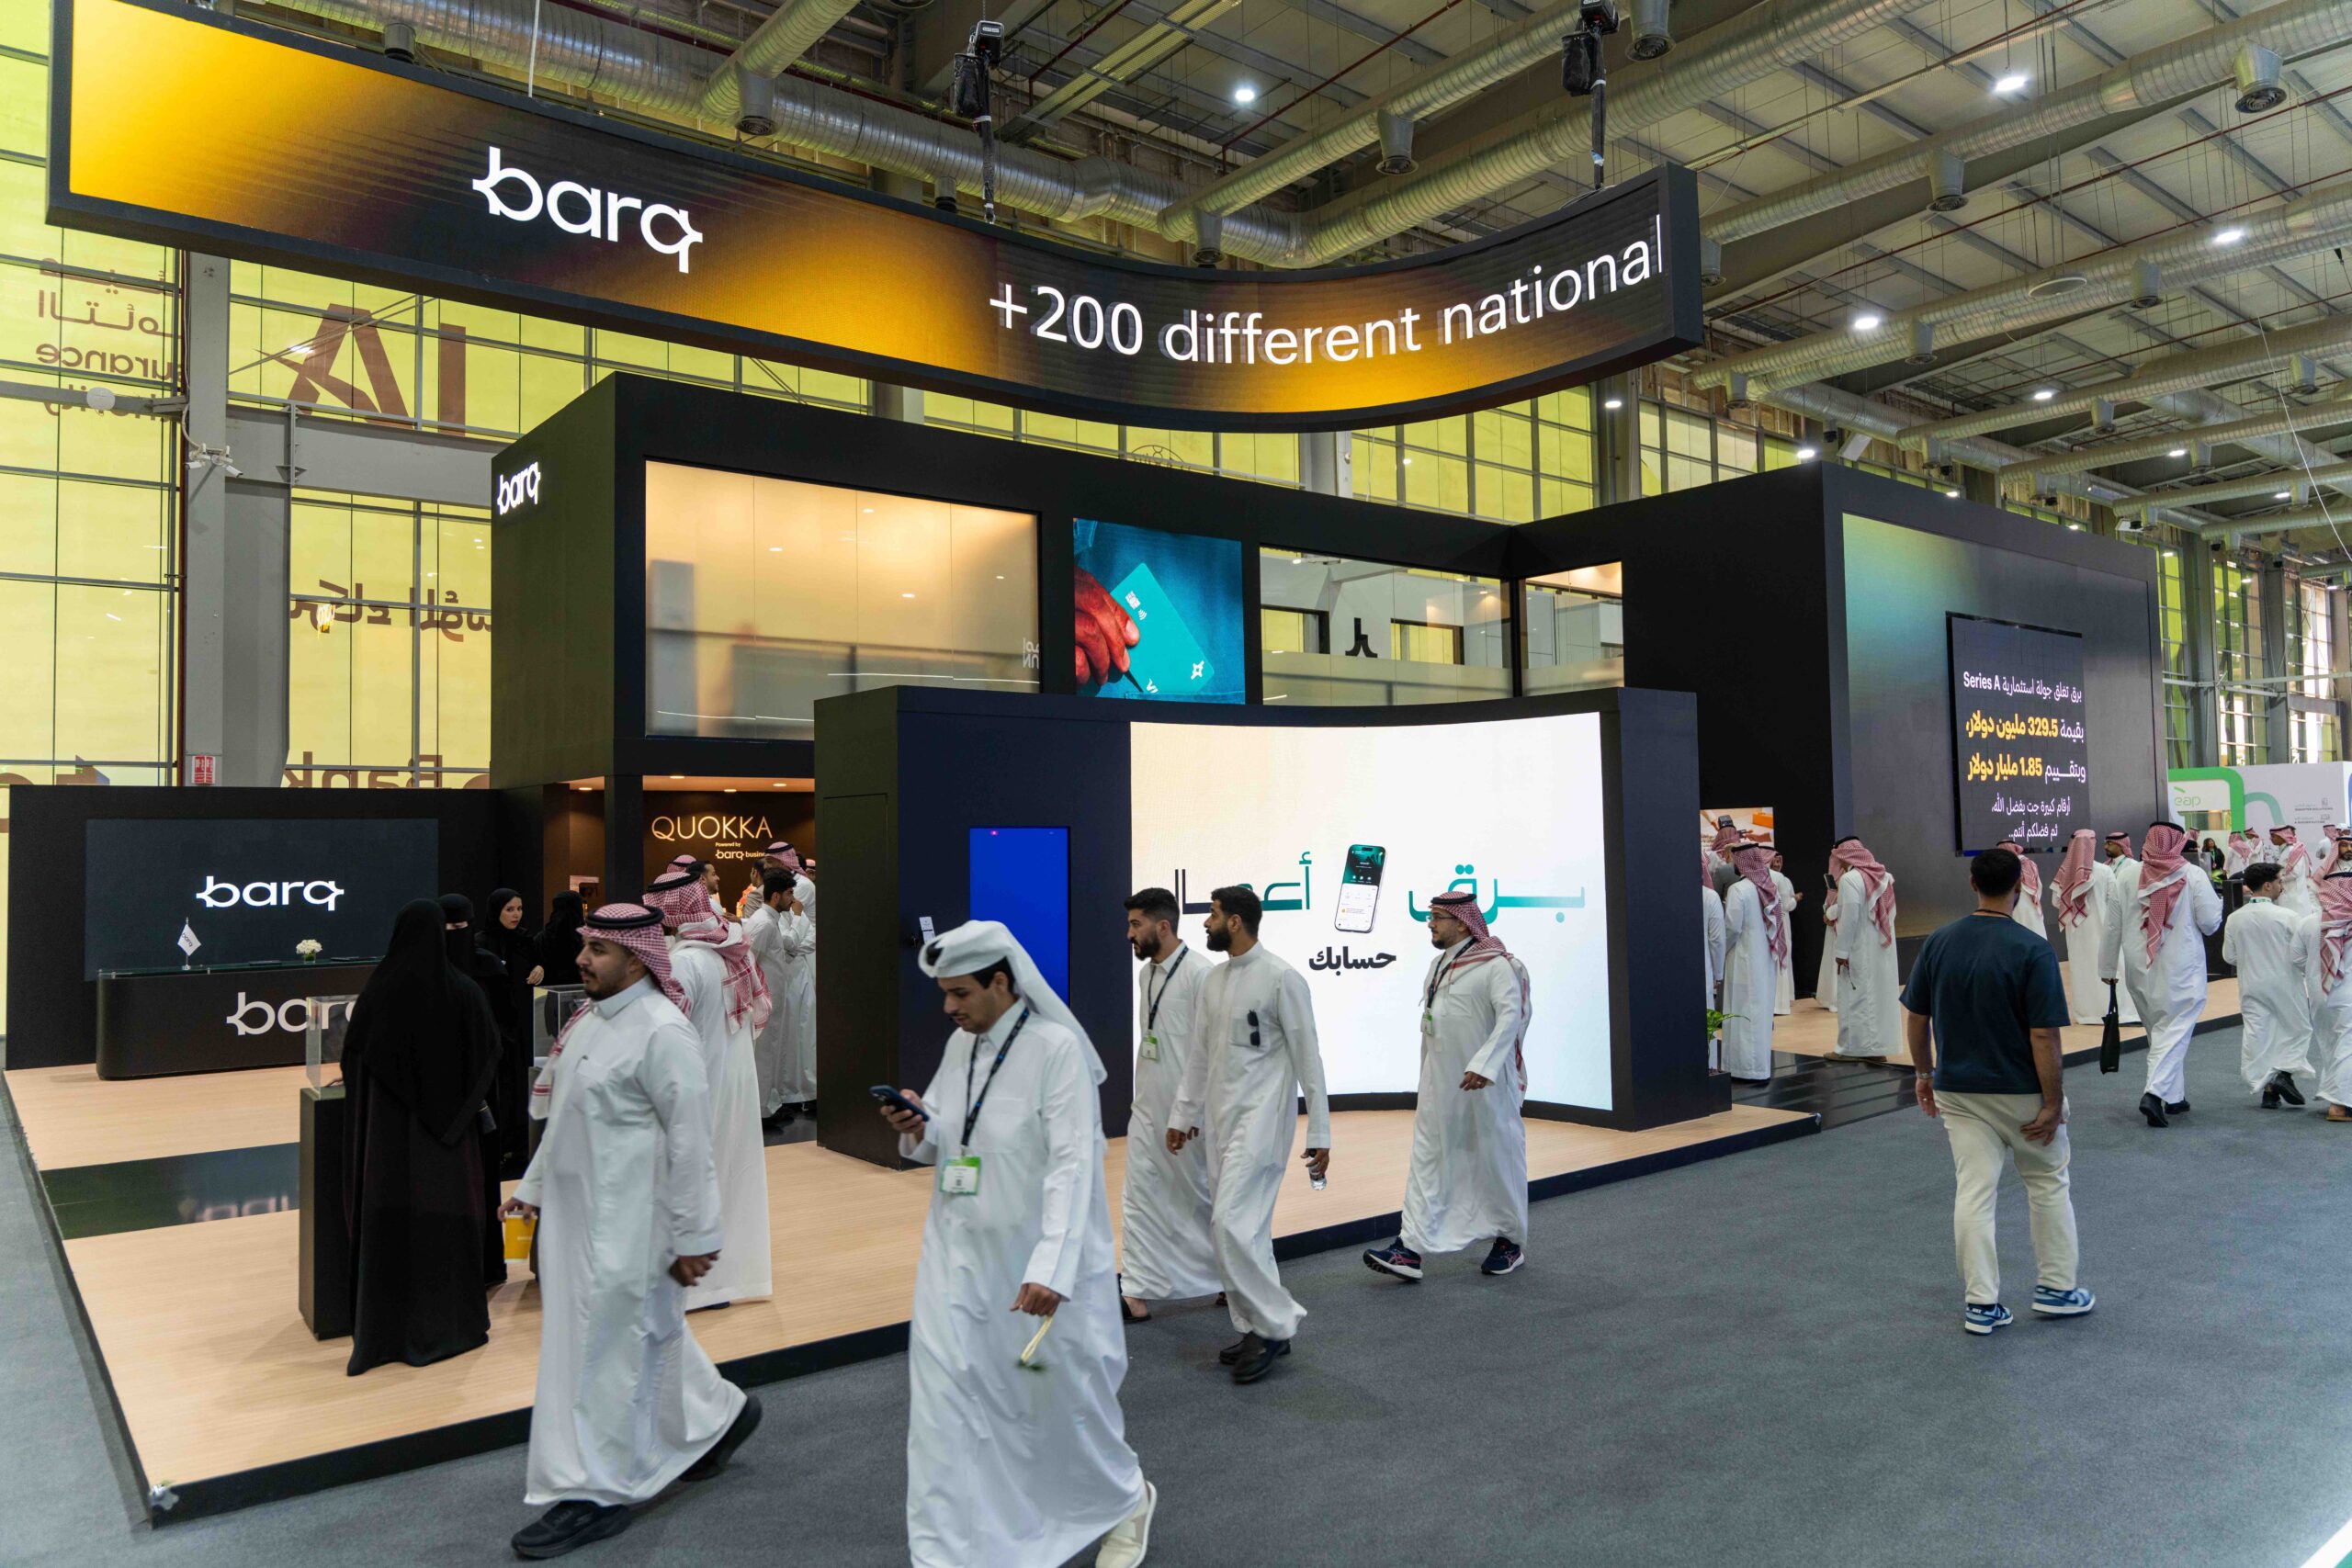
Saudi digital payments company barq announced the close of a series A funding round worth $329.5 million, at a valuation of $1.85 billion, marking a new milestone that reflects the growth the company has achieved since its launch. The funding round cements its position among the fastest-growing fintech companies in Saudi Arabia and the region.

The round saw participation from Noon Investments, Sohar International Bank, and M20 Fund, a step that reflects investor confidence in barq’s trajectory and future potential, and underscores the appeal of the investment opportunities emerging in the fintech sector across the Kingdom and the region.

The round follows a standout growth journey for barq, which has now surpassed 15 million users within two years, from more than 210 nationalities, alongside the expansion of its ecosystem of digital financial services and solutions — reflecting the growing demand for the company’s products and its ability to build a broad user base within a record period of time.

The value of funds processed has also surpassed SR440 billion ($117.2 billion), an indicator that reflects the scale of activity barq has achieved and the widening use of its digital financial services since launch.

Based on its valuation, barq has become one of the fastest companies in the region to reach unicorn status, and among the fastest globally within the fintech sector, reflecting the pace of growth the company has achieved within a short period since its launch.

The funding round will support barq’s next phase of growth, by strengthening operational efficiency, accelerating the development of products and services, investing in new financial and technology solutions, and expanding into new regional and international markets — contributing to delivering a more advanced and accessible digital financial experience for users.

This achievement comes at a time when Saudi Arabia’s fintech sector is undergoing exceptional development, driven by continued progress in financial and digital infrastructure, a supportive regulatory environment, the targets of Saudi Vision 2030, and the Saudi Central Bank’s efforts to advance digital payments and support innovation in financial services.

The close of the round marks a major milestone in barq’s journey, reflecting its ability to move within a short period from a phase of rapid growth to building a broad-scale digital financial platform, underpinned by a growing user base, an increasing volume of operations, and expansion ambitions aimed at strengthening its presence in the fintech sector at both the regional and international levels.

Source link

Latin American Neobanks Take the Next Step

As their customer base grows fast, fintechs across the region are looking to become banks in the full regulatory and economic sense.

This article appears in the September 2026 issue of Global Finance Magazine.

After nearly a decade of explosive growth, Brazil’s fintech industry has crossed a threshold that once looked unthinkable; a digital bank now counts more customers than any of the country’s storied private lenders.

According to recent data from the Central Bank of Brazil, nearly 60% of the nation’s adults now hold an account with Nubank, making it Brazil’s largest private financial institution by customer count, albeit still far from the largest by assets. Similarly, 55% of banked Brazilians primarily identify as customers of a digital bank or fintech, according to research organization Instituto Locomotiva.

“The fintech market has decidedly moved beyond access and into becoming the central piece of the Brazilian banking economy, also from the population’s perspective,” said Álvaro Machado Dias, associate director of Instituto Locomotiva.

The Brazilian experience reflects a broader shift across Latin America. Having secured a competitive customer base, the region’s fintechs are now seeking the licenses, deposits, and balance sheets that could allow them to become the banks they once set out to disrupt.

In Argentina, digital wallets have overtaken every other payment instrument, with 70% of consumers using them over the past six months compared with 52% for cash, according to Mastercard. Nu Mexico reaches roughly 15% of the adult population just seven years after entering the market, while Mercado Pago, the fintech arm of now-Montevideo-headquartered MercadoLibre Inc., now has 83 million monthly active users across eight countries, up 29% over the past year. 

The shift is also changing how consumers transact. Sixty-one percent of Brazilian and 47% of Mexican consumers used a mobile device for their latest retail purchase, according to PYMNTS Intelligence’s Global Digital Shopping Index.

Having crossed that threshold with customers, the fintechs are now moving to the next stage: becoming banks in the full regulatory and economic sense. Nubank agreed in July to acquire Banco Porto Real de Investimentos S/A, enabling it to obtain a Brazilian banking license, while its Mexican unit began operating as a bank last month, becoming the first Mexican popular financial society (SOFIPO) authorized to convert.

Mercado Pago is close behind, with its own application reportedly first in line at Mexico’s banking regulator and an ambition to build the country’s largest digital bank. Mexican fintech Plata secured its license in February, while Argentina’s Ualá Bank SAU already holds a full banking license at home and in Mexico and a financing company license in Colombia.

Why A Banking License?

The economics of the transition are straightforward. As fintechs scale, the limitations of lighter regulatory charters become increasingly binding. Nu Mexico’s SOFIPO status, for example, allows deposit insurance of just 25,000 UDIs (Mexico’s inflation-indexed units of accounts) per client; a full banking license raises that ceiling sixteenfold. Banks can also compete for payroll accounts, held by only about a third of Mexican adults and concentrated largely among four incumbent institutions.

Most important, a banking license gives fintechs access to the deposits that provide the cheapest funding for a growing loan book.

Nu Mexico already holds $5.9 billion in deposits, which makes the ability to gather and deploy them at scale an increasingly important side of its business.

“Once a digital bank holds the same license, follows the same rules, and funds itself the same way, it stops being essentially different from a traditional bank,” said Reginaldo Nogueira, national director of Brazil’s Ibmec business and economics school. “The difference shifts to technology, efficiency, and customer experience.”

Accompanying that strategic shift is a much larger investment commitment. Founder David Vélez paired Nubank’s Mexican license with a projected $4.2 billion investment in the country through 2030.

The fintechs’ current profile marks a striking reversal from where the industry began. A decade ago, they were outsiders challenging Latin America’s established banks to control the region’s customers, branches and balance sheets. Today, they have crossed the most important threshold on the customer side. The next step is to acquire the regulatory privileges and funding advantages that underpin the banking business itself.

Thomas Monteiro is a contributing writer based in Spain.

Source link