fintech

Arab News | Saudi fintech barq closes $329.5m series A funding round

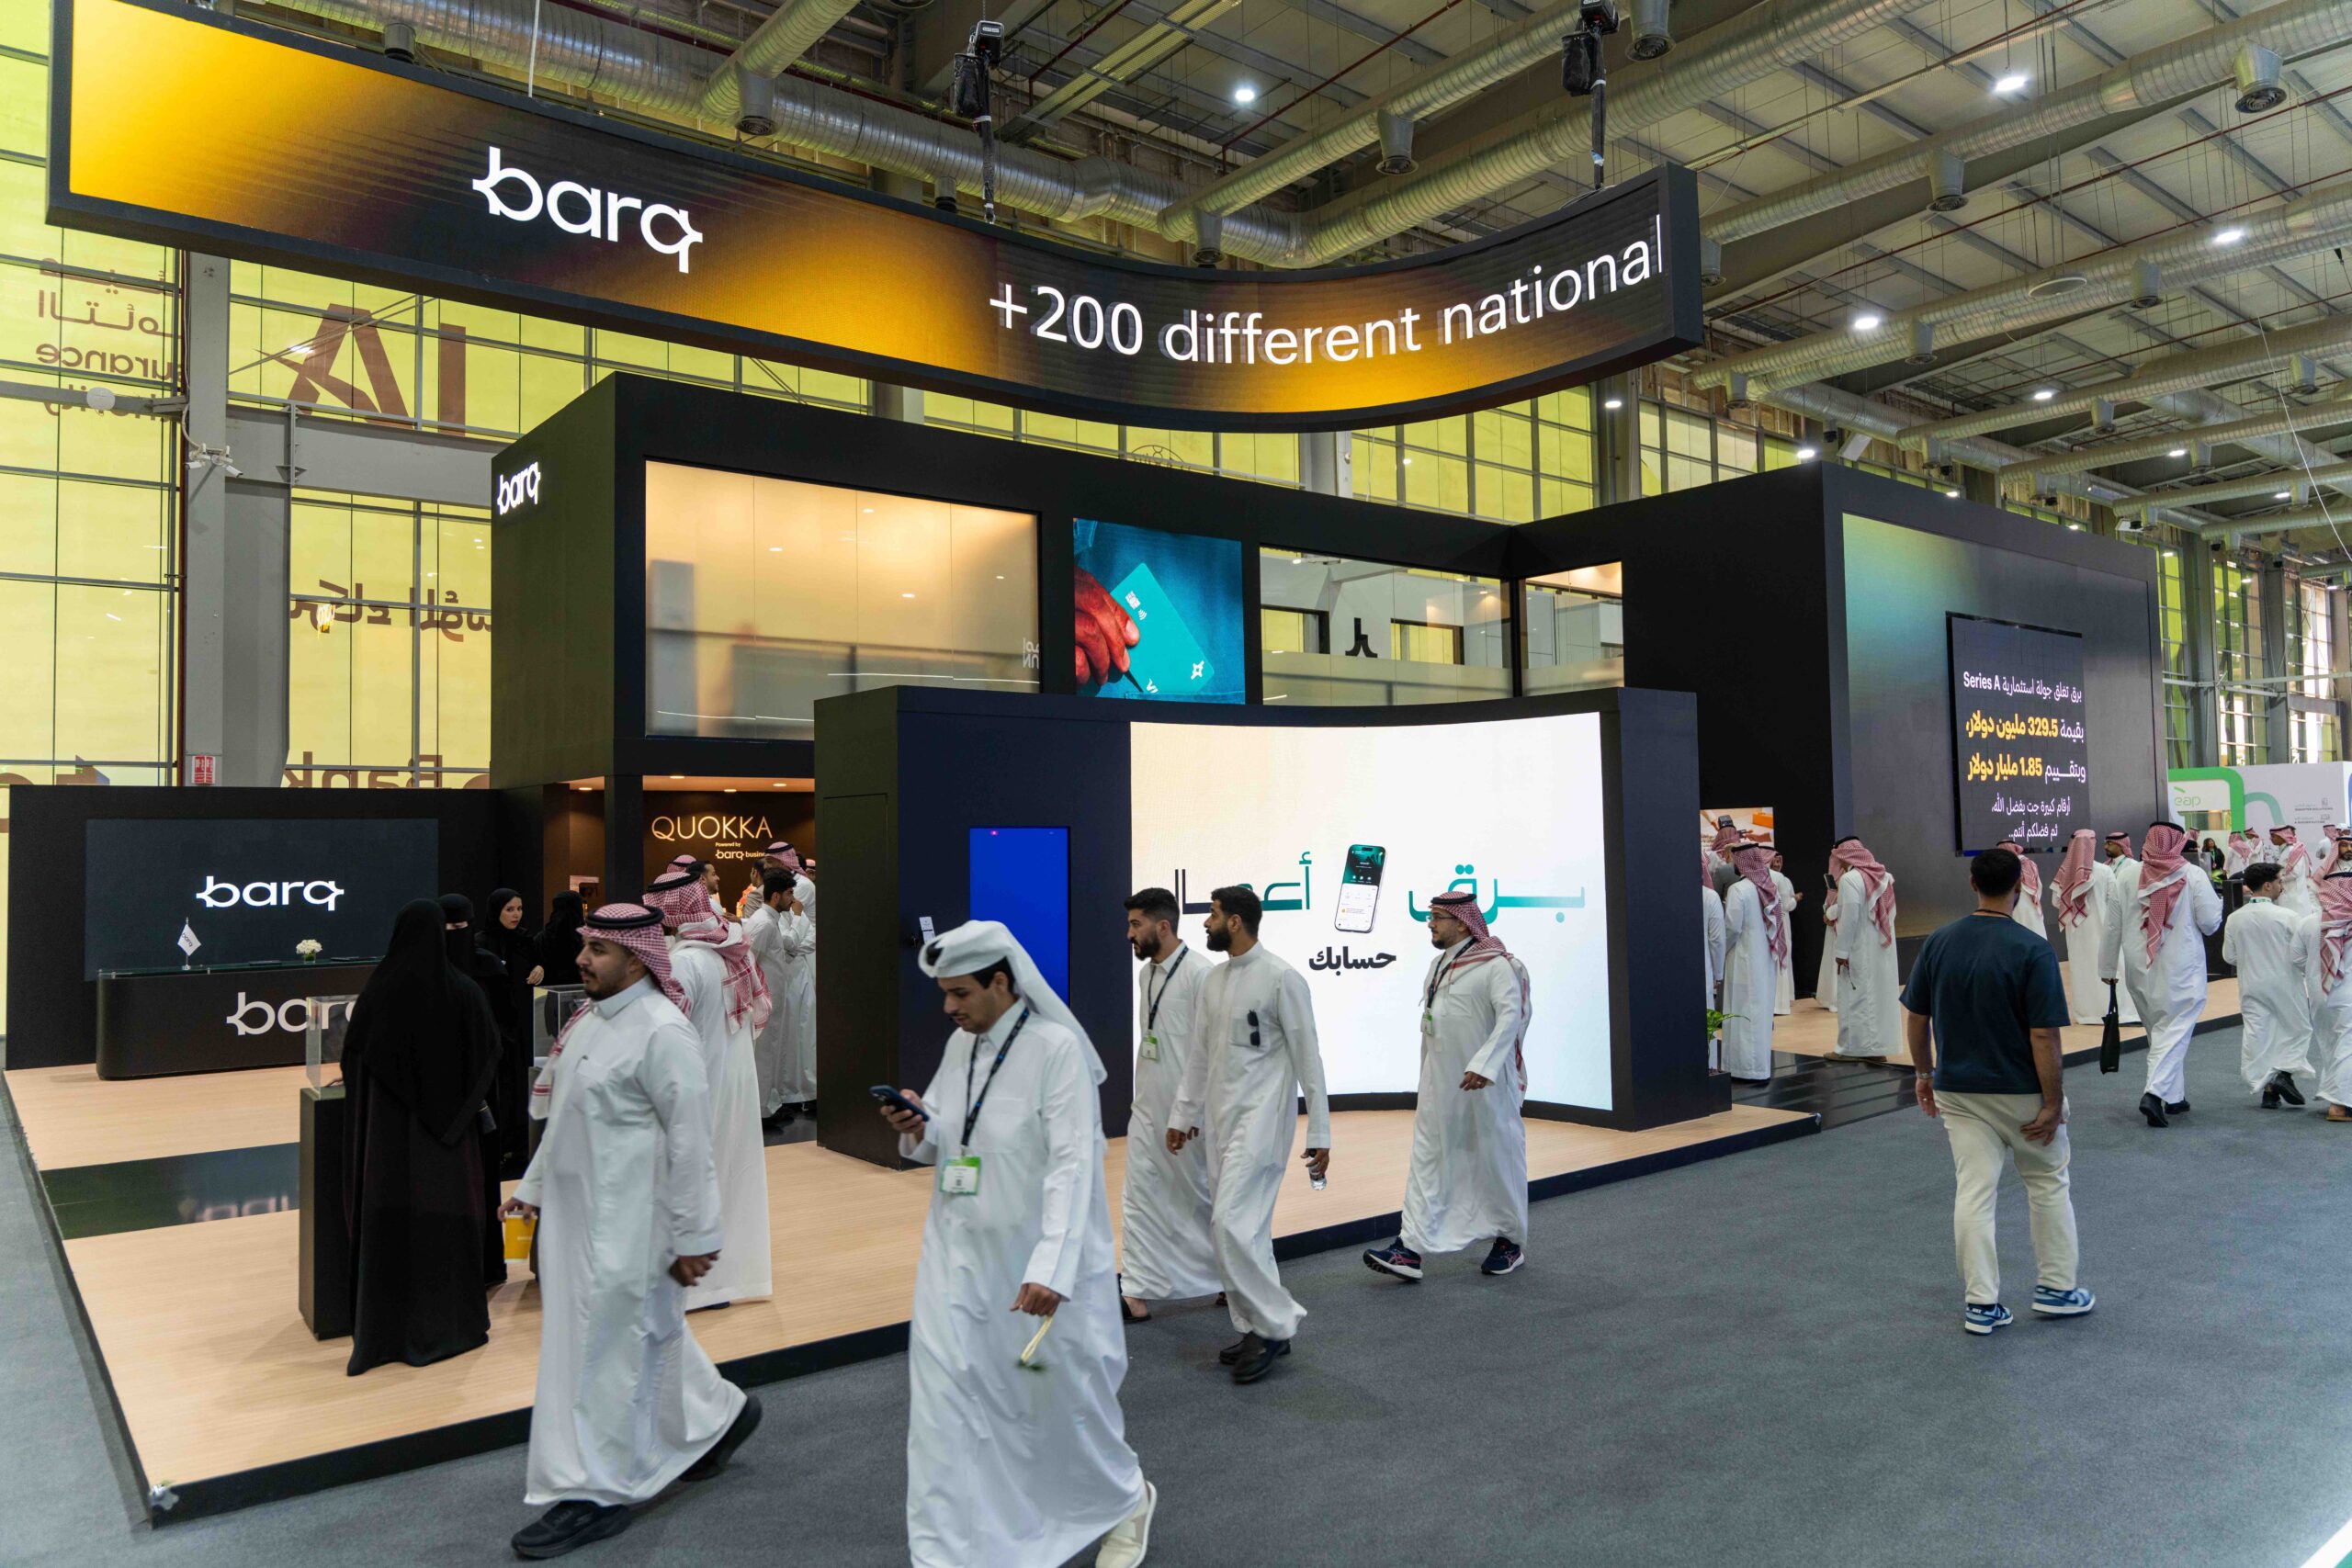
Saudi digital payments company barq announced the close of a series A funding round worth $329.5 million, at a valuation of $1.85 billion, marking a new milestone that reflects the growth the company has achieved since its launch. The funding round cements its position among the fastest-growing fintech companies in Saudi Arabia and the region.

The round saw participation from Noon Investments, Sohar International Bank, and M20 Fund, a step that reflects investor confidence in barq’s trajectory and future potential, and underscores the appeal of the investment opportunities emerging in the fintech sector across the Kingdom and the region.

The round follows a standout growth journey for barq, which has now surpassed 15 million users within two years, from more than 210 nationalities, alongside the expansion of its ecosystem of digital financial services and solutions — reflecting the growing demand for the company’s products and its ability to build a broad user base within a record period of time.

The value of funds processed has also surpassed SR440 billion ($117.2 billion), an indicator that reflects the scale of activity barq has achieved and the widening use of its digital financial services since launch.

Based on its valuation, barq has become one of the fastest companies in the region to reach unicorn status, and among the fastest globally within the fintech sector, reflecting the pace of growth the company has achieved within a short period since its launch.

The funding round will support barq’s next phase of growth, by strengthening operational efficiency, accelerating the development of products and services, investing in new financial and technology solutions, and expanding into new regional and international markets — contributing to delivering a more advanced and accessible digital financial experience for users.

This achievement comes at a time when Saudi Arabia’s fintech sector is undergoing exceptional development, driven by continued progress in financial and digital infrastructure, a supportive regulatory environment, the targets of Saudi Vision 2030, and the Saudi Central Bank’s efforts to advance digital payments and support innovation in financial services.

The close of the round marks a major milestone in barq’s journey, reflecting its ability to move within a short period from a phase of rapid growth to building a broad-scale digital financial platform, underpinned by a growing user base, an increasing volume of operations, and expansion ambitions aimed at strengthening its presence in the fintech sector at both the regional and international levels.

Source link

Latin American Neobanks Take the Next Step

As their customer base grows fast, fintechs across the region are looking to become banks in the full regulatory and economic sense.

This article appears in the September 2026 issue of Global Finance Magazine.

After nearly a decade of explosive growth, Brazil’s fintech industry has crossed a threshold that once looked unthinkable; a digital bank now counts more customers than any of the country’s storied private lenders.

According to recent data from the Central Bank of Brazil, nearly 60% of the nation’s adults now hold an account with Nubank, making it Brazil’s largest private financial institution by customer count, albeit still far from the largest by assets. Similarly, 55% of banked Brazilians primarily identify as customers of a digital bank or fintech, according to research organization Instituto Locomotiva.

“The fintech market has decidedly moved beyond access and into becoming the central piece of the Brazilian banking economy, also from the population’s perspective,” said Álvaro Machado Dias, associate director of Instituto Locomotiva.

The Brazilian experience reflects a broader shift across Latin America. Having secured a competitive customer base, the region’s fintechs are now seeking the licenses, deposits, and balance sheets that could allow them to become the banks they once set out to disrupt.

In Argentina, digital wallets have overtaken every other payment instrument, with 70% of consumers using them over the past six months compared with 52% for cash, according to Mastercard. Nu Mexico reaches roughly 15% of the adult population just seven years after entering the market, while Mercado Pago, the fintech arm of now-Montevideo-headquartered MercadoLibre Inc., now has 83 million monthly active users across eight countries, up 29% over the past year. 

The shift is also changing how consumers transact. Sixty-one percent of Brazilian and 47% of Mexican consumers used a mobile device for their latest retail purchase, according to PYMNTS Intelligence’s Global Digital Shopping Index.

Having crossed that threshold with customers, the fintechs are now moving to the next stage: becoming banks in the full regulatory and economic sense. Nubank agreed in July to acquire Banco Porto Real de Investimentos S/A, enabling it to obtain a Brazilian banking license, while its Mexican unit began operating as a bank last month, becoming the first Mexican popular financial society (SOFIPO) authorized to convert.

Mercado Pago is close behind, with its own application reportedly first in line at Mexico’s banking regulator and an ambition to build the country’s largest digital bank. Mexican fintech Plata secured its license in February, while Argentina’s Ualá Bank SAU already holds a full banking license at home and in Mexico and a financing company license in Colombia.

Why A Banking License?

The economics of the transition are straightforward. As fintechs scale, the limitations of lighter regulatory charters become increasingly binding. Nu Mexico’s SOFIPO status, for example, allows deposit insurance of just 25,000 UDIs (Mexico’s inflation-indexed units of accounts) per client; a full banking license raises that ceiling sixteenfold. Banks can also compete for payroll accounts, held by only about a third of Mexican adults and concentrated largely among four incumbent institutions.

Most important, a banking license gives fintechs access to the deposits that provide the cheapest funding for a growing loan book.

Nu Mexico already holds $5.9 billion in deposits, which makes the ability to gather and deploy them at scale an increasingly important side of its business.

“Once a digital bank holds the same license, follows the same rules, and funds itself the same way, it stops being essentially different from a traditional bank,” said Reginaldo Nogueira, national director of Brazil’s Ibmec business and economics school. “The difference shifts to technology, efficiency, and customer experience.”

Accompanying that strategic shift is a much larger investment commitment. Founder David Vélez paired Nubank’s Mexican license with a projected $4.2 billion investment in the country through 2030.

The fintechs’ current profile marks a striking reversal from where the industry began. A decade ago, they were outsiders challenging Latin America’s established banks to control the region’s customers, branches and balance sheets. Today, they have crossed the most important threshold on the customer side. The next step is to acquire the regulatory privileges and funding advantages that underpin the banking business itself.

Thomas Monteiro is a contributing writer based in Spain.

Source link

Revolut Fast Tracks to Wall Street With Conditional US Charter

Revolut gets an OCC thumbs up to launch a US bank, but lending ambitions are another issue.

Technically, financial technology company Revolut is already a bank across several regions—it holds licenses in the U.K., France, Mexico and Australia.

Now, in the U.S. market, it is one step closer to bankhood.

The London-based startup announced Thursday that it has received conditional approval from the U.S. Office of the Comptroller of the Currency for a national bank charter. The move would help the company grow its customer base from 80 million to 100 million by mid-2027.

It also exemplifies Revolut’s agility as a fintech compared to traditional banks, which typically take years to pull off similar expansion efforts.

“Legacy banks are working with legacy systems,” David Tirado, Revolut’s VP of Profitability and Global Business, told Global Finance in an interview last year. “Revolut, on the other hand, built our proprietary technology from the ground up with a global mindset. While competitors struggle to scale across different markets and regulatory landscapes, our systems were designed for this from day one.”

What Else Does Revolut Need?

Revolut still needs a green light from the Federal Deposit Insurance Corp. and the Federal Reserve, as well as final sign-off from the OCC, before it can open the proposed bank.

Once fully approved, Revolut said it would offer U.S. customers loans, credit cards, FDIC-insured deposits, and access to stablecoins and cryptocurrencies.

In a prepared statement, Revolut founder and CEO Nik Storonsky said the conditional approval was “an important first step towards establishing the proposed Revolut Bank US,” adding that it gives the company “the foundation to build in the world’s largest financial market.”

The U.S. bid follows Revolut’s expansion across Latin America, where the company recently launched a bank in Mexico and is pursuing licenses in Brazil, Colombia, Peru and Argentina. This year, Revolut has also obtained banking licenses in France, Australia and the U.K., a payments license in the United Arab Emirates, and is seeking a banking license in South Africa.

The company claims to add roughly 1 million customers every 17 days.

What About Lending?

Whether Revolut can become a customer’s primary financial institution without being a major loan underwriter remains to be seen. Revolut’s consumer lending segment remains small relative to its tens of billions in customer deposits. Still, it’s worth noting that the so-called neobank’s loan book, as of March, is up 120% year over year at $2.9 billion.

Felipe Peñacoba Martinez, CEO of Getnet Platforms Payments Hub and former CIO at Revolut Bank (EU), told Global Finance in June: “Revolut is aware this takes time, and they’re going slower than in other areas.”

Ultimately, the central question facing the industry is whether fintechs like Revolut can scale core banking products faster than traditional incumbents can modernize their digital ecosystems.

Anthony Noto covers corporate finance and private credit. Contact him at anoto@gfmag.com

Source link

Why Banks Are Losing the AI Search War

JPMorgan Chase dominates other banks when it comes to AI banking citations, but regional banks are invisible.

Whenever someone poses banking-related inquiries to AI platforms like ChatGPT, Claude, Gemini or Perplexity, the biggest banks are getting upstaged by third-party comparison hubs and media outlets.

Three websites in particular — Bankrate, Investopedia and Wikipedia — supply 68% of all banking-related AI citations, according to an “AI Visibility” report from communications firm 5WPR. Bank-owned domains, meanwhile, account for less than 7%.

Even within the narrow slice of visibility banks do capture, one name dominates. In response to real consumer questions, such as “best bank near me” or “top bank in [state],” JPMorgan Chase & Co. holds 28.4% of consumer banking AI citation share in the U.S. That’s more than Bank of America (7.1%), Wells Fargo (5.9%), Citi (4.8%), and Capital One (4.2%) combined.

The findings underscore a new reality in the AI era: brand prestige matters less if a chatbot leaves a bank out of the conversation entirely.

JPMorgan Leads Chatbot Citations

“It isn’t accidental,” Ronn Torossian, founder and chairman of 5WPR, told Global Finance in an email. JPMorgan Chase operates more than 4,800 branches across the U.S., but “branch count has almost nothing to do with it,” he added.

Whenever someone consults an AI platform about where to bank, the New York-based firm wins the AI answer outright in only three states: New York, Illinois, and Arizona. Still, Chase owes its AI presence to machine-readable content on its own site, combined with a press footprint that keeps it landing in outlets AI engines already trust, Torossian explained.

But the bank hasn’t locked in the lead just yet. “This is a snapshot, and AI citation patterns shift as engines update retrieval and as competitors invest in the same levers,” he added. “Any bank willing to match that content and structural investment can close the gap.”

Until then, AI assistants will likely continue citing media coverage of banks rather than the banks themselves, he added.

“What these publishers [Bankrate, Investopedia, Wikipedia and also NerdWallet] are doing right is straightforward: comprehensive, frequently updated comparison content, clear schema markup, strong domain authority, and a format built to directly answer the exact questions people and now AI are asking,” Torossian said.

These sites present direct ‘best’ and ‘worst’ rankings of banks, credit cards, and other financial products, giving AI engines structured data to pull from.

Bankrate, for example, feeds answers to specific inquiries about borrowing and connects them with competing lenders. This forces banks to up their game to win over potential customers.

“When banks compete, users get better [interest] rates that help them save money more easily and more effectively,” Bankrate editor-in-chief John Puterbaugh said in an email. “Our commitment to consumer advocacy and helping people get better deals runs across our whole business, and we believe this approach will win even as AI platforms and LLMs continue to evolve.”

What Are Banks Doing Wrong?

Bank websites, by contrast, typically heighten the marketing language to tout their products and offerings. The problem? AI engines ignore that type of content and, instead, identify content that answers specific questions with clarity.

As Andy Mollison, head of search and Innovation at Varn Search Marketing, puts it: AI systems are built around language.

“Vague claims such as ‘we go above and beyond’ provide little useful information,” Mollison said in an email. “A statement such as ‘customers can access support 24 hours a day, seven days a week’ is concrete, verifiable and far more likely to match a user’s query.”

Regulatory and compliance constraints also limit how banks communicate in ways that don’t affect financial-information publishers, Mollison explained. “That often leaves them with less educational content, and more content that is cautious, technical or heavily qualified,” he added.

As a result, publishers have the AI advantage over banks, because they write in language that matches how people actually ask questions.

Regional Banks Face a Discovery Gap

Perhaps the starkest finding from the 5WPR report is this: 22 of the 75 largest U.S. banks registered less than 0.3% citation share. Top bank names — Fifth Third, KeyBank, M&T, Huntington and Regions — barely show up despite their branch networks. Meanwhile, fintech challengers are eating their lunch.

Chime, SoFi, Ally and Discover now out-cite regional banks like PNC, Truist, U.S. Bank and Citizens in AI answers, despite operating with a fraction of the deposit base.

“These five banks registering under 0.3% citation share despite significant size and branch networks isn’t a vanity-metric problem; it’s a discovery problem,” Torossian said. “As more consumers use AI assistants as a first stop for financial research, a bank that’s missing from those answers is missing from consideration at the exact moment decisions are being formed.”

5WPR is careful to frame the index not as a hard count pulled from platform query logs. “Nobody outside those companies has access to that, and any firm claiming otherwise is overselling,” Torossian said. He also acknowledged the report can’t yet tie citation share to account openings or traffic. AI platforms, after all, don’t publish that data. “We’re measuring the front door. We’re not measuring the sale,” he said.

Why AI Invisibility Is Risky

Still, Torossian argued that waiting for proof before investing in AI visibility carries its own risk.

Recall the early days of search engine optimization when Google’s search algorithms transformed how businesses competed online. Companies began investing heavily in web presence during the so-called “SEO Gold Rush” in the early 2000s.

“The brands that showed up first captured the customers,” Torossian said. The ones that waited for proof spent the next decade “trying to catch up,” he added.

“That’s the same bet regional banks made about search fifteen years ago,” he added. “And it’s the same bet that let fintechs out-cite them in AI answers today.”

5WPR isn’t the only agency tracking AI usage among bank consumers. Wells Fargo published a survey in April, alongside the American Bankers Association, reporting that 19% of U.S. adults (and 38% of Gen Z) use AI for financial advice. Two-thirds of those respondents acted on the AI financial suggestions and said those recommendations proved profitable or worthwhile.

In other words, facts matter. Tyler Desjardin, the founder of Pivot Creative Media, a firm that focuses on improving business visibility when it comes to SEO and AI-generated results, advises clients to prioritize just that.

“Brands need to ensure that they provide accurate information so that AI does not have to create something that could be misleading to search engines,” Desjardin said. “Visibility should come from structured information that conveys correct facts, rather than trying to game the system, since AI automatically eliminates any thin or misleading content.”

Anthony Noto covers corporate finance and private credit. Contact him at anoto@gfmag.com
Source link

Worldpay Deal Anchors Fintech’s Best Half in Years: KPMG

There’s a lot of cash, but fewer deals propelled global fintech to the best year since 2022.

When Global Payments completed its roughly $24.3 billion acquisition of London-based Worldpay in January, it would account for nearly a quarter of all global fintech investment in the five months that followed, according to Big Four auditor KPMG International’s latest Pulse of Fintech report released Monday.

That massive transaction captures the central paradox shaping current fintech funding: total capital is surging, yet it is concentrated in fewer hands.

KPMG crunched the numbers using data from PitchBook, which tracks M&A and venture capital activity. Overall fintech investment surged to $103.1 billion across the six-month period — up from $72.2 billion in the second half of last year — putting the sector on track for its strongest annual performance in four years. Overall deal count, however, dropped to a multi-year low.

Deal Volume Remains Soft

The shift reflects a strong preference for mature fintechs with proven track records over higher-risk, early-stage startups.

As a result, global deal volume dropped to just 2,100 transactions in the first half of the year. That’s down from 2,501 in the prior six-month period (the last six months of 2025). Instead of spreading capital across early-stage ventures, investors funneled funds into late-stage blockbuster deals.

Ten deals worth $1 billion or more closed during the period. In addition to buying WorldPay, Global Payments Inc. found itself on the sell side. The Atlanta-based company sold its issuer solutions business, Total System Services (TSYS), to Fidelity National Information Services Inc. for $13.5 billion — also in January.

Among the other megadeals of 2026, thus far, are the $8.4 billion buyout of Clearwater Analytics and the $6.4 billion take-private of OneStream. In Europe, Denmark’s Saxo Bank was acquired for $1.2 billion, and Belgium’s Kpler Holding landed a private equity growth equity investment of over $1 billion from global investment firm Sixth Street Partners in June.

Investment Falls Sharply Outside the Americas

The Americas accounted for more than 80% of global fintech investment, drawing $86.9 billion across 1,120 deals. The U.S. alone attracted $80.8 billion across 933 deals — over 75% of worldwide investment and 92% of the region’s total. American merger and acquisition activity more than doubled, rising to $64.6 billion from $27.4 billion in the prior six months.

Asia-Pacific investment slid to $4.6 billion across 350 deals, down from $7.1 billion across 426 deals, with weaker activity in China, Japan and Singapore. India held up better, drawing $2 billion, while South Korea hit a four-year high of $899 million.

Sub-Sector Specifics

Digital assets, meanwhile, attracted $11.1 billion across 467 deals. Corporate venture arms of major crypto platforms drove much of the activity in that corner. AI-focused fintechs pulled in $21.4 billion combined across venture capital, private equity and M&A.

M&A Across the Board

The dynamics shaping fintech mirror a macro trend sweeping the global dealmaking landscape: total dollars are surging, but transaction activity remains bottlenecked. Across all sectors, PitchBook reported that global M&A deal value posted massive year-over-year gains in H1 2026. It reached $1.6 trillion in Q1 (up 50.5%) and $1.3 trillion in Q2 (up 35.3%). Just as in fintech, capital is concentrating heavily at the top — driven almost entirely by megadeals while overall transaction volume stays flat.

Source link