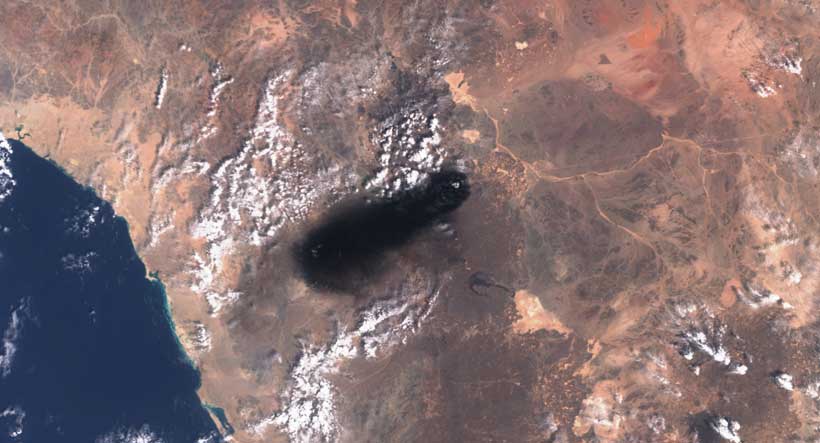
Saudi Arabia has closed its East-West oil pipeline due to a drone attack linked to Iranian-backed militias in Iraq. This pipeline is crucial for Saudi Arabia, as it allows the country to bypass the congested Strait of Hormuz, which has faced reduced tanker traffic due to an ongoing conflict between the U.S. and Iran. The Saudi Energy Ministry stated that the closure is a precautionary measure; the pipeline typically carries about 4 to 5 million barrels of oil per day, contributing 4% to 5% of global oil supply. The attack caused injuries and damage, but the exact impact on oil exports is still being evaluated.
President Trump, while attending a golf event in Ireland, suggested that Iran was likely responsible for the attack and predicted that oil prices would drop after the upcoming U.S. midterm elections. Recently, oil prices have surged, with diesel prices in the U.S. topping $6 a gallon due to tensions in the region. Reports surfaced that the Houthis, aligned with Iran, seized the strategic Perim Island in the Red Sea.
Crown Prince Mohammed bin Salman of Saudi Arabia reached out to Trump for military assistance against the Houthis, but Washington decided not to intervene directly at that moment, offering intelligence support instead. There were concerns that the attacks on the pipeline and Perim Island could escalate tensions further, especially since diplomatic efforts to resolve the war have stalled.
Iran’s parliamentary committee has stated that negotiations are futile unless the U.S. meets Iran’s demands, particularly concerning recognition of its control over the Strait of Hormuz. The Iranian foreign ministry announced plans for discussions with Gulf states in Oman regarding the strait. Meanwhile, Iraq’s government dismissed a military commander connected to the attack and has closed the Shalamcheh border crossing with Iran as a precaution to prevent further incidents.
The Saudis have not retaliated yet, following a request from Iraq’s prime minister, but they maintain the right to take necessary actions to protect their interests. Saudi Arabia’s oil production has plummeted to its lowest level in over 30 years, partly due to attacks on maritime vessels by Houthi factions. These forces, supported by Iranian guidance, are reportedly planning counterattacks to reclaim territories lost to the Houthis, who have advanced significantly along Yemen’s coast under Iranian direction. The Houthis have claimed that maritime navigation remains safe, except for Saudi vessels, which are subject to a ban.
The Strait of Hormuz has become the central pressure point in the escalating confrontation between the United States and Iran. Before the conflict, roughly 20 million barrels of oil moved through the narrow waterway each day, equivalent to about one fifth of global oil consumption. For years, traders could therefore rely on relatively consistent estimates of the volumes passing through one of the world’s most important energy corridors.
That certainty has now disappeared.
The use of “dark crossings,” in which tankers switch off their identification and navigation systems, has made vessel movements increasingly difficult to monitor. Satellite imagery, port records, tanker drafts, loading schedules and shipping data are being used to reconstruct movements, but the information remains incomplete. Recent estimates of Hormuz flows have differed dramatically, leaving traders and governments uncertain about the true scale of oil moving through the waterway.
The uncertainty comes as Brent crude has moved above the $100 a barrel threshold for the first time since July, driven by renewed military escalation and concerns over Middle Eastern oil supplies.
Stay ahead of the geopolitical week.
MD Briefing delivers expert analysis across five global fronts — the Indo-Pacific, energy, geoeconomics, European security, and the Middle East — every Monday morning. Free.
The Hormuz Information Gap
The most unusual feature of the current oil crisis is not simply that supplies may have fallen. It is that markets cannot confidently determine how much oil is actually moving.
U.S. Energy Secretary Chris Wright said more than 17 million barrels crossed the strait on August 31 under U.S. Navy supervision. Shipping intelligence firm Kpler, however, estimated that only around 6 million barrels crossed that day. Kpler put average August flows at approximately 4.3 million barrels per day, with flows rising to nearly 5 million barrels per day during the first days of September.
The difference could partly reflect different methodologies, including whether shipments using alternative routes outside Hormuz are included. Tankers that remain invisible to tracking systems for days or even weeks make the picture even harder to reconstruct.
This means that traders are attempting to price global oil supplies without reliable visibility over one of the world’s most important supply arteries.
Why the Strait of Hormuz Matters
Hormuz is strategically important because of the enormous concentration of energy exports that normally pass through it. Any sustained disruption can affect crude supplies, tanker availability, insurance costs and shipping times, eventually feeding into fuel prices and broader inflation.
The current situation is different from a straightforward blockade. The strait has not necessarily become completely impassable. Instead, its reliability has been severely compromised.
That distinction matters because a tanker does not have to be physically prevented from crossing for markets to react. The possibility that vessels may be delayed, attacked or unable to cross safely is enough to increase the cost of transporting oil.
As a result, the market is responding not only to actual supply losses but also to the risk of future disruption.
Iran’s Strategic Leverage
Iran’s ability to disrupt maritime traffic remains an important source of leverage despite indications that its military capabilities around Hormuz have been weakened.
U.S. demining operations and a growing U.S.-protected shipping corridor along Oman’s coast have allowed more vessels to enter and leave the Gulf. At the same time, Iran-linked forces continue to threaten commercial shipping, meaning Tehran retains the ability to create uncertainty even if it cannot completely shut down the waterway.
This gives Iran a form of asymmetric leverage. Tehran does not necessarily need to close Hormuz completely to impose economic costs. Sporadic attacks, warnings or restrictions can increase insurance premiums, delay shipments and encourage traders to price in a greater possibility of supply disruption.
The renewed attacks on Saudi energy infrastructure have added another layer of risk by threatening alternative routes that have become increasingly important as traffic through Hormuz has declined.
Impact on Global Oil Markets
The immediate consequence is a higher geopolitical risk premium on crude.
Oil prices normally respond to measurable fundamentals such as production, consumption, inventories and transportation. But when the market cannot establish how much oil is moving through Hormuz, uncertainty itself becomes part of the fundamental picture.
This can keep prices elevated even if actual physical supply losses are smaller than feared.
Brent has already moved above $100 a barrel, while analysts and major financial institutions have raised their oil price forecasts as concerns about prolonged disruption increase.
For oil-importing countries, sustained high crude prices could translate into higher fuel and transportation costs, increased inflationary pressure and greater economic uncertainty. Airlines, manufacturers and businesses dependent on energy-intensive supply chains would also face higher operating costs.
Economic and Geopolitical Implications
The crisis demonstrates how vulnerable the global energy system remains to a single strategic chokepoint.
For the United States, maintaining freedom of navigation through Hormuz is not simply a military objective. It is also essential to preventing a regional conflict from becoming a wider global energy crisis.
For Gulf producers, the challenge is equally significant. Even countries with substantial production capacity cannot fully compensate for disrupted shipping if export routes remain vulnerable.
For major Asian importers, the risks are particularly serious because much of the energy normally passing through Hormuz is destined for Asian markets. A prolonged disruption could therefore create significant pressure on import bills, currencies and inflation across energy-dependent economies.
The crisis also highlights the limits of alternative routes. Pipelines and routes outside Hormuz can reduce some of the pressure, but they cannot immediately replace the enormous volumes that normally pass through the waterway.
What’s Next?
The key variable is whether the confrontation between Washington and Tehran moves toward negotiations or further escalation.
A diplomatic breakthrough could rapidly reduce the geopolitical risk premium by restoring confidence in shipping and improving visibility over oil flows. A further escalation, however, could produce additional attacks on tankers, restrictions around the Gulf or renewed pressure on alternative shipping routes.
The oil market will therefore be watching tanker movements as closely as military developments.
If shipping activity becomes more visible and flows recover, some of the current premium could disappear. If the information blackout continues, traders may continue pricing the possibility of a much larger supply disruption.
Analysis
The deeper significance of the Hormuz crisis is that information itself has become a strategic commodity.
Modern energy markets have traditionally depended on the ability to monitor ships, cargoes and supply chains with increasing precision. Satellite imagery, tracking systems and port data created an assumption that physical oil flows could be observed and measured with reasonable accuracy.
That assumption is now being challenged.
The result is a market where perception can influence prices almost as powerfully as physical shortages. If traders believe Hormuz is becoming less reliable, they will pay more for crude today even without definitive evidence of a catastrophic supply loss.
This gives Iran an important form of strategic leverage. The threat of disruption can generate economic consequences even when actual disruption remains limited.
At the same time, Washington faces a difficult calculation. Greater military protection may help keep shipping moving, but prolonged confrontation can also increase the geopolitical risk premium that the United States is trying to contain.
The central question, therefore, is no longer simply how much oil is passing through the Strait of Hormuz. It is how long the global market can function without knowing the answer.
If that uncertainty persists, the oil market could continue carrying a substantial security premium even if physical supplies prove higher than current estimates suggest. The longer the uncertainty lasts, the more deeply it can become embedded in prices, inflation expectations and global economic planning.
The Iran conflict and disruption to the Strait of Hormuz are forcing major oil importing countries to rethink how they source crude. Countries that once relied heavily on nearby Middle Eastern suppliers are increasingly turning to producers in the Americas and Africa, accepting longer voyages and higher shipping costs in exchange for greater energy security.
Japan Diversifies Its Oil Supplies
Japan is among the clearest examples of this shift. Before the conflict, more than 90% of its crude came from the Middle East, benefiting from short and relatively inexpensive shipping routes.
Since Gulf exports were disrupted, Japanese imports from the United States have surged. Between March and June, Japan imported more than 4.5 million metric tons of US crude, compared with less than 1 million tons during the same period in 2025.
The alternative comes with a cost. US crude takes roughly nine days longer to reach Japan, increasing freight expenses and requiring refiners to adjust their delivery schedules.
Stay ahead of the geopolitical week.
MD Briefing delivers expert analysis across five global fronts — the Indo-Pacific, energy, geoeconomics, European security, and the Middle East — every Monday morning. Free.
Asia Looks Beyond the Middle East
Japan is not alone. South Korea and India are also increasing purchases from suppliers in the Americas and Africa as Middle Eastern shipments decline.
China, the world’s largest crude importer, has relied heavily on strategic reserves to cushion the impact of the conflict. As those reserves are drawn down, Chinese buyers could return to international markets and intensify competition for crude from alternative producers.
The Americas Emerge as Major Suppliers
The disruption has created a major opportunity for oil exporters outside the Middle East.
US crude exports reached a record 61.6 million metric tons in the second quarter of 2026, up 43% from a year earlier. Brazil, Argentina and Guyana have also recorded strong export growth.
Brazilian shipments to India, for example, were three times higher in the first half of 2026 than during the same period in 2025.
Longer Routes, Higher Costs
The new trade patterns are considerably less efficient.
A tanker travelling from major Gulf terminals to India’s western coast can take only three to five days. A shipment from Brazil to the same destination can take around 25 days.
Longer journeys mean higher tanker demand, greater freight costs and more complicated logistics. Yet importers are increasingly willing to absorb those costs because dependence on a single vulnerable supply corridor carries its own risks.
Avoiding Strategic Chokepoints
The shift is also about reducing exposure to vulnerable maritime routes.
The Strait of Hormuz remains a major risk, while geopolitical tensions have reduced traffic through the Suez Canal. Drought has also constrained the Panama Canal.
As a result, importers are increasingly valuing suppliers whose shipping routes can bypass these chokepoints.
A New Global Energy Map
The emerging pattern is creating a more geographically dispersed oil market.
Middle Eastern producers will remain crucial because of their enormous reserves, low production costs and established infrastructure. But Asian buyers are unlikely to forget the disruption caused by the Hormuz crisis.
Regular purchases from new suppliers can therefore become a form of insurance, even after Gulf exports recover.
Analysis
The most important change is that energy security is beginning to outweigh pure economic efficiency.
For decades, Asian refiners benefited from buying Middle Eastern crude because geography made it cheaper and faster. The Iran conflict has exposed the vulnerability of that model. A short shipping route is of limited value if a single geopolitical crisis can disrupt it.
The result could be a lasting diversification of global oil trade. Importers are unlikely to completely abandon Middle Eastern crude, but they may maintain larger relationships with US, Latin American and African suppliers to create alternative sources of supply.
This means the cost of energy security will increasingly be reflected in the global oil market. Longer voyages, higher freight rates and more complex supply chains may become the price importers are willing to pay for resilience.
The broader shift is therefore from an oil market designed primarily around efficiency to one increasingly designed around redundancy and geopolitical risk.