Dutch

Dutch riot police break up violent far-right protest in The Hague | The Far Right News

Justice minister condemns ‘Hitler salutes, antisemitic slogans, violence’ at the anti-immigration rally.
Dutch riot police have intervened at a protest against immigration and asylum policies after about 500 far-right demonstrators pelted them with projectiles and fireworks .

Police used baton charges and dogs to break up the demonstration in The Hague on Saturday, reported the AFP news agency.

Recommended Stories

list of 4 itemsend of list

Local authorities said the demonstration was ended because of continued violence, and protesters were escorted away from Malieveld park in the city centre.

Police said they arrested 24 people and deployed water cannon to disperse the rioters. Further investigations were underway, they added.

Prime Minister Rob Jetten said on X that the demonstrators deliberately sought confrontation with the police and chanted “abhorrent” far-right and antisemitic slogans

Justice Minister David van Weel condemned the violent scenes and slogans.

“Identical images from the Malieveld. Hitler salutes, antisemitic slogans, violence against the police and throwing fireworks at the riot squad,” he posted on X. “It is important that hardline action is taken against this.”

He also thanked police officers for helping to maintain the democratic rule of law.

The “Wij zijn het volk” rally, which translates to “We are the people”, was organised to protest against government policies in the Netherlands’, specifically on immigration.

The protesters had planned to march through The Hague, but local authorities banned it when violence began and ordered the demonstration to be broken up.

A child runs with the Prince's Flag with the symbol of the Dutch East India Company during a far-right demonstration in The Hague, Netherlands, September 19, 2026. REUTERS/Nicolas Economou
The Prince’s flag with the symbol of the Dutch East India Company during the far-right demonstration in The Hague on Saturday [Nicolas Economou/Reuters]

Someone at the rally was seen giving a Hitler salute, while a truck serving as a stage displayed a screen reading “The Netherlands is for the Dutch,” according to the country’s largest national news agency, Algemeen Nederlands Persbureau (ANP).

Protester Thijs Jansen, a 31-year-old mechanic, told AFP: “We’re losing our country. We’re literally losing our country to mass migration”.

Saturday’s unrest came a year after Dutch police used water cannon to disperse another anti-immigration rally in The Hague.

A police car was then set on fire in clashes between black-clad protesters and police, as the headquarters of the centrist D66 party were attacked. Its leader, Rob Jetten, is now prime minister.
Source link

Dutch Pension Shift Hits Long-Term Debt Market

European CFOs must adjust as the region’s biggest pension buyer of long-dated debt cuts back.

This article appears in the September 2026 issue of Global Finance Magazine.

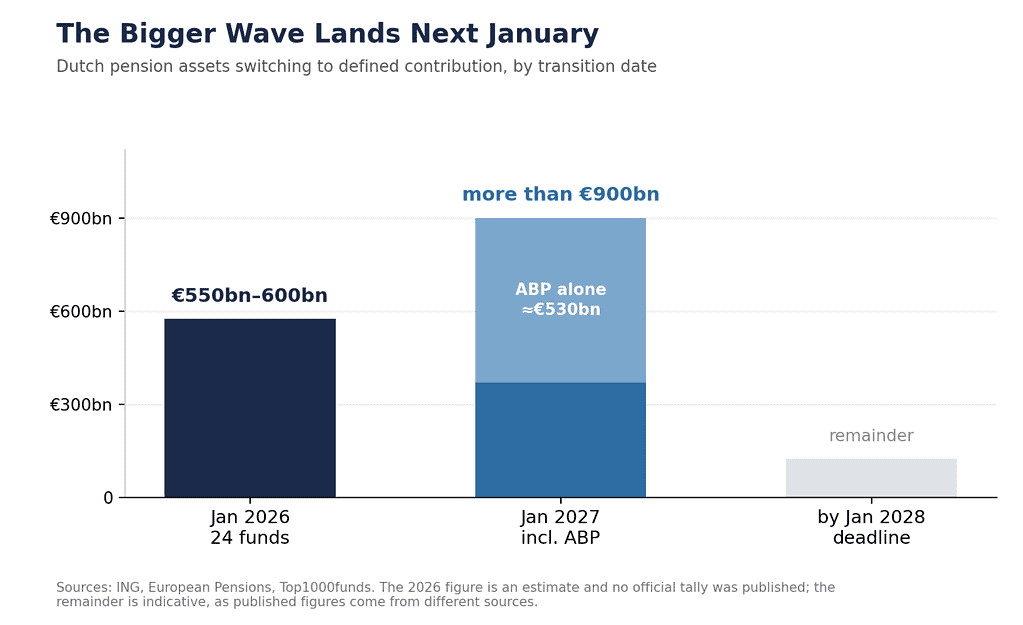
The Netherlands pension system is beginning to reduce one of Europe’s most reliable sources of demand for long-dated debt as a broad regulatory shift changes how Dutch pension funds manage their assets and liabilities. ING Groep NV estimates that nearly €600 billion ($699 billion) of assets have already been affected by the change, with more than €900 billion expected to follow early next year.

Under the old defined-benefit pension system, Dutch funds were required to hedge the interest-rate sensitivity of long-term pension liabilities by using long-dated bonds and swaps to match assets with payments extending decades into the future. Under the new defined-contribution model, which became law in 2023, that liability matching requirement has been significantly reduced, allowing funds to carry less duration and scale back their long-term hedges, resulting in less structural demand for the longest-dated debt and swaps.

For European CFOs, this could mean a higher premium for 20-, 30- and 50-year borrowing as companies and governments compete for a smaller pool of long-duration investors.

The change “should reduce structural demand for long-end duration assets and support curve steepeners over the long-term horizon,” wrote Sara Adjir, senior vice president and portfolio manager, and Jeroen van Bezooijen, account manager, at Pacific Investment Management Co., in a research note. They expect the impact will be mostly concentrated in 50-year swaps, but will also be felt in the demand for 20- and 30-year euro swaps and government bonds, including German and Dutch debt.

Deadlines

The Netherlands runs Europe’s largest pension system, with roughly €1.6 trillion in assets, and every fund must complete the switch by January 2028. Dutch pensions have long dominated the market for European long-dated debt, holding around €88 billion of interest-rate swaps maturing beyond 25 years at the end of last year, roughly a quarter of the total.

The first major wave of the transition came on Jan. 1, when 24 funds converted, among them the healthcare scheme PFZW and the metals scheme PMT, with an estimated €550 billion to €600 billion of pension assets between them. Analysis by the Netherlands central bank shows that Dutch pensions bought almost €34 billion net of swaps maturing inside 25 years while selling more than €12 billion of longer-dated ones. 

The bigger test, however, comes when more than €900 billion of pension assets is scheduled to convert on Jan. 1, with the Dutch civil service scheme ABP accounting for about €530 billion of that. 

The shift does not mean long-dated Dutch debt is suddenly becoming illiquid or even hard to sell: “Overall, we still see strong demand for our 30-year bond. Remember, we are AAA,” said Saskia van Dun, director of the Dutch State Treasury Agency.

Sovereign Issuers Adjust

Data indicates that sovereign borrowers are already adjusting to the change.

The share of Netherlands government bonds sold at maturities beyond 10 years fell from 42% at the start of 2025 to 31% by the third quarter, according to the Organization for Economic Co-operation and Development (OECD), which calls the constraint on long tenors structural. The OECD expects eurozone debt agencies to sell a record €1.35 trillion of medium- and long-term bonds this year into that thinner pool of demand.

For European finance chiefs, however, times are changing. For two decades, long-dated bond demand was unusually deep and predictable. As it recedes, the shifting cost of locking in 20 or 30 years of funding could become a live question.

Thomas Monteiro is a contributing writer based in Spain.

Source link