Libya

For Libya, the Hormuz crisis can be a trap or an opportunity | Energy

Amid the worsening global energy crisis triggered by the US-Israel war on Iran, European countries, desperate for alternative energy supplies, trade routes and partnerships, have looked across the Mediterranean for solutions.

As a result, governments across North Africa have started to reassess their strategic value. Algeria is in an especially strong position as an established gas supplier, while Egypt can offer infrastructure, refining capacity and access through the Suez Canal.

Libya has also seen its strategic value increase. It has around 48 billion barrels of proven oil reserves, the largest in Africa, and produces 1.5 million barrels of oil per day. It also has substantial natural gas reserves.

Its oil reaches international markets through the Mediterranean, while the Greenstream gas pipeline connects its Mellitah complex directly to Europe.

Libya cannot replace the Gulf in terms of oil and gas exports, but it can become a major player in diversification efforts not just in Europe but elsewhere in the world. The challenge the country faces is how to take full advantage amid structural constraints and insecurity.

Energy insecurity at home

Libya is simultaneously a major energy exporter and an energy-insecure state. Although the country possesses vast oil and gas resources, Libyans experience regular electricity blackouts due to an inefficient domestic energy system.

More than 70 percent of Libyan gas production is consumed domestically, mostly for electricity generation. Production has struggled to meet both domestic needs and export commitments. Gas exports consequently fell year on year from around 200 billion cubic feet in 2019 to 35 billion in 2025, the lowest export levels in 22 years.

At the same time, the country is flaring at least 200 billion cubic feet of gas annually due to underdeveloped infrastructure. Gas that could generate electricity, support industry or increase exports is instead being wasted.

The International Monetary Fund has estimated Libya’s total energy subsidy burden at around $17bn, equivalent to roughly 35 percent of GDP – one of the largest in the world.

Much of these funds go into subsidising imported refined fuels, as domestic refining capacity is largely underdeveloped and cannot meet demand.

The domestic energy situation is compounded by political fragmentation, institutional disputes and periodic disruptions to production due to conflict.

Increasing exports without addressing these problems risks improving energy security abroad while neglecting it at home, and that is a recipe for more instability in an already fragile nation.

Opportunity or trap?

The global energy crisis triggered by the Iran war is surely a major opportunity for Libya to increase its revenues from hydrocarbons. But it also carries a risk.

As I pointed out during the 5th meeting of the Mediterranean Energy Experts Circle earlier this month, greater demand for Libyan oil and gas could reinforce the economic model the country has struggled to escape from for decades: producing hydrocarbons, exporting them, distributing the revenues and postponing structural reform.

This model does not allow Libya to capture the full economic potential of its resource wealth. It keeps the Libyan state stuck in the all too familiar “resource curse”, which promotes economic stagnation and inefficiency.

That is why when taking advantage of heightened demand for energy, it is crucial that Libya uses the proceeds to transform its energy system.

That means capturing flared gas, modernising electricity generation and transmission, expanding domestic refining where economically viable, reforming subsidies, investing seriously in renewable energy and participating in sustainable regional energy cooperation.

Libya’s National Sustainable Energy Strategy aims to have 22 percent of electricity generation from renewable sources by 2035, an ambitious target that requires major positive shifts in security and governance conditions. Increased revenue flows can help jump-start the process.

Another important consideration is how the country should approach heightened foreign interest. Libya’s first major oil and gas licensing round since 2007 was concluded in February, with the US’s Chevron, Italy’s Eni, QatarEnergy, Spain’s Repsol, Hungary’s MOL, Nigeria’s Aiteo, and Türkiye’s TPAO securing new licences.

Commercial and geopolitical interests are rarely completely separate in energy. For Libya, this creates bargaining power—if managed coherently by the Libyans. Rather than becoming an arena in which external actors compete for individual assets and relationships, Libya could use diversified partnerships to attract investment and technology while reducing dependence on any single partner.

From energy exporter to Mediterranean energy hub

The transformation Libya seeks should not be confined to its borders. Its strategic objective should be to become an integral player in a Mediterranean energy hub by expanding cooperation with neighbouring states and leveraging existing production capacities and infrastructure.

To Libya’s east, Egypt has a large electricity system and significant refining and processing capacity. To its west, Tunisia provides access towards the wider Maghreb and increasingly towards European markets. Libya sits between them with enormous hydrocarbon resources, considerable solar potential and existing energy connections with both neighbours.

Important steps have already been taken to deepen regional energy integration. In January, Egypt and Libya signed an energy cooperation agreement covering exploration and the development of crude-oil refining. The two countries are also discussing the construction of an 800km pipeline connecting Tobruk to Alexandria. The project is worth $1bn and would carry Libyan crude directly to Egyptian refineries.

Libya and Tunisia are also expanding cooperation. Earlier this month, the Libyan-Tunisian company Joint Oil opened an international licensing round covering around 3,000 square kilometres of shared offshore acreage and development of the cross-border Zarat oil and gas discovery. Formal awards are expected by the end of April 2027.

The risk here is that expanded cooperation could develop into dependence. How to avoid that is the lesson Libya can learn from the Strait of Hormuz crisis. The country still needs sufficient domestic electricity, refining and production capacity to protect itself. Regional integration should add alternatives rather than create new vulnerabilities: more markets, more electricity connections, more processing options and more export routes.

The objective should therefore be specialisation, connectivity and redundancy all achieved in the right sequence depending on needs and conditions.

A moment for strategic redesign

The Iran war has given Libya something potentially more valuable than temporarily higher hydrocarbon prices: renewed strategic relevance. But greater strategic relevance does not automatically make the country a more reliable energy partner.

Converting the former into the latter requires a radically different approach not just to the domestic oil and gas industry, but also to overall economic development and regional geopolitics.

Libya must use this moment to pursue strategic redesign: to increase production while recovering wasted gas, improve electricity infrastructure, develop refining and renewables, strengthen regional connections and cooperation, and use competition among international partners to attract investment.

Libya already has the resources and the geography to become an even bigger player in the energy market. The question is whether it can build the rest.

The views expressed in this article are the author’s own and do not necessarily reflect Al Jazeera’s editorial stance.
Source link

Arab News | Libya’s NOC says it may declare force majeure after protests hit oil facilities

TRIPOLI: Operations were suspended at two oilfields and a pumping station after members of the security force charged with protecting Libya’s oil sector closed a valve on the main Hamada-Zawiya crude-loading pipeline, the National Oil Corporation said on Tuesday.

The NOC said it may declare force majeure if the valve remains closed or if other fields ‌are subjected ‌to similar forced shutdowns.

The company said ‌production had completely halted at the Hamada and Tahara fields and at a pumping station. Libyan oil output has been subject to repeated closures for political and technical reasons since the 2011 uprising against Muammar Qaddafi.

In a statement obtained by Reuters, the Petroleum Facilities Guard, which provides security for Libya’s oil fields, pipelines and terminals, demanded that ‌their agency be transferred “financially ‌and administratively under the National Oil Corporation”.

They called on the ‌prime ministry and the NOC to take urgent measures ‌to complete the administrative and financial arrangements for this, and set a clear implementation timeline.

The agency currently operates under the defense ministry. The Guard said it would implement a ‌partial production cut for one week as of Tuesday at several fields including Wafa, Al-Khamsa and El Feel, adding that a complete shutdown would follow if their demands were not met.

Oil production is Libya’s main economic source, representing approximately 90 percent of the economy of the entire country. “Shutting down oil fields and halting production operations at this critical juncture — as the world witnesses a rise in crude oil prices — constitutes a devastating blow to the national economy,” the NOC said in a statement.

Source link

After the Flames at Zawiya: Why Libya Needs More than Oil

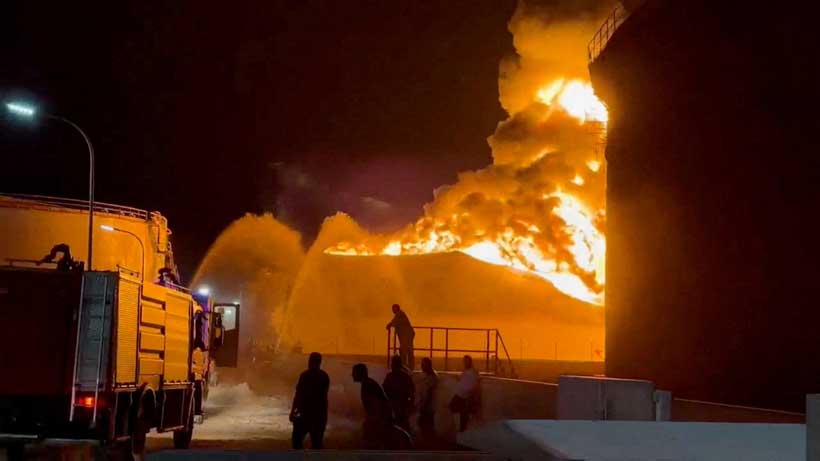
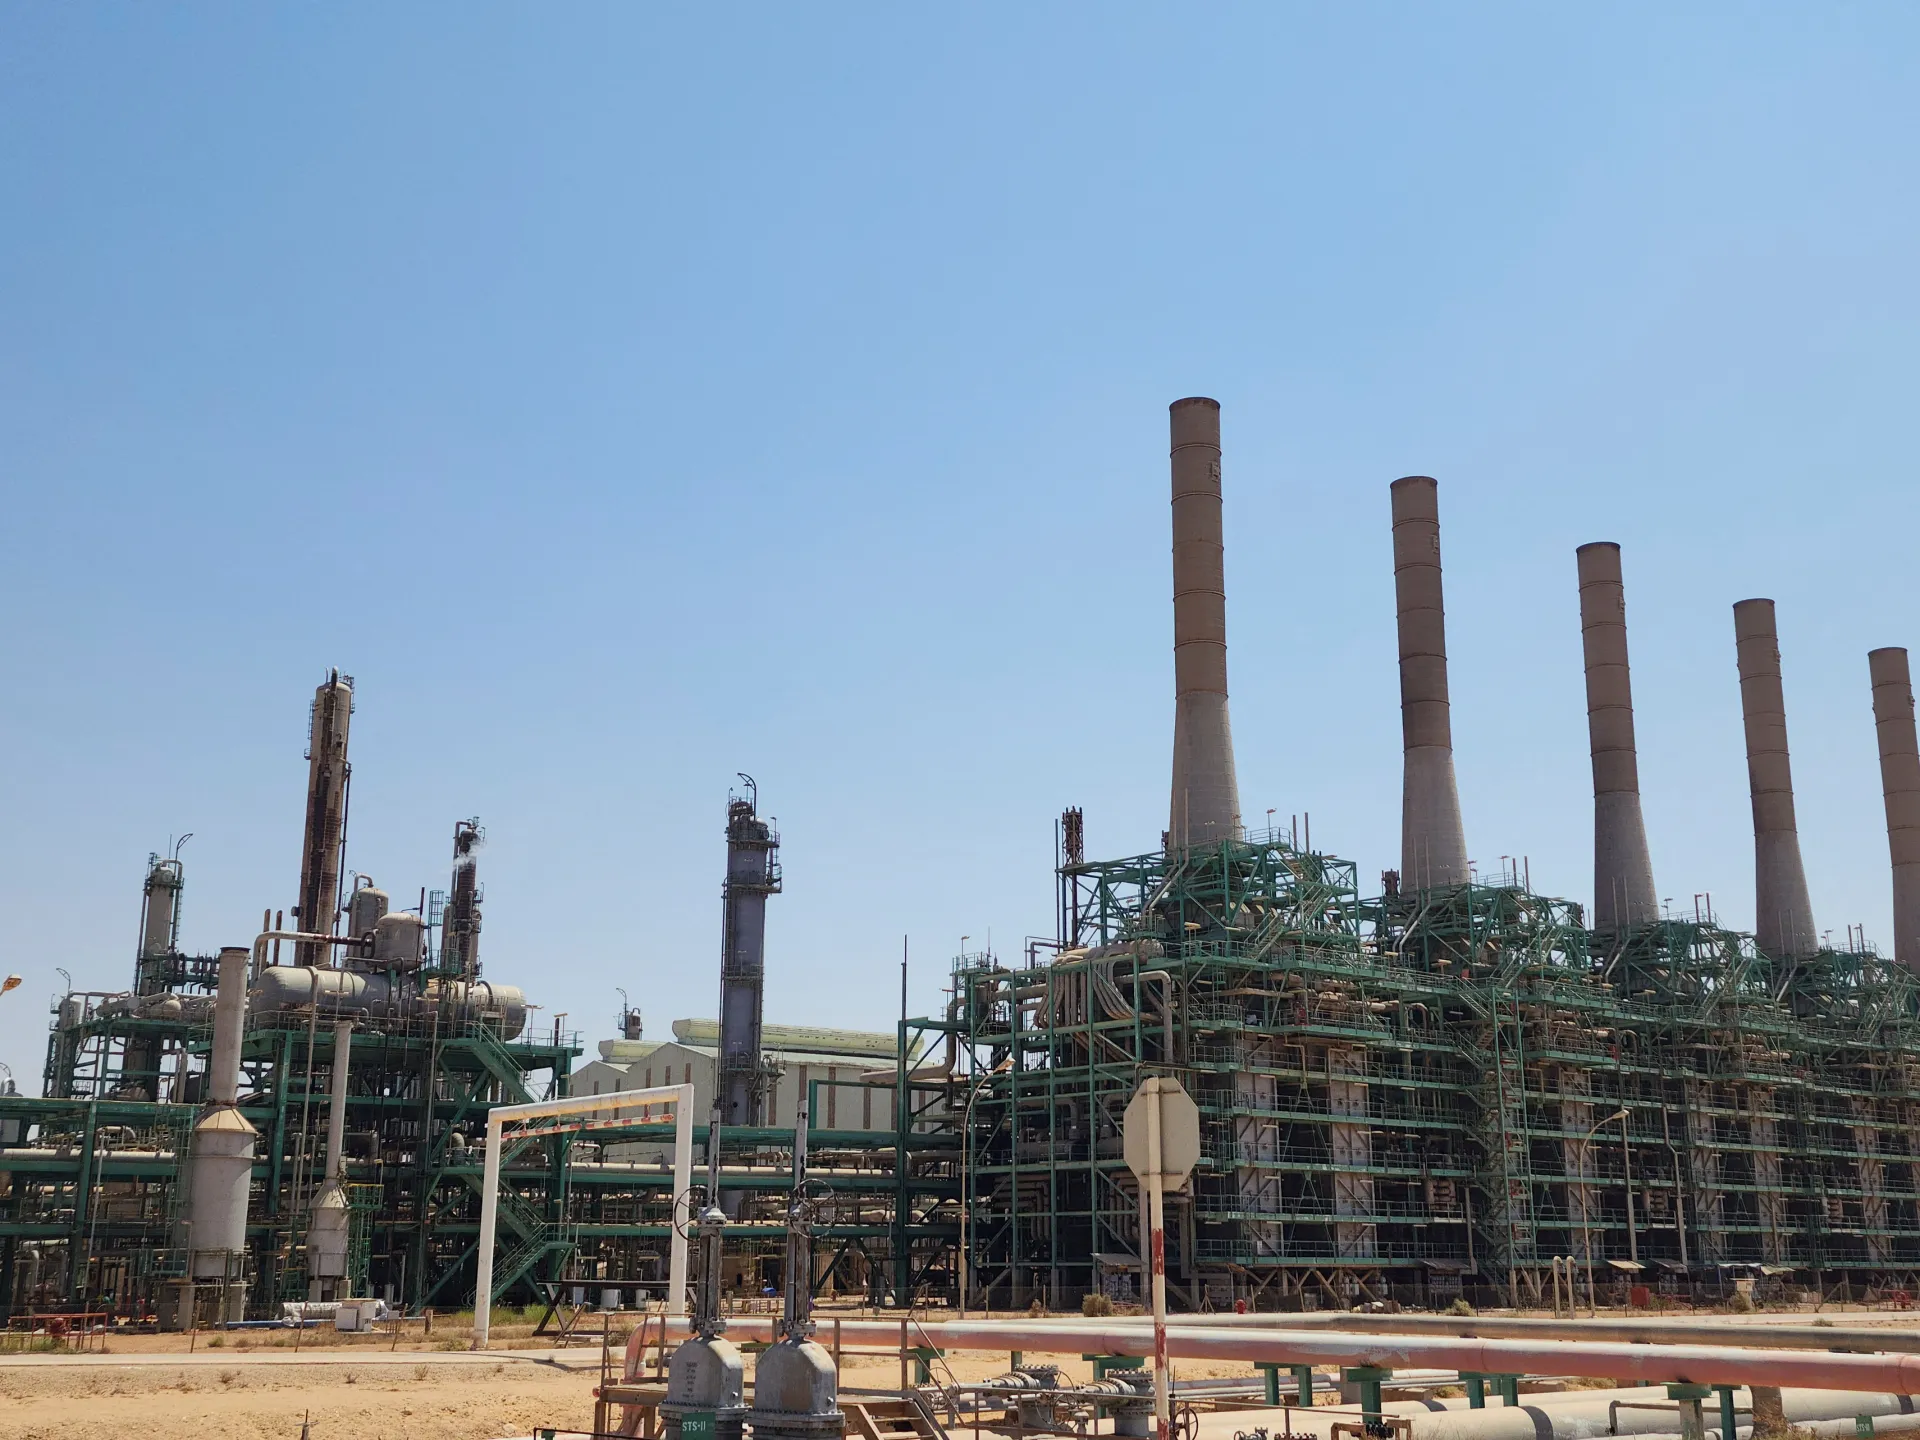
The drone strike that hit a gasoline tank at the Zawiya refinery in August was more than a security incident. Zawiya is Libya’s largest operating refining facility, and the National Oil Corporation warned that continued attacks could force operations to halt. In an economy still built almost entirely around hydrocarbons, a disruption at one major facility rarely stays local. It becomes a national economic risk.

Libya’s dependence on oil has generated enormous wealth, but it has also concentrated economic risk in a relatively narrow network of fields, pipelines, export terminals, and refineries. A disruption at any one of these nodes can threaten fuel supplies, production, and the state revenue that depends on them, reaching well beyond the site itself.

None of this means Libya should move away from oil, which will remain central to the economy for years. The more useful question is whether Libya can build enough productive capacity around it that the country’s economic future isn’t defined by the vulnerability of a handful of facilities. Diversification is often discussed in the abstract. In Libya, it is starting to take a more concrete shape, particularly in cement and steel, where investment is beginning to build an economic base around production, employment, infrastructure, and domestic value rather than around extraction alone.

Why cement is more than a construction material

Stay ahead of the geopolitical week.

MD Briefing delivers expert analysis across five global fronts — the Indo-Pacific, energy, geoeconomics, European security, and the Middle East — every Monday morning. Free.

Cement doesn’t carry the same strategic weight as oil in most conversations about Libya’s economy, but for a country rebuilding its cities and infrastructure, it arguably should. Housing, roads, and public infrastructure all depend on a steady domestic supply of building materials, and meeting that demand locally generates a different kind of value than exporting raw resources: factories, supply chains, jobs at multiple skill levels, and more of the value construction generates staying inside the national economy.

There is also an export dimension. Libya’s location and access to regional markets give a competitive cement industry real potential beyond its own borders. Suhail Abushiha, Libya’s Minister of Economy and Trade, has said the country could eventually export as much as 25 million tonnes of cement annually, a figure that indicates how far this ambition is meant to reach, even if it remains some distance from current output.

A functioning industrial sector depends on engineers, technicians, suppliers, contractors, energy, transport, finance, logistics, and maintenance, and its output in turn supports other industries and the wider construction economy. That is the multiplier effect Libya needs, not just revenue, as oil provides, but economic activity that spreads across businesses, regions, and communities. The foundations for that are already forming.

The industrial base already in place

Libya is not starting from scratch. The Libyan Cement Company in Benghazi remains one of the country’s most established industrial producers, accounting for roughly 20 percent of national cement output and supporting more than 1,000 direct jobs. Over the years, its cement has supplied major infrastructure and reconstruction projects, and its history tracks the broader shift in Libya’s private sector. In 2023 it came under the ownership of businessman Ahmed Gadalla and has since grown to become a defining industrial player in eastern Libya.

The company’s importance extends past what it produces. A major industrial operation generates demand for engineers, contractors, transportation, logistics, maintenance, and energy services, and its output feeds directly into the construction and infrastructure projects that will shape Libya’s future. Gadalla’s industrial interests go beyond cement, in fact. His involvement in the SULB steel venture, alongside Tosyalı Holding, follows the same logic of building productive capacity in sectors that support construction and long-term development.

Alongside these established players, Libya is seeing a new wave of large-scale investment. In Nalut, ALHEDAB Cement Company is developing a major project with an estimated investment of $600 million, designed to produce up to 12,000 tonnes of cement per day, one of the largest industrial projects currently under development in the country. What distinguishes the project isn’t only its scale. Around 25 percent of its capital is expected to open to public and foreign investors, with plans for a future stock market listing, which points to a shift in how large industrial projects in Libya could be financed going forward: less reliant on the state or a narrow group of private interests, and more open to broader participation.

Other producers are expanding the sector as well. Arabian Cement Company, a domestically owned producer based in Khoms, has an annual production capacity of roughly 3.3 million tonnes, and international companies including Pakistan’s Lucky Cement and Oman’s Raysut Cement have identified opportunities in the Libyan market. What matters is less any single project than the combined effect: a growing network of producers, suppliers, contractors, logistics companies, and skilled workers starts to resemble an industrial ecosystem rather than a collection of unrelated ventures.

Diversification depends on projects reinforcing each other

Libya’s economic future won’t be transformed by one factory or one investment announcement. Diversification becomes meaningful when industries start reinforcing each other: cement supports construction, construction creates demand for steel, transport, and engineering services, and new industrial facilities need energy infrastructure, maintenance, logistics, and finance in turn. Industry’s value isn’t limited to what leaves the factory. It lives in the network of activity that builds up around it, which matters for Libya in particular, since oil has financed much of the state for decades without creating a broad productive base on its own. Cement and steel fit that gap reasonably well, given that reconstruction already creates substantial domestic demand and regional markets could add export opportunities over time.

Incentives alone won’t be enough

Projects at this scale need capital, confidence, and long-term commitment. Libya has been working to strengthen the investment environment through incentives and guarantees aimed at domestic and foreign investors. Investment promotion mechanisms backed by the Public Investment Bank are meant to build investor confidence, and the investment framework has tried to encourage the transfer of foreign expertise and technology, including requirements such as health insurance for workers.

These measures matter, but they aren’t sufficient on their own. Market opportunities, natural resources, and favorable terms can draw investors in, but long-term industrial investment depends on something more basic: confidence that regulators apply the rules consistently, and that assets, workers, and supply chains can operate somewhere secure. That is where the Zawiya attack becomes relevant again.

Security, not just incentives, will determine whether this works

The refinery attack points to a challenge that goes beyond any single facility: Libya’s economic prospects can’t be separated from its security and political environment. A country can offer investment guarantees, but uncertainty erodes their value. A manufacturer weighing a multi-million-dollar factory has to account for demand and profitability, but also electricity, logistics, regulation, security, and whether operations can run consistently for years at a time. That is why economic diversification and institutional reform need to move together. Libya needs investment, but investment needs predictability just as much: clear regulations, reliable institutions, and an environment where companies can plan past the next political or security disruption.

The Zawiya attacks make that need difficult to ignore. They show how quickly insecurity can threaten assets central to the national economy, and they strengthen the case for an economy that doesn’t depend on a narrow set of sources. Diversification can’t eliminate political or security risk, but it can reduce how much of the country’s economic life hinges on a limited number of facilities.

Where this leaves Libya

The Zawiya fire is a warning about what happens when a national economy leans too heavily on a narrow group of critical assets. Libya will remain an oil producer for the foreseeable future, and hydrocarbons will continue generating a large share of national wealth. But that doesn’t mean the country’s economic future has to be defined by oil alone.

New cement plants are under development, existing producers continue to back reconstruction and employment, capital is opening to domestic and foreign investors, and international companies are moving in alongside Libyan businesses. These are early signs of a possible shift, not evidence of one already completed. Whether Libya can turn individual investments into a coherent industrial strategy will depend on more than capital and ambition. It will depend on regulatory reform, stronger institutions, security, and sustained commitment to building productive capacity, with Libya’s oil wealth funding the broader transformation rather than substituting for it.

Source link