F-15EX May Finally Get Missile Warning System The USAF Originally Skimped On Buying
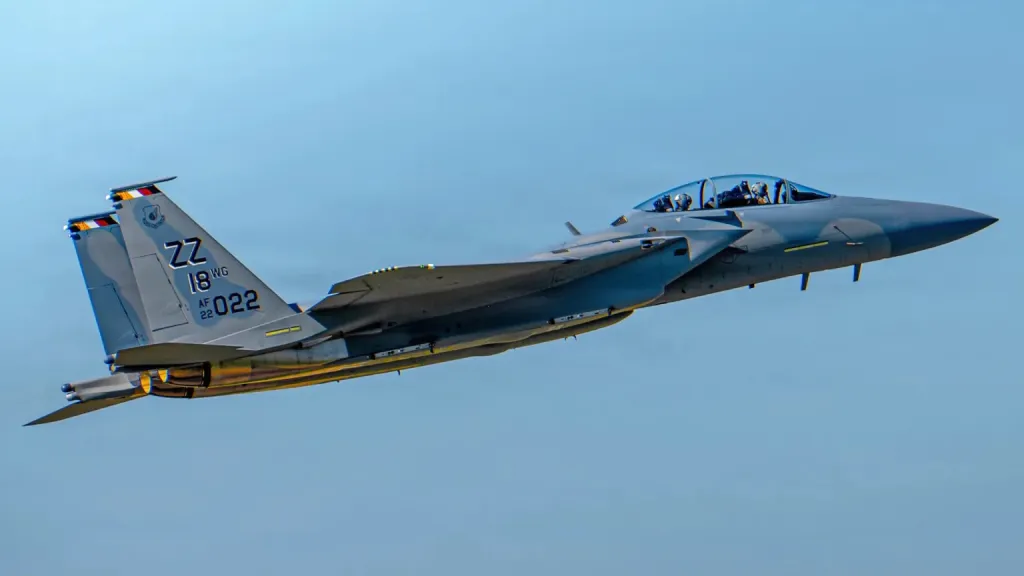
The U.S. Air Force is looking at adding a missile warning system (MWS) to its new F-15EX Eagle II fighters. This will give the aircraft a way to optically detect incoming missile threats, especially passively guided ones like heat-seeking infrared-guided missiles, which they currently lack. The continued absence of an MWS has become more pronounced in light of recent combat experiences over Iran.
The F-15EX is derived from earlier F-15 variants that all have MWSs, and it had seemed logical to expect the Eagle II would feature this capability. So it was puzzling when the first examples rolled out without such a system, and no apparent plans to install one on a jet already costing upwards of $100 million. The omission has been glaring for years now, especially given that the aircraft has all the provisions for such a system, including blanked-over spots for the sensors.

The Air Force has 22 Eagle IIs in inventory now and currently plans to acquire a total fleet of 267 of the jets. The aircraft’s manufacturer, Boeing, is on contract now to build 120 F-15EXs, including a lot of 22 jets through a new $2.38 billion deal also announced yesterday.
Now, the Air Force Life Cycle Management Center’s (AFLCMC) Fighters & Advanced Aircraft Directorate “is seeking sources for the procurement of an operationally qualified threat missile launch and approach warning system for rapid integration into the United States Air Force (USAF) F-15EX Eagle II fighter aircraft,” per a contracting notice put out yesterday. “The MWS must alert the F-15EX aircrew to the presence of missiles that may threaten the aircraft without unreasonably distracting the aircrew with false alarms.”
As mentioned, the F-15EX is already configured to accommodate an MWS, inside and out, something AFLCMC’s notice emphasizes. This is a result of the Eagle II having been directly derived from the F-15QA variant for Qatar, which itself was an outgrowth of the F-15SA for Saudi Arabia. While many of the F-15EX’s advances come from these aircraft, the first F-15 variant to get an MWS was actually Singapore’s F-15SG. The Advanced Eagle line and the F-15SG are part of Boeing’s extended F-15E Strike Eagle family.

“The MWS must use the six (6) pre-existing F-15EX sensor locations, data cables, power cables, and cooling,” the contracting notice says. “It must be easily, safely, rapidly, and organically installable and removable in the field by USAF military aircraft maintenance personnel without requiring any change to aircraft configuration beyond installation of MWS line replaceable units (LRUs) in the six (6) pre-existing locations in the aircraft dedicated for missile warning.”
Those most visually prominent of those pre-existing sensor locations are two horn-like sponsons, one on each side of the forward fuselage right below the cockpit canopy. There are two more locations at the ends of the jet’s tail booms. The last two locations are situated so additional sensors can face straight up and down to provide total 360-degree coverage.


The sources sought notice does not mention any specific MWS and invites prospective vendors to submit proposals. It also stresses that the Air Force is still in the “market research” phase of the contracting process and that it “does not constitute [a] solicitation and shall not be construed as a commitment” to buy such a system.
The F-15SA uses the AN/AAR-57 Common Missile Warning System (CMWS), and this system is understood to also be found on the F-15QA. Beyond F-15 variants, versions of the AN/AAR-57, for which BAE Systems is currently the prime contractor, are fielded today on a wide variety of other fixed-wing aircraft and helicopters, including various types in U.S. military service. CMWS variants are notably found across the U.S. Army’s AH-64, UH-60, and CH-47 helicopter fleets.


All versions of the CMWS consist of several electro-optic missile sensors (EOMS), the number of which varies from platform to platform, linked to a central electronic control unit (ECU). The system is also designed to be integrated into larger defensive suites.

While the AN/AAR-57 is a proven system with years of successful integration on the F-15 and other platforms, it is just one option of the open market today. The Air Force could choose to take another route, possibly with a new system that offers added functionality.
The addition of any MWS will give the F-15EX a valuable, if not increasingly critical, boost in defensive capability. The Eagle II does already have an extremely powerful self-protection suite, including the Eagle Passive/Active Warning Survivability System (EPAWSS). However, it is heavily geared toward defending against radar-based threats that pump out signals that can be detected and jammed. Infrared-homing anti-air missiles zero in on their targets passively.

Eagle Passive Active Warning Survivability System (EPAWSS) l BAE Systems
In general, MWSs also typically make use of passive infrared sensors to spot the heat plumes of missile launches and the thermal signatures of those threats as they continue their approach. BAE Systems says current-generation versions of the AN/AAR-57 are sensitive enough to detect infantry anti-armor rockets being launched, as well as small arms fire from the ground, under the right circumstances. Though an MWS is not an active countermeasure unto itself, the early warning it provides gives critical time to deploy flares or employ other defensive capabilities, or just take evasive action.
TWZ touched on all of this last month after The New York Times reported new details about the shootdown of an F-15E Strike Eagle over Iran in April. A shoulder-fired, heat-seeking surface-to-air missile, also known as a man-portable air defense system (MANPADS), is said to have been responsible, thought his remains unconfirmed. The Strike Eagle also lacks an MWS. The Times‘ story said that the F-15E’s defensive suite provided the crew with only half a second of warning. As we noted at the time, it would actually have provided no warning given that the Strike Eagle also lacks an MWS.

Even before the current conflict with Iran broke out, TWZ had questioned the F-15EX’s lack of this capability given the general focus on increased survivability to match expanding threat ecosystems globally. EPAWSS is already a reflection of that reality, and could be made even more capable when tied together with an MWS. In May, we had reached out to the Air Force about any plans to integrate an MWS onto the F-15EX in light of observations from the ongoing conflict with Iran. The service told us then that it had no details to share. Whether the service now has any plans to add MWSs to the Strike Eagle fleet, which would require more significant integration work, is also unknown.
Infrared homing anti-air missiles, as well as air defense systems that use passive infrared sensors for target detection and cueing, are certainly not threats limited to Iran. In Yemen, Iranian-backed Houthi militants have been making good use of these capabilities for years now, something else we have explored in great detail in the past. The Houthis claimed to have downed a Saudi Arabian F-15 just earlier this month and, per a now-long standing modus operandi, subsequently released video captured through a ground-based forward-looking infrared (FLIR) system as evidence. The group also shared images of the wreckage of what looked to be an F-15SA Advanced Eagle, underscoring the dangers posed even to aircraft equipped MWSs.
These threats are not limited to the Middle East more broadly, either, and are only increasingly likely to be encountered in future conflicts globally. The emergence of ever-more capable and longer-range anti-air missiles with infrared or dual-mode guidance systems is a significant factor in all this. Expanding use of passive infrared search and track (IRST) systems on aircraft and infrared sensors on ground-based air defense systems are part of this larger equation, as well.
How the Air Force ultimately decided to proceed with the integration of an MWS onto the F-15EX fleet remains to be seen. However, the Eagle II’s lack of this capability is only becoming more striking, especially in light of the conflict with Iran.
Contact the author: joe@twz.com
Central Banks Are Buying Gold Like De-Dollarization Is Already Happening — Are They Right?
Central banks’ record, price-insensitive gold buying is a more credible signal of the dollar’s structural trajectory than this year’s currency markets, because FX markets are structurally bad at pricing the discontinuous, wartime-style tail risk central banks are actually hedging — so this autumn’s calmer dollar should not reassure anyone that de-dollarization has stalled.
In June, the European Central Bank made an announcement most people missed: gold has overtaken US Treasuries as the world’s single largest reserve asset. Central banks bought 289 tonnes of it in the second quarter alone — a record for that quarter and five times Q1’s pace — with Poland’s central bank openly telling investors it was “buying the dip.” Here is the part that should stop you: gold’s price fell 22% between January and September. Central banks were never more convinced buyers of an asset than while it was crashing. Either the reserve managers are wrong, or currency markets — which show none of this urgency — are the ones asleep at the wheel.
Gold peaked at $5,589 an ounce on 28 January, the same month the dollar index hit a four-year low of 95.5 and the dollar’s share of global reserves fell toward its lowest level since 1995. Both moves reflected the same story: Fed rate cuts through 2025, a US debt load past $37 trillion, and BRICS states settling more trade outside the dollar. Then the picture split. Kevin Warsh, confirmed as Fed chair in May, signalled a hawkish pivot in August; the Iran war pushed oil and inflation higher through September, and markets began pricing a rate hike rather than a cut. The dollar index clawed back to 99.46. Gold fell to $4,330. Central-bank buying did not follow the price down — Poland alone added 82 tonnes this year toward a 700-tonne target, and a World Gold Council survey found a record 45% of central banks plan to buy more within twelve months.
State the gap plainly. Two signals, same underlying question — is the dollar-centred monetary order changing — and they disagree by a wide margin. The buying signal says yes, decisively: record quarterly purchases, gold displacing Treasuries at the ECB’s own reckoning, 74% of surveyed reserve managers expecting the dollar’s reserve share to keep falling over five years, and buyers adding tonnage through a 22% drawdown rather than fleeing it. The price signal says not yet: the dollar just posted one of its sharper rallies of the year, gold is down sharply from its high, and nothing in currency markets shows the kind of stress a genuine regime shift would produce.
Stay ahead of the geopolitical week.
MD Briefing delivers expert analysis across five global fronts — the Indo-Pacific, energy, geoeconomics, European security, and the Middle East — every Monday morning. Free.
The strongest objection to trusting the buying signal is a good one, and it needs to be taken seriously rather than waved away: foreign exchange is the deepest, most liquid market in the world, turning over more than $7 trillion a day. A few hundred tonnes of central-bank gold buying — perhaps $30–40 billion a quarter — is a rounding error against that. If professional currency traders, sitting on far more capital and far better short-term information than a handful of reserve managers, saw a serious de-dollarization story unfolding, it would already be in the price. Instead the dollar just rallied. On this view, central banks are not seeing something markets are missing; they are pattern-matching off 2022, when Russia’s $300 billion in reserves was frozen overnight, and over-hedging a tail risk that has not recurred and mostly will not.
That objection assumes FX markets and central-bank reserve committees are pricing the same kind of risk, on the same time horizon, and they are not. Currency markets are exceptionally good at pricing continuous, high-frequency variables — rate differentials, growth surprises, this week’s inflation print — because that is what moves flows daily. They are structurally poor at pricing discontinuous, low-probability events until those events occur: equity volatility did not price 2008 in 2007; sovereign spreads did not price the Russia reserve freeze in the weeks before it happened. A reserve freeze, a secondary-sanctions campaign, or exclusion from SWIFT-style settlement infrastructure is exactly that kind of event — binary, rare, and catastrophic for whoever it hits — which is precisely why Poland’s central bank governor, Adam Glapiński, described his buying not as a trade but as insurance: reserves that keep the state secure “under all circumstances, including wartime, which of course we’re not expecting.” That is not the language of someone chasing momentum. It is the language of someone who manages the one asset class that keeps its value if their country is ever cut off from the dollar system, and who would rather hold it and be wrong for a decade than not hold it and be wrong once.
The buying pattern itself supports that reading. Momentum money sells into a 22% drawdown; insurance money adds to it. Central banks did the latter through the first half of this year, which is the behavioural signature of a structural reallocation program with a fixed multi-year target — Poland’s is explicit, 700 tonnes — not speculative flow riding gold’s rally. Meanwhile the dollar’s autumn recovery has an identifiable, largely cyclical cause: a new, more hawkish Fed chair and a war-driven oil shock forcing a rate-hike repricing. Neither event reverses the debt trajectory, the BRICS settlement trend, or the reserve-freeze precedent that pushed the dollar to a four-year low in January. A rally built on this year’s Fed chair and this year’s war is not proof that last year’s structural story is over; it is evidence that a cyclical force is currently strong enough to mask it.
The Scenarios
Base case (55%): The gap persists rather than resolves. The dollar holds most of its autumn gains through the current rate-hike cycle, gold range-trades below its January peak, and central banks keep buying at a steadier, slower pace toward stated targets like Poland’s 700 tonnes. Nobody is “proven right” on any particular Tuesday, because reserve diversification is a decade-scale hedge, not a trade with a catalyst date. This is the least satisfying outcome for anyone wanting a verdict, and the most likely one.
Downside case (for dollar holders): A discrete trigger — a fresh reserve-freeze or secondary-sanctions episode, plausibly connected to the still-live US-Iran war spilling into action against a third country’s assets, or a shock to Fed independence under a more political Warsh chairmanship — crystallizes the exact tail risk central banks have been hedging. Gold spikes back through its January high, the dollar index breaks below its 95.5 low, and the gap closes in weeks rather than years, vindicating the reserve managers all at once and catching FX markets flat-footed exactly as the theory predicts.
Upside case (for the dollar): The Iran war resolves, Warsh’s rate hikes cool inflation without a recession, US fiscal metrics stabilize, and BRICS local-currency settlement growth stalls on friction between its own members. Central-bank gold buying does not reverse but plateaus as reserve managers hit conventional diversification ceilings — most target 15–20% of reserves in gold, not open-ended accumulation. The gap closes gradually as price drifts up toward the buying signal over several years, with no crisis required to force the reconciliation.
The Takeaway
The dollar’s calmer autumn is not evidence the de-dollarization hedge was a mistake; it is evidence that currency markets and central-bank reserve committees are pricing two different things on two different clocks, and only one of those clocks rings in a crisis. Central banks bought through a 22% drawdown because the point of the position was never this quarter’s return.
Watch for: the World Gold Council’s Q3 2026 Gold Demand Trends report, expected in early November. A third consecutive quarter of buying that ignores price direction will confirm this is policy, not opportunism — and the moment currency markets have to agree with that policy will not be a quiet one.